Just in:
Toward a Shared Future for Humanity: Rethinking Civilizational Exchange // Fungal toxins detected across 212 UK plant-based products // Ex-minister named accused in Messi visit fraud case // Dubai Introduces SHARH, an AI-Powered Platform Helping Entrepreneurs Buy, Sell and Manage Businesses in the UAE // Yeebo Announces Interim Results for FY26/27 Revenue Increases by 45.5% to HK$806.7 Million Profit Attributable to Owners Surges 87.6% to HK$2,284.7 Million // Workday targets Honeydew purchase to unify AI metrics // Russia permits retail cryptocurrency purchases under regulated framework // ED searches five districts in probe against hawala // Jaiedco and Golden Bridge Announce Strategic Collaboration for a New Dubai Islands Development // Dalilk Academy reaches 27 million, targets 100 million by 2030 // Technology at Work, Heritage for All: The “Chinese Approach” to Safeguarding the Leshan Giant Buddha // Bail refused to 17-year old in Abhiram murder // Balagopal challenges CM over tax revenue // Sui activates Hashi Bitcoin lending across partner network // Promoting Common Human Development Through Exchanges and Mutual Learning Among Civilizations // Sabarimala booking discrepancies prompt sabotage angle probe // Padmini follows Padmaja for ‘ghar vapsi’ // US military rebuts Iran’s Gulf F-16 strike allegation // Diabetes Malaysia And Alpro Pharmacy Set National Record With 11,007 Most Blood Glucose Screenings Conducted Across Malaysia In Just 48 Hours // Saudi defences destroy three Houthi missiles targeting Riyadh //

News related to
profit

Arabian Post Staff -Dubai Alpha Dhabi Holding has doubled its capital commitment to the Mubadala Capital-managed MICAD Credit joint venture to $1 billion and raised its ownership stake to 40 per cent from 20 per cent, expanding its exposure to global private credit. The Abu Dhabi Securities Exchange-listed investment group said the revised partnership agreement also broadens MICAD Credit JV’s mandate beyond its existing US and European […]

Highlights of the Interim Results for the Six Months Ended June 30, 2026:

  • Benefiting from sustained strong chip demand across the AI data center (“AIDC”), storage and robotics sectors, the Group’s revenue increased by approximately 98.4% year-on-year to approximately RMB13,249.2 million;
  • The Group recorded gross profit of approximately RMB799.7 million and net profit of approximately RMB373.0 million. Profit attributable to equity shareholders of the Company amounted to approximately RMB278.9 million, representing a year-on-year increase of approximately 111.1%;
  • The Group has strategically upgraded from an “AI hardware distributor” into a “Token computing power operator”, opening up a second growth curve; and
  • The Group has formally entered into Token computing power services contracts worth more than US$1 billion, with delivery expected to commence in the fourth quarter of 2026.

HONG KONG SAR – Media OutReach Newswire – 31 August 2026 – Ingdan, Inc. (“Ingdan” or the “Company”; Stock Code: 400.HK, together with its subsidiaries, the “Group”), an ecosystem services platform anchored in artificial intelligence (“AI”) chips and principally engaged in the businesses of “Comtech” and “Ingdan” today announced its unaudited interim results for the six months ended June 30, 2026 (the “First Half of 2026” or the “Period”).

Financial Highlights for the First Half of 2026

During the Period, benefiting from sustained strong chip demand across the AIDC, storage and robotics sectors, the Group recorded revenue of approximately RMB13,249.2 million, representing an increase of approximately 98.4% from approximately RMB6,676.5 million for the corresponding period in 2025.

The Group’s gross profit amounted to approximately RMB799.7 million, representing a year-on-year increase of approximately 36.5%. Operating profit was approximately RMB517.2 million, representing a year-on-year increase of approximately 87.7%. Net profit after tax amounted to approximately RMB373.0 million, representing a year-on-year increase of approximately 96.3%.

Business Review

Strategic Upgrade Milestone: Token Factory Order Formally Secured, Opening Up a Second Growth Curve

During the First Half of 2026, the Group achieved a landmark breakthrough in its AI-driven strategic upgrade. The previously disclosed intent service orders exceeding US$1 billion have now been formalized into services contracts. Delivery is expected to commence in the fourth quarter of 2026, with the contracts expected to generate aggregate service revenue of more than US$1 billion over the next five years. This milestone signifies a fundamental evolution in the Group’s growth model—from “selling chips” to “selling computing power”—and its formal upgrade into an “Token computing power operator”, presenting a compelling new value proposition to the capital markets.

Three Growth Drivers for Rapid Expansion

The Group’s performance growth is supported by three core drivers:

  • AI computing power: The accelerating development of global data centers continues to drive strong demand for GPUs and CPUs. The Group provides full-stack computing power support, from chips to application solutions, and is deeply involved in the development of cloud-based intelligent computing centers;
  • Storage cycle: Surging demand for AI foundation model training and inference is driving expansion in the memory chip market. Leveraging the resources of leading global suppliers, the Group ensures a reliable supply of memory chips and complementary solutions; and
  • Embodied intelligence and robotics: As humanoid robots enter the mass-production stage, the Group is strengthening its full-stack deployment, from edge AI computing solutions built around platforms such as NVIDIA Jetson to enterprise-level computing clusters.

Full-Chain Technology Services Platform

As a technology services platform based on AI chips, the Group connects upstream AI chip technologies with the needs of downstream innovative enterprises. Leveraging the resources of leading global chip manufacturers, including NVIDIA, Intel, AMD and SanDisk, the Group has established a comprehensive product portfolio covering GPUs, CPUs, FPGAs, ASICs, memory chips and software ecosystems. With chip distribution serving as its entry point, the Group provides customers with integrated, full-chain services encompassing technology solutions, supply chain management, technical training, and after-sales operation and maintenance. Its services cover a broad range of application scenarios, including cloud-based intelligent computing centers, edge AI, robotics, drones and enterprise-level computing power services.

Global Computing Power Network Deployment

To support the large-scale delivery of its Token factory business, the Group is accelerating the development of a global computing power network. In the near term, it plans to expand its computing centers footprint into multiple Asian countries, with total planned computing capacity exceeding 100 megawatts. Through its proprietary Token computing power scheduling platform, the Group provides one-stop services encompassing computing power scheduling, cluster operation and maintenance, and Token computing power services. Its customers include leading internet cloud service providers and market-leading enterprises in vertical robotics segments, demonstrating the commercial viability of the Group’s business model.

Outlook

Mr. Jeffrey Kang, Chairmanand CEO of Ingdan, Inc., commented: “As demand across AIDC, storage, robotics and AI Token services continue to grow, the Group’s strategic positioning as a ‘Token computing power operator’ has been further strengthened. We expect robust customer demand in the second half of the year, while the AI Token factory business is expected to become the Group’s second growth curve. This will further enhance the capital market’s recognition of the visibility of the Company’s growth and its long-term development potential.”

Cautionary Statement

The information contained in this document has not been independently verified. Neither the Company nor any of its affiliates, advisers or representatives makes any express or implied representation, undertaking or warranty as to the fairness, accuracy, completeness or correctness of the information or opinions presented or contained herein. No person should rely on this document as a basis for any decision.

The information contained in this document should be considered in the context of the circumstances prevailing at the relevant time and is subject to change without notice. The Company undertakes no obligation to update the information contained herein to reflect any developments occurring after the date of this document. This document is not intended to provide, and should not be relied upon as providing, a complete or comprehensive analysis of the Company or its financial or operating condition or prospects. Neither the Company nor any of its affiliates, advisers or representatives shall have any obligation or accept any liability, whether in negligence or otherwise, for any loss arising from any use of this document or its contents or otherwise arising in connection with this document.

This document may contain statements reflecting the Company’s current intentions, beliefs and expectations regarding the future as of the relevant dates indicated herein. Such forward-looking statements do not constitute guarantees of future performance. They are based on certain assumptions concerning the Company’s operations and on factors beyond the Company’s control, and are subject to significant risks and uncertainties. Accordingly, actual results may differ materially from those described in such forward-looking statements. Neither the Company nor any of its affiliates, advisers or representatives has any obligation or undertakes to update any forward-looking statement to reflect events or unforeseen circumstances arising after the relevant date.

Hashtag: #Comtech #Ingdan #AI #AIDC #TokenFactory #IC #Chips #humanoid #Intel #AMD #Sandisk #NVIDIA #Tech #RevenueGrowth #TechGrowth #AIInvestment #ProprietaryProducts #KeplerLab #Comtech #IngdanTechnology #IngdanAcademy #AIAcceleration #TechTransformation

The issuer is solely responsible for the content of this announcement.

Ingdan, Inc.

Ingdan, Inc. (Stock Code: 400.HK) is an ecosystem services platform anchored in artificial intelligence (“AI”) chips. The Group captures the rapidly growing demand across numerous industries, from AI computing centers to AI-powered intelligent terminals, by converting AI chip resources into a broad range of rapidly deployable application solutions that provide the core driving force for customers’ intelligent upgrade. Through its proprietary AI technologies, large models and specialized industry knowledge bases, the Group provides customers with advanced chip application technology solutions and efficient supply chain management services.

Headquartered in Shenzhen, the Group operates offices and branches across major cities in China, including Hong Kong, Beijing, Shanghai, Guangzhou, Hangzhou , Suzhou, Wuhan and Chengdu, as well as operations in Singapore and Japan. The Group’s core businesses are Comtech — a technology services platform for the chip industry; and Ingdan — a platform providing Artificial Intelligence of Things (“AIoT”) technology and services.

For further information, please refer to the Company’s website at

Proposed an interim dividend of HK11.0 cents per share

Highlights:

  • Revenue increased to approximately HK$1,450.9 million.
  • Gross profit increased to approximately HK$518.8 million.
  • Profit attributable to owners of the Company amounted to approximately HK$116.2 million.
  • As at 30 June 2026, the Group operated a total of 190 chain retail stores
  • Basic earnings per share was approximately HK11.6 cents. The Board recommended the payment of interim dividend of HK11.0 cents per share.

Financial Highlights:

For the 6 months ended 30 Jun
HK$’000 2026 2025 Change
Revenue 1,450,897 1,436,576 +1.0%
Sales derived from private label products 277,194 251,203 +10.3%
Gross profit 518,758 518,177 +0.1%
Interim dividend per share (HK cents) 11.0 11.0 –

HONG KONG SAR – Media OutReach Newswire – 31 August 2026 – Best Mart 360 Holdings Limited (“Best Mart 360” or the “Company”, together with its subsidiaries, the “Group”; stock code: 2360.HK), a leading leisure food retailer in Hong Kong, announced its interim results for the six months ended 30 June 2026 (“the Period under Review”). During the Period under Review, the revenue recorded by the Group amounted to approximately HK$1,450,897,000, representing an increase of approximately 1.0% as compared to approximately HK$1,436,576,000 for the six months ended 30 June 2025 (the “Corresponding Period Last Year”).

During the Period under Review, profit attributable to owners of the Company amounted to approximately HK$116,221,000.

For the six months ended 30 June 2026, gross profit of the Group was approximately HK$518,758,000, representing an increase of approximately 0.1%, as compared to gross profit of approximately HK$518,177,000. Gross profit margin during the period was approximately 35.8%. During the Period under Review, basic earnings per share of the Group was approximately HK11.6 cents. The Board recommended the payment of interim dividend of HK11.0 cents per share.

BUSINESS REVIEW

CHAIN RETAIL STORES

As at 30 June 2026, the Group operated a total of 190 chain retail stores, including 184 chain retail stores in Hong Kong and 6 chain retail stores in Macau, respectively. During the Period under Review, the Group continued to implement its store network optimization strategy to fully showcase its diverse product portfolio, further enhance its overall brand image and provide customers with a more comfortable shopping environment.

Since 2021, the Group has launched its brand of global wine and food stores “FoodVille”, which provides mid-to-high-end, premium food products from around the globe. These include fine wines, premium chocolates, health foods, cheese, Western sauces and ingredients from around the world, aming to cater to the market’s pursuit of a quality of life and expanding the Group’s customer base. As at 30 June 2026, the Group operated a total of 8 retail stores under the brand.

During the Period under Review, the rental expenses (on a cash basis) of the Group’s retail stores accounted for approximately 9.7% of its sales revenue.

THE PRODUCTS

During the Period under Review, the Group adhered to its global procurement strategy, sourcing high-quality products from around the world to provide customers with a diversified range of choices. During the Period under Review, the Group sold over 1,045 brands and more than 3,054 stock keeping units (“SKUs“) of products in total. The Group continuously optimised its product portfolio and actively introduced a variety of new products and flavours to meet customers’ ever-changing needs.

To enrich its product mix and maintain effective control over product quality, supply stability and profit margins, the Group continued to actively develop its private label products. During the Period under Review, sales derived from private label products amounted to approximately HK$277,194,000 (six months ended 30 June 2025: approximately HK$251,203,000), which accounted for approximately 19.1% of the Group’s total revenue for the Period under Review. The Group had a total of 12 private labels covering approximately 272 SKUs of products, including masks, canned Chinese delicacies, cereals, milk, honey, nuts and dried fruits as well as a wide range of leisure food products.

MEMBERSHIP SCHEME AND MARKETING & PROMOTIONAL ACTIVITIES

As at 30 June 2026, the Group had a cumulative total of approximately 2,469,754 registered fans and members (30 June 2025: approximately 2,243,198). As at 30 June 2026, the number of mobile app members reached approximately 1,374,462 (30 June 2025: approximately 1,238,775).

During the Period under Review, the Group continued to carry out a variety of marketing activities, including “Best Price”, “Instant Redemption upon Purchase” and other promotional campaigns, which provided customers with a series of special offers on selected quality products as a way to show its appreciation for their support and effectively enhance customer loyalty. The Group also launched a new brand promotion campaign, namely “Best Mart, Always a Friendly Buy”, in 2026. By integrating online and offline promotional channels, the Group further strengthened its brand image and enhanced its interaction and connection with customers.

The Group also utilised a variety of outdoor media, such as large-scale advertisements at MTR stations and truck wraps, together with marketing strategies on digital media and social platforms, to further increase its brand exposure and market penetration, thereby attracting more new customers to shop at its stores.

In addition, the Group actively fulfilled its corporate social responsibility by partnering with the charitable foundation under China Merchants Group to launch the “Care 360˚” Neighborhood Support Programme, which aids families in need, continuously promotes community care and inclusion and actively puts into practice the core principles of corporate sustainability.

EMPLOYEES

As at 30 June 2026, the Group employed a total of 1,257 full-time and part-time employees (31 December 2025: 1,227). The increase in the total number of employees was primarily due to the Group’s recruitment of additional staff for its newly opened stores. To retain talent and provide its employees with appropriate incentives to enhance their sense of belonging and loyalty, the Group regularly reviews and updates its employee remuneration packages and benefit plans, taking into account labour market supply and remuneration trends as well as individual employee performance. During the Period under Review, the staff costs of the Group (excluding emoluments of the Directors) accounted for approximately 9.6% of its total revenue (six months ended 30 June 2025: approximately 9.7%).

OUTLOOK

Global geopolitical tensions remain high, and uncertainty persists regarding the pace of the external economic recovery. Meanwhile, the active expansion of mainland Chinese e-commerce platforms into Hong Kong has driven the popularity of cross-border online shopping, further intensifying competition in the local retail market. Amid complex and increasingly competitive market conditions, the overall business environment for the retail sector is expected to remain under pressure in the second half of 2026. However, as Hong Kong hosts a series of major international events and exhibitions as well as cultural and sports activities, the number of visitors to Hong Kong and their willingness to spend are steadily recovering. At the same time, consumption of daily necessities has demonstrated strong resilience. Market demand for value-for-money globally sourced food products and healthy snacks continues to grow, presenting the Group with solid development opportunities. Looking ahead, the Group remains cautiously optimistic about its business prospects. To address intense market competition, we are committed to refining operational management, optimizing business processes, and maintaining strict cost controls.

To further strengthen its connection with consumers, the Group officially launched a rebranding campaign in June 2026, adopting “Best Mart, Always a Friendly Buy” as its new core brand value and striving to build a more welcoming, youthful, vibrant and creative brand image. Regarding its store network management, the Group will balance strategic expansion with operational optimization. On one hand, the Group will capitalise on appropriate market opportunities and continue to expand its footprint through a “dual-brand” strategy featuring “Best Mart 360˚” and “FoodVille”, aiming to precisely meet the demand for high-quality food across different customer segments. On the other hand, the Group will adhere to strict capital-return discipline by actively negotiating with landlords for more flexible and reasonable lease terms, while regularly reviewing the operational efficiency of existing stores. Through these efforts, the Group aims to comprehensively enhance the overall profitability of its network and deepen its presence in the mass retail market.

Faced with a complex, ever-changing and highly competitive market environment, the Group is comprehensively exploring and researching the application of artificial intelligence in its business processes, aiming to enhance operational efficiency through innovative technology. The Group will further deepen its online-offline integration strategy, fully leverage the advantages provided by the extensive member database of its mobile app and implement targeted marketing through big data analysis to effectively increase member engagement and overall repeat purchase rates.

In terms of online channels, the Group will strengthen its collaboration with the foodpanda mall platform to ensure a seamless shopping experience. The Group will also remain agile in our operational strategies to optimize overall sales performance.

Guided by its core brand philosophy of “Best Quality” and “Best Price”, the Group will make every effort to expand its upstream supplier network while ramping up the development of its private label products. These initiatives will solidify our competitive pricing advantage while effectively meeting the market demand for daily necessities. The Board is confident that, through prudent yet flexible strategic planning, strong brand appeal and an optimised product portfolio, the Group will successfully enhance customer loyalty. This will steadily drive the business toward sustainable growth, thus creating long-term and robust returns for shareholders.

Hashtag: #BestMart360

The issuer is solely responsible for the content of this announcement.

About Best Mart 360 Holdings Limited

Best Mart 360 Holdings Limited, mainly operates chain retail stores under the brand “Best Mart 360˚”. It offers a wide collection of imported prepackaged leisure foods and other grocery products, principally from overseas. The Group’s business objective is to offer “Best Quality” and “Best Price” products to customers through continuous efforts on global procurement with a mission to provide comfortable shopping environment and pleasurable shopping experience to customers. As at 30 June 2026, the Group operates 190 retail stores that are strategically located across 18 districts in Hong Kong and Macau. In addition, the Group’s new global gourmet store, “FoodVille”, was officially opened in September 2021, which mainly provides globally sourced medium-to-high-end quality food products.

Matein Khalid Chinese fast-fashion giant Shein is set to list in Hong Kong on September 1 at a valuation of up to $27 billion. That is less than half the $64 billion valuation at which Abu Dhabi sovereign wealth fund Mubadala invested in 2023. It is a brutal comedown for a retailer once expected to be worth $100 billion. My knowledge of sartorial retailing is admittedly less than encyclopaedic. Yet I […]

Arabian Post Staff -Dubai Gulf companies are pouring money into artificial intelligence, but many are finding that rapid adoption is not translating into measurable financial returns as weak data foundations, fragmented technology systems and governance gaps constrain deployment at scale. Around 84% of organisations across the Gulf are using AI in some form, yet only about 11% have reached a level where scaled deployments are producing clearly […]

PayPal-linked exchange-traded funds suffered steep losses on Friday after Stripe and Advent International abandoned their pursuit of the payments company, wiping out much of the takeover premium that had built into PayPal-related investments. PayPal Holdings shares closed 12.7% lower at $53.66 on August 28 after reports that the consortium had stopped pursuing a transaction valued at more than $50 billion. The sell-off was amplified in leveraged ETFs […]

Strengthening Competitiveness via Online-to-Offline Integration and Supply Chain Agility

Results Highlights

  • Revenue reached US$301.51 million, representing a strong increase of 23.2%.
  • Gross profit grew by 28.2% to US$93.98 million, with gross profit margin expanding to 31.2%.
  • Operating profit increased by 30.1% to US$24.29 million.
  • Net profit surged by 30.0% to US$18.30 million, with net profit margin improving to 6.1%.
  • Business-to-consumer (B2C) platform YesStyle recorded revenue of US$215.07 million, up 30.5%, accounting for 71.3% of the Group’s total revenue. Offline expansion was enhanced with the opening of its first physical concept store in the US.
  • Business-to-business (B2B) platform AsianBeautyWholesale (ABW) recorded revenue of US$82.75 million, up 6.2%, accounting for 27.4% of the Group’s total revenue.

HONG KONG SAR – Media OutReach Newswire – 28 August 2026 – YesAsia Holdings Limited (“YesAsia Holdings”, together with its subsidiaries, the “Group”) (2209.HK), a leading e-commerce platform operator recognized for its expertise in curating Asian beauty and lifestyle products, announced today its interim results for the six months ended 30 June 2026 (the “Reporting Period”).

The Group continued to capture strong global demand for Korean Beauty (“K-Beauty”) products, driving revenue up by 23.2% year-on-year to US$301.51 million. Gross profit increased by 28.2% to US$93.98 million, with gross profit margin expanding by 1.2 percentage points to 31.2%. Operating profit grew by 30.1% to US$24.29 million. Benefiting from forward-looking investments in localized and tech-driven logistics infrastructure, which successfully mitigated geopolitical and freight cost pressures, profit for the period surged by 30.0% to US$18.30 million, after recognition of an one-off expense of approximately US$1.24 million in termination benefits arising from the organizational streamlining. Net profit margin improved to 6.1%. Basic earnings per share were US4.39 cents (1H 2025: US3.43 cents).

Navigating Uncertainties through Market Diversification and Logistics Agility

A global market footprint remains pivotal in mitigating geopolitical risks. The US, the Group’s largest market, has absorbed the tariff shock and delivered progressive improvement during the Reporting Period, with revenue exceeding 2H 2025 even outside the typical holiday peak season. Among non-core markets (excluding the US, the UK, Canada, and Australia), robust demand across Europe and Latin America, unlocked new growth momentum, with revenue from Europe and associated countries and Latin America growing by 22.1% and 178.4%, respectively. In the Middle East, the Group navigated the regional tensions to achieve steady revenue growth of 33.4%.

Complementing market diversification, strategic investments in logistics infrastructure spanning Hong Kong, South Korea, the US, and Europe, alongside the adoption of automation technologies like AMRs, have built a highly resilient and scalable supply chain. These capabilities enabled the Group to maintain a stable baseline for business costs and absorb freight and fuel price spikes stemming from Middle East conflicts during the Reporting Period. Consequently, the increase in operating costs remained well below revenue growth, with freight cost as a percentage of revenue dropping to 19.0%, demonstrating the Group’s robust cost control and operational agility.

Integrating O2O Experiences to Drive B2C-B2B Dual-Engine Synergy

Social media marketing remained one of the Group’s core strengths during the Reporting Period, supported by an ecosystem of over 557,000 unique influencers that generated US$85.70 million and contributed nearly 40% of YesStyle‘s revenue. To amplify this online impact, the Group strategically expanded its global offline presence to seamlessly bridge online and offline customer experiences. YesStyle debuted a 1,500 sq. ft. concept store in the San Francisco Bay Area. At the same time, the Group staged high-profile activations, including a Madrid café pop-up that generated over 2 million impressions and brand events at Seoul’s Yesful Land that accumulated over 3 million impressions. Together, these physical and digital touchpoints successfully converted customer engagement into sustained loyalty.

This heightened brand exposure across end-consumer markets directly catalyzed overseas B2B purchasing demand. During the Reporting Period, ABW consolidated its newly built partnerships with retailers in the US and Latin America. Notably, ABW Online’s average order size surged 38.6% year-on-year to US$3,590.60. This uptick reflects substantially stronger purchasing appetite and inventory confidence for K-Beauty products among retailers, underscoring the powerful synergy of the Group’s B2C-B2B dual-engine model.

Mr. Joshua Lau, Founder, Executive Director and Chief Executive Officer of YesAsia Holdings, said: “K-Beauty remains on an upward trajectory as it becomes a mainstream player in the global beauty business. Looking ahead, we believe that there is ample room for growth for YesAsia Holdings in both the retail and wholesale spheres worldwide. Amid geopolitical and supply chain uncertainties, we are continuously reinforcing our competitive moat and market leadership through AI-empowered customer services, a highly agile supply chain, and a strategy that seamlessly converts online traffic into immersive physical experiences, thereby driving long-term value for our shareholders in a fast-evolving market landscape.”

Hashtag: #YesAsia

The issuer is solely responsible for the content of this announcement.

About YesAsia Holdings Limited (02209.HK)

Established in 1997, YesAsia Holdings is a leading e‑commerce platform operator recognized for its expertise in identifying and procuring quality Asian beauty products. Headquartered in Hong Kong, the Group delivers products promptly and efficiently to a global audience through its strong ties with over 400 leading Asian beauty brand and supplier partners. The Group operates two major channels: YesStyle, a B2C e‑commerce platform serving the growing demand for Asian beauty, fashion and lifestyle products, particularly Korean beauty products; and AsianBeautyWholesale, a B2B‑oriented business for Asian beauty products via online and offline channels. YesAsia Holdings is a constituent of the MSCI Hong Kong Micro Cap Index.

For more information, please visit the Group’s official website:

Advertisements
  • IFPHK x YF Life: Hong Kong–Macau Retirement Expense Indexrises to 131.6 — Monthly Spending Reaches HK$15,090
  • Retiree Living Costs Have Risen Nearly 3 Times Faster Than General Inflation Since 2020

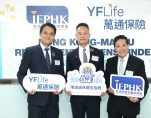
HONG KONG SAR – Media OutReach Newswire – 27 August 2026 – The Institute of Financial Planners of Hong Kong (IFPHK), in collaboration with YF Life Trustees Ltd. (YF Life Trustees), today launched the “IFPHK x YF Life: Hong Kong–Macau Retirement Expense Index” (Index). While the Index has been tracking retiree living expenses since its inception in 2020, this year marks the first time IFPHK and YF Life Trustees have partnered to expand the study to cover both Hong Kong and Macau, providing a broader regional benchmark.

Retirement Costs Soar Faster Than Inflation, Monthly Spend Hits HK$15,090: Over 72% of HK Retirees Wish They'd Acted Sooner

The findings show that retiree inflation in Hong Kong has continued to outpace general inflation. The Index rose to 131.6 in 2026, up from 127.0 in 2023 and 100 in 2020, while average monthly spending increased to about HK$15,090 in 2026. On an annualised basis, the Hong Kong Retirement Expense Index grew by more than 5% per annumfrom November 2020 to May 2026, compared with about 1.8% per annum for Hong Kong’s Composite CPI over the same period, showing that retiree living costs have effectively appreciated close to three times faster than Hong Kong’s general Composite CPI over the same period, underscoring how retirement-specific inflation — driven by travel and dining — is materially outpacing headline price trends.

Furthermore, the study reveals that more than 72% of retirees carry at least one regret regarding their retirement preparation. Most commonly, respondents feel they should have started saving or investing earlier and learned about financial planning sooner, while many continue to express concerns about medical costs, inflation, longevity risk and the risk of outliving their savings.

Dr. Paris Yeung, Chief Executive Officer of IFPHK, stated: “The findings show that satisfaction alone does not mean retirees are fully prepared. More than 72% say they have regrets, and the most common regrets point clearly to the need to start saving, investing and planning earlier. At the same time, retiree inflation has been rising faster than headline inflation, which means future retirees need more robust and flexible plans to protect their purchasing power over time. Through this expanded collaboration with YF Life, we aim to provide deeper regional insights to help future retirees plan with greater confidence.”

He added: “Turning regret into action requires starting earlier, integrating healthcare protection into retirement planning, viewing MPF as a steady retirement paycheck, and engaging qualified financial planners to address estate planning gaps. More importantly, retirement planning should shift from a rigid, set-and-forget approach to a flexible plan that adapts to each retiree’s evolving needs—what we call moving from a ‘fixed plan’ to a ‘flexible, evolving strategy’. Our goal is to help future retirees achieve sustainable and wellplanned golden years.”

Mr. Alvin Tse, Chief Executive Officer of YF Life Trustees, stated: “As the exclusive Project Sponsor of this expanded regional study, YF Life is proud to collaborate with IFPHK on this critical benchmark for Hong Kong and Macau. The 2026 data clearly shows that while retirees desire active lifestyles, they are heavily squeezed by medical inflation and the fear of outliving their wealth. To bridge this gap, retirees must shift away from viewing retirement savings as a static lump sum. By maximizing the flexibility of the MPF through phased withdrawals and mixed-asset strategies, alongside pairing them with lifetime annuity-style income streams and robust medical protection, individuals can effectively convert accumulated assets into a predictable, lifelong paycheck. True financial peace of mind comes from building an integrated fortress that safeguards against both market volatility and longevity risk.”

Key Highlights of the Study:

  • Retiree Inflation Has Outpaced General Inflation: The Index rose from 100 in 2020 to 131.6 in 2026, with average monthly retiree expenses increasing to about HK$15,090 and the Index growing at more than 5% per annum versus about 1.8% for Hong Kong’s Composite CPI for the same period. This escalation is driven partly by travelling and cross‑boundary transport—with roughly four out of five retirees visiting GBA Mainland cities and spending about RMB 1,100 per trip. This suggests that general inflation figures may understate retirees’ actual cash‑flow needs, highlighting the importance of planning for inflation‑protected retirement income and periodically rebasing budgets using a retiree‑specific living expense index rather than general CPI so they can maintain their intended post‑retirement lifestyle.
  • Retirees’ Satisfaction Masks Ongoing Financial Anxiety and Planning Gaps: Although many retirees report being satisfied with their current retirement life, concerns remain widespread, with 51% worrying about unexpected medical expenses, 41% about inflation and 77% still lacking any form of estate or asset planning. This suggests that retirees should turn present satisfaction into future resilience by building healthcare and contingency reserves, setting clear drawdown rules to manage longevity risk, and putting in place basic estate and incapacity documents such as wills, enduring powers of attorney and advance directives well before potential health or family crises arise.
  • Conservative Spending but Widespread Regret—Especially Among Asset‑Rich Retirees
    Actual retirement spending remains conservative, with average retirement expenses in 2026 equal to about 49% of pre‑retirement income. Yet more than 72% of retirees say they would have done something differently in preparing for retirement, most notably saving or investing earlier, learning financial planning earlier and communicating more openly with family about money and care needs. This pattern emphasizes that future retirees should start disciplined saving, investing and family financial discussions much earlier, even when their asset position appears comfortable.
  • MPF Transitioning Toward Income Support: While most eligible retirees still treat MPF as a lump sum, with about 76% having fully withdrawn their benefits in 2026, the scheme is gradually shifting toward an income‑support role, as 22% now use MPF to fund monthly expenses, up from 12% in 2023. Retirees are encouraged to treat MPF as part of a structured retirement income strategy, considering phased withdrawals, annuity‑style income solutions, and planned drawdowns rather than a single cash‑out, converting accumulated MPF assets into a more predictable and sustainable retirement paycheck.

Hashtag: #IFPHK #YFLife #RetirementPlanning

The issuer is solely responsible for the content of this announcement.

About “IFPHK x YF Life: Hong Kong–Macau Retirement Expense Index”

The “IFPHK x YF Life: Hong Kong–Macau Retirement Expense Index” was jointly launched in 2026 by the Institute of Financial Planners of Hong Kong (IFPHK) and YF Life Insurance International Limited. Since 2020, the Index has been the only long-term, retirement-specific benchmark tracking retirees’ actual living expenses. As the first study of its kind by IFPHK, the Index tracks and measures long-term changes in retirees’ actual living expenses with reference to the Composite Consumer Price Index (CPI) and the expenditure weightings published by the Government.

In the Hong Kong survey conducted in June 2026, NielsenIQ (NIQ) interviewed 304 retirees aged 55 to 74 with monthly personal income of at least HK$20,000 before retirement and not receiving means-tested social security or charitable support.

About IFPHK

IFPHK was established in June 2000 as a non-profit organization for the fast–growing financial industry. The Institute is the sole licensing body in Hong Kong authorized by Financial Planning Standards Board Limited to grant the much-coveted and internationally recognized CFP® certification and AFP® certification to qualified financial planning professionals in Hong Kong and Macau. Currently there are more than 236,000 CFP certificants in 29 regions; the majority of these professionals are in the U.S., China, Japan, Canada and Brazil. As at 28 February 2026, Hong Kong had approximately 3,238 CFP certificants.

At present, IFPHK has 5,298 members in Hong Kong including 956 Qualified Retirement Adviser (QRA) holders; and represents financial planning practitioners in diverse professional backgrounds such as banking, insurance, independent financial advisory, stock broking, accounting, and legal services.

About YF Life Trustees Ltd. & YF Life

YF Life Trustees is a member of YF Life Insurance International Limited (YF Life), and was among the first group of institutions approved as a Mandatory Provident Fund (MPF) scheme trustee. The company specializes in providing MPF services and is committed to creating long-term value for its scheme members.

The major indirect shareholders* of YF Life Insurance International Limited (“YF Life”) include Massachusetts Mutual Life Insurance Company (“MassMutual”), which itself has over 170 years of experience and is one of the Five Largest US Life Insurance Companies**, as well as Yunfeng Financial Holdings Limited, among others. YF Life is a long-term strategic partner of Barings. We stay at the forefront of Hong Kong’s insurance industry with our superior global investment capabilities, extensive partnership network, and fintech innovation.

* MassMutual and Yunfeng Financial Holdings Limited have indirect shareholdings in YF Life.
** The “Five Largest US Life Insurance Companies” are ranked according to the results of “Insurance: Life, Health (Mutual)” and “Insurance: Life, Health (Stock)”on total revenues for 2025, and based on the FORTUNE 500 as published on June 3, 2026.

HONG KONG SAR – Media OutReach Newswire – 27 August 2026 – In an era when enterprise software valuations are being fundamentally repriced by the rise of agentic AI, Deepexi Technology Co., Ltd. (1384.HK) has emerged as a rare counterexample: a pure-play enterprise AI platform that is delivering both technology leadership and bottom-line profitability. According to the company’s first interim results following its public listing, Deepexi recorded a 115% year-over-year surge in revenue for the first half of the year, powered by a 209% leap in core AI revenue and a decisive turnaround to quarterly GAAP profitability in the second quarter of 2026. This performance has earned the company “Buy” and “Overweight” ratings from multiple brokerages within its first year of listing.

Quarterly Profitability: A Rare Milestone in Hong Kong’s AI Sector

In capital markets, ambitious visions must ultimately be backed by real financial performance—and Deepexi’s interim results provide clear proof of execution.

For the first half of 2026, the company generated RMB 284.0 million in total revenue, marking a 115.0% year-over-year increase. Its AI business served as the primary growth engine, contributing RMB 226.0 million—an impressive 209.2% year-over-year surge—bringing AI revenue to 79.6% of total corporate turnover.

Even more noteworthy is the marked improvement in profitability. First-half gross profit reached RMB 160.0 million, up 120.5% year-over-year, with gross profit margin expanding to 56.5%. Crucially, during the second quarter of 2026, Deepexi posted a standalone quarterly net profit of approximately RMB 30.1 million, officially crossing the breakeven threshold.

In Hong Kong’s technology sector, pure-play enterprise AI companies capable of achieving quarterly net profitability while sustaining high R&D investment remain exceptionally rare. This milestone underscores Deepexi’s operational efficiency, scalable software delivery, and self-sustaining monetization engine.

This scarcity value is equally evident in the company’s revenue composition and vertical reach. Industrial manufacturing accounted for more than 50% of total revenue, while retail and consumer goods contributed 30%, alongside expanding footholds in healthcare and smart transportation. In manufacturing, for example, equipment troubleshooting and predictive maintenance involve dense engineering schematics, real-time IoT sensor telemetry, and extensive historical maintenance logs—all of which Deepexi translates into structured logic that AI models can readily interpret. This deep vertical expertise and proprietary data accumulation create a formidable competitive barrier that general-purpose AI vendors cannot easily match.

Beyond the “SaaSpocalypse”: Deepexi’s AI-Native Platform Defies the Software Valuation Reset

The first quarter of 2026 witnessed what market observers have dubbed the “SaaSpocalypse”—a tectonic shift in which approximately $2 trillion in market capitalization was erased from B2B software equities, driven by a fundamental fear that agentic AI would cannibalize the traditional per-seat licensing model. The iShares Expanded Tech-Software ETF (IGV) plunged nearly 21% year-to-date, and enterprise software multiples (EV/Sales) cratered from a 5.6x average at the end of 2025 to 4.2x by mid-March.

Investors have pivoted decisively toward AI-native infrastructure—companies that manage the data and underlying plumbing of autonomous systems—while penalizing traditional application-layer SaaS vendors reliant on human-centric interfaces. As a recent Windsor Drake analysis notes, “AI-native agentic platforms clear 14x to 22x revenue, with private rounds at 20x to 30x,” while legacy standalone RPA trades at just 2.5x to 5x. The market is now rewarding AI-native architecture and measurable workflow ownership.

Deepexi sits squarely on the winning side of this divergence. Unlike traditional SaaS vendors whose revenues are tied to human seat counts—and thus vulnerable to agentic displacement—Deepexi’s token-based, consumption-driven model aligns directly with the agentic AI future. The company’s DeepWorks enterprise Agent platform does not sell per-seat licenses; it sells AI productivity, enabling enterprises to deploy autonomous agents that replace repetitive administrative work, not software seats. As the market shifts from “AI as a feature” to “AI as a replacement,” Deepexi’s business model is structurally insulated from the seat-compression forces that have punished legacy software vendors.

Focus on Enterprise AI Applications and Proprietary Domain Data

To ensure AI truly meets real-world enterprise demands, generic foundational models are insufficient on their own. Deepexi’s core competitive edge lies in its specialized “Data + AI” dual-engine architecture, anchored by the FastData enterprise data intelligence platform, the FastAGI agentic AI suite, and the Deepexi Enterprise Large Model Platform, supported by its proprietary Deepology ontology dataset containing over 2,000 vertical industry skills.

At the foundational layer, the FastData platform—powered by the FastData Foil fusion engine—acts as an intelligent lakehouse that tokenizes structured, semi-structured, and complex unstructured enterprise data into standardized formats ready for large model training and inference. Building upon this data foundation, the FastAGI platform and DeepWorks Enterprise Agent Platform provide organizations with a flexible, modular AI operating system.

Featuring a pluggable architecture, the platform connects seamlessly to leading open-source foundation models such as DeepSeek and Zhipu AI, giving enterprise clients complete autonomy while eliminating vendor lock-in. This “model-agnostic” approach is a key differentiator in an environment where enterprises increasingly demand flexibility to choose the best model for each use case, rather than being locked into a single provider.

Through native Model Context Protocol (MCP) frameworks and specialized agents—ranging from operational decision-making agents to productivity and autonomous workflow execution agents—Deepexi embeds intelligence directly into core business operations. DeepWorks is fully integrated with mainstream workplace collaboration suites such as DingTalk, Feishu, and Tencent Meeting, allowing employees to summon AI copilots directly for automated weekly reporting, data synthesis, and cross-departmental coordination—effectively turning AI into an indispensable daily productivity tool.

In an enterprise AI market where 42% of organizations already have AI agents in production and 72% are deploying across production and pilots combined, Deepexi’s proven, governed agentic workflows are no longer an experiment—they are core infrastructure.

Strategic Partnership with Huawei Cloud: Tackling Compute and Data Bottlenecks

In the commercialization of enterprise AI, computing costs and access to high-quality domain data represent two of the industry’s most critical bottlenecks. On August 12, Deepexi announced a strategic alliance with Huawei Cloud to jointly launch enterprise data intelligence solutions, providing strong operational backing for the company’s long-term expansion.

The partnership combines the complementary strengths of both technology leaders. Huawei Cloud provides underlying Ascend AI computing clusters and distributed cloud infrastructure, while Deepexi brings its deep expertise in enterprise data governance, data tokenization, and vertical AI agent deployments. By integrating with Huawei’s domestic Ascend compute clusters, Deepexi not only secures stable, long-term computing power but also significantly drives down token processing costs. This cost efficiency establishes ideal conditions for exploring usage-based, token-metered commercial billing models—precisely the kind of consumption-based pricing that aligns with the agentic AI future.

Crucially, falling AI costs are widely expected to accelerate enterprise adoption of autonomous agents. Deepexi’s partnership with Huawei Cloud positions the company to capture this demand wave with a cost structure that improves as token volumes scale—a powerful margin-expansion dynamic that stands in stark contrast to the fixed-cost burden of traditional SaaS.

Strong Institutional Backing Highlights Long-Term Investment Value

Reflecting strong capital market confidence, Deepexi announced on August 17 the successful placement of 14,286,000 new H-shares at HK$35.00 per share, raising net proceeds of approximately HK$488.0 million. Successfully closing a sizeable placement amid broader market volatility demonstrates strong institutional recognition of Deepexi’s proven business model, robust unit economics, and profitability trajectory.

The company’s strategic shareholder structure provides a solid foundation for long-term growth. It is supported by prominent independent investors, including Hillhouse, 5Y Capital, and BAI, as well as industry-focused investors such as Shanghai AI. These partnerships enhance Deepexi’s industry reputation, drive technological innovation, and strengthen its market competitiveness.

The newly raised funds are earmarked primarily for continuous R&D in next-generation enterprise agent systems and token productivity platforms—positioning the company to capture the $206.5 billion AI agent software market projected for 2026, which Gartner expects to grow to $376.3 billion in 2027.

Investment Thesis: Why Deepexi Stands Apart

1. AI-Native Architecture in an Agentic World. Unlike legacy SaaS vendors facing seat compression, Deepexi’s token-based model is structurally aligned with the agentic AI future. The company doesn’t sell software seats—it sells AI productivity.

2. Rare Profitability in Enterprise AI. Quarterly GAAP profitability at a 56.5% gross margin, with projected revenue CAGR of 95.5% through 2027, places Deepexi among the most financially disciplined enterprise AI companies globally.

3. Model-Agnostic, Vendor-Neutral Platform. In an environment where enterprises demand flexibility, Deepexi’s pluggable architecture—supporting DeepSeek, Zhipu, and other open-source models—eliminates lock-in and captures value regardless of which foundation model wins.

4. Proprietary Data Moat. With over 2,000 vertical industry skills and deep expertise in manufacturing, retail, healthcare, and transportation, Deepexi’s domain-specific data capabilities create barriers that general-purpose AI vendors cannot replicate.

5. Strategic Compute Partnership with Huawei Cloud. Long-term, cost-effective compute access, combined with token-metered pricing models, positions Deepexi for sustained margin expansion as token volumes scale.

6. Institutional Validation. Backing from top-tier investors and a successful HK$488 million placement amid market volatility signal strong institutional confidence in Deepexi’s business model and growth trajectory.

The enterprise AI market has decisively shifted from early conceptual exploration into a new era of commercial execution and tangible financial delivery. Backed by mature product suites across FastData and FastAGI, proprietary vertical ontologies, strategic cloud partnerships, and an official transition to net profitability, Deepexi Technology has proven that enterprise AI can deliver both transformative technology and sustainable profits.

Hashtag: #DeepexiTechnology

The issuer is solely responsible for the content of this announcement.

About Deepexi Technology

Deepexi Technology is China’s leading provider of enterprise large model AI application solutions. Through its FastData enterprise data intelligence solution and FastAGI enterprise AI solution, it empowers enterprises to integrate their data, decisions and operations efficiently at scale. Deepexi ranked fifth in China’s enterprise large model AI application solution market in terms of revenue in 2024. Its solutions have achieved large-scale commercialization across multiple verticals, including consumer goods, manufacturing, healthcare and transportation. As of June 30, 2025, Deepexi Technology served a cumulative total of 283 enterprise customers across various industries.

This press release contains forward-looking statements that involve risks and uncertainties. Actual results may differ materially from those projected. The company undertakes no obligation to update any forward-looking statements.


HONG KONG SAR – Media OutReach Newswire – 26 August 2026 – SenseTime Group Inc. (“SenseTime” or the “Company”; Stock Code: 0020.HK) today announced its results for the first half of 2026. During the Reporting Period, the Group recorded total revenue of RMB2.91 billion, representing a year‑on‑year (“YoY”) increase of 23.4%, and gross profit of RMB1.21 billion, up 32.9% YoY. Gross profit margin reached 41.4%, an increase of 2.9 percentage points YoY. The Group also introduced recurring revenue (“RR”) for the first time, which totaled RMB1.14 billion and accounted for 39.3% of total revenue. The Group recorded a net profit of RMB620 million under International Financial Reporting Standards (“IFRS”), marking its first IFRS profit since its public listing. Generative AI revenue reached RMB2.33 billion, representing nearly 80% of the Group’s total revenue, while overseas business revenue increased 127% YoY, significantly outpacing the Group’s overall growth rate. While delivering healthy growth in revenue and gross profit, the Group continued to improve operating efficiency, with core operating losses narrowing significantly. Non‑IFRS adjusted net loss was RMB390 million, narrowing by 67.3% YoY.

The Group continued to accelerate the large‑scale commercial deployment of its AI capabilities, building system‑level AI capabilities around the framework of “one model system, one Token Factory, and one Agent Harness” to advance AI from intelligence generation toward end‑to‑end task execution and transform these capabilities into scalable commercial value.

Dr. Xu Li, Chairman of the Board and CEO of SenseTime, said: “SenseTime’s three-pillar core capability framework, built around ‘one model system, one Token Factory, and one Agent Harness’, uses a unified model system to continuously push the boundaries of intelligence, leverages infrastructure and optimization capabilities to reduce Token costs and strengthen cost‑based pricing power, and deploys agents deeply integrated into enterprise and individual workflows to deliver complete task execution capabilities. This framework enables SenseTime to move beyond pure price competition and create sustainable commercial value through differentiated technologies and services. At the same time, it allows us to expand our user base, drive recurring revenue growth, and lay a solid foundation for the Group’s high‑quality development.”

One Model System: Advancing Native Multimodal Intelligence and Long‑Horizon Agents with Global Leading Performance

In 2026, SenseTime released a series of models at a rapid pace, spanning native multimodal unification, visual perception and reasoning, controllable generation, long‑horizon agents, spatial intelligence, and physical world models. These included the NEO‑Unify architecture; SenseNova U1, U1.5 and U1.5‑Lite; SenseNova Vision; the office‑focused multimodal agent SenseNova 6.8‑Flash‑Lite; the content creation model SenseNova U1‑Pro; the spatial intelligence model SenseNova SI‑8B; and the Kairos 3.1 world model co‑developed with Ace Robotics. Across multiple core benchmarks, these models matched or outperformed leading international models, including Gemini, GPT, and DeepSeek. Less than four months after the U1 series was open‑sourced, the three projects had collectively garnered more than 11,000 stars on GitHub.

SenseTime is advancing from digital intelligence toward physical AGI through the closed‑loop framework of “architectural innovation, system capabilities, and high‑value delivery,” continuously translating technological breakthroughs into real-world applications and commercial value.

Token Factory: Upgrading from Compute Provisioning to Scaled Intelligence Production

SenseTime’s SenseCore is evolving into a production‑oriented Token Factory. Through integrated model and infrastructure optimization, as well as capabilities in model adaptation, inference optimization, heterogeneous scheduling, energy management and global service delivery, the Token Factory not only expands Token output and lowers unit costs, but also continuously enhances the reasoning, understanding, generation, and execution capabilities embedded in each Token.

In July 2026, SenseCore delivered an average daily Token service volume of 2.4 trillion, representing a YoY increase of approximately 22 times. As of the date of this announcement, the Group’s total deployed computing power had reached 48,000 Petaflops (P).

The Token Factory provides strong support for SenseTime in advancing the performance boundaries of its foundation models and scaling their commercial deployment. It has tripled the training speed for long‑context Agent models, increased image and video generation efficiency sixfold, improved reinforcement learning training efficiency, and shortened the cycle from model R&D validation to large‑scale deployment to just one week. In addition to supporting the SenseNova foundation model, the Token Factory now serves four external foundation model providers, establishing differentiated capabilities across high‑complexity computing domains, including AI for Science (“AI4S”), video generation, embodied intelligence, world models, and city‑level intelligent applications.

In addition, the Group remains committed to advancing the domestic compute ecosystem, increasing the MFU (Model Floating‑Point Utilization) of mainstream domestic chips by up to 2.5 times compared with the baseline levels established by chip manufacturers. SenseNova U1 has achieved Day 0 adaptation across more than ten domestic chip platforms.

Through compute‑energy synergy, the Company continues to reduce the unit cost of intelligence. During the Reporting Period, its Compute‑Energy Synergy Agent achieved load forecasting accuracy of 96% and generated cumulative electricity cost savings of more than RMB12 million. For every 10,000P of computing power, annual carbon emissions were reduced by 24,000 tons.

Agents Accelerate Adoption Across Enterprise and Consumer Markets, Delivering Value Through Workflow Integration and Enhanced Everyday Experiences

Building on its model and Token capabilities, SenseTime connects models, knowledge, tools, and workflows through a unified Agent Harness, transforming underlying AI capabilities into end-to-end task delivery solutions for enterprise and individual users.

The Group’s agents are rapidly expanding across both enterprise and personal workflows. During the Reporting Period, they served more than 1,000 enterprise customers across over 20 key industries, including education, government, marketing, logistics, banking, and insurance. The Office Agent, Raccoon, has served major enterprises including Lenovo, Ping An Technology, China’s three major telecommunications operators, JD.com, and Kylin Software. Total users increased more than fivefold YoY, enterprise users grew more than sixfold, and monthly active users on the cloud platform increased nearly tenfold. In addition, the video‑generation agent Seko reached a daily video production volume of 10,000 minutes. Content created on the platform has amassed an estimated 1.5+ billion views across short‑video platforms, including 10 short-form dramas that have each surpassed 100 million views. AI productivity solutions are also expanding beyond large organizations to serve smaller teams and One‑Person Companies (OPCs). In the consumer market, the Kapi series of agents, covering use cases such as health, finance, and content creation, has surpassed 45 million cumulative users.

Computer Vision remains a strategic gateway for the Group’s expansion into industry verticals and overseas markets. During the Reporting Period, revenue from the business reached RMB500 million, accounting for approximately 17% of the Group’s total revenue. The business extended across more than 20 countries and regions and served more than 4,500 customers worldwide, with recurring customers contributing 67% of revenue.

Bridging Digital and Physical Intelligence, Unlocking Ecosystem Value

SenseTime continued to invest in frontier areas, including world models and embodied intelligence, intelligent terminals, smart healthcare, and chips. The increase in the valuation of certain AI ecosystem investments generated fair‑value gains, contributing to the Group’s first‑ever IFRS profit and reflecting the gradual realization of financial value from our ecosystem assets. Beyond short‑term investment returns, the more significant long‑term value of these ecosystem investments lies in enabling the Group gain early access to frontier domains, continuously acquire real‑world tasks, data, and feedback, and further strengthen SenseTime’s unified multimodal models and system‑level delivery capabilities.

SenseTime is deepening its “Three-pillar Framework”: one model system to raise the ceiling of intelligence and expand agents’ ability to handle complex tasks; one Token Factory to improve quality and efficiency, reduce costs, and enhance global delivery capabilities; and one Agent Harness to integrate multimodal models with the Token Factory, enabling AI to complete end‑to‑end tasks in real-world scenarios.

Looking ahead, SenseTime will continue to advance the iteration of multimodal agents, driving the evolution of the Token Factory from pricing based on Token volume to pricing based on task outcomes. The Group will also deepen the application of multi‑agent collaboration across enterprise, individual, and OPC workflows, delivering efficient and reliable productivity solutions to users.

Hashtag: #SenseTime

The issuer is solely responsible for the content of this announcement.

About SenseTime

Founded in 2014, SenseTime is a leading artificial intelligence (AI) software company, committed to its mission of “creating a better AI-empowered future through original innovation”. The Company continues to lead cutting-edge AI research while accelerating the large-scale commercialization of AI technologies.

Leveraging deep academic expertise and strong in-house innovation capabilities, SenseTime continues to enhance its industry-leading multimodal, multi-task general AI capabilities, while fostering a vibrant developer ecosystem through structured open-source initiatives.

SenseTime’s business spans Generative AI, Vision AI, and emerging innovation-driven segments. Underpinned by SenseCore, its next-generation AI infrastructure, the Company integrates computing power, algorithms, and platforms to enable scalable AI deployment. Building on this foundation, SenseTime has developed the SenseNova foundation model series, delivering cost-efficient capabilities across a wide range of general AI tasks. SenseTime continues to lead the global Vision AI market, ranking No.1 worldwide by market share. Its SenseFoundry platform integrates years of accumulated computer vision expertise with advanced multimodal foundation models, providing stable and efficient Vision AI solutions to industries worldwide.

SenseTime is listed on The Stock Exchange of Hong Kong, with operations spanning more than a dozen countries and regions.

By Subrata Majumder In the post Japanese Yen appreciation era, Japanese overseas investment shifted to China and ASEAN for low-cost manufacturing, leaving India behind. The trajectory is now witnessing movement in the reverse gear, owing to US President Trump’s high reciprocal tariff. Japanese investment has surged in India, leaving China and ASEAN behind. While Japanese […]

The article Trump’s high-tariff regime revives Japanese investment in India appeared first on Latest India news, analysis and reports on Newspack by India Press Agency).

Alibaba Group Holding’s powerful insiders have stepped in to buy shares after its $10.2 billion equity placement, but their show of confidence has done little to settle investor unease over dilution and the rising cost of the company’s artificial intelligence ambitions.

Founder Jack Ma bought more than HK$600 million worth of Alibaba’s Hong Kong-listed shares over consecutive trading days, while chairman Joe Tsai and chief executive Eddie Wu together purchased more than HK$200 million of stock. The buying helped shares recover modestly after the placement triggered their sharpest setback in months, but the stock remained well below levels preceding the deal.

Alibaba priced 710 million new shares at HK$112.70 each, raising HK$80 billion, or about $10.2 billion. The price represented an 8.4% discount to the August 21 Hong Kong close of HK$123 and increased the company’s outstanding share count by roughly 3.7%.

Hong Kong-listed shares slumped 8.5% on August 24, closing at HK$112.50 after trading as low as HK$110.10. They recovered 1.5% to HK$114.20 on Tuesday as purchases by senior executives became known, leaving them still more than 7% below the price immediately before the placement was announced.

The transaction has become a test of whether investors will continue financing increasingly expensive AI expansion despite the near-term pressure it places on earnings and cash generation. Alibaba has earmarked all net proceeds for its full-stack AI capabilities, covering computing infrastructure, chips, models and other technologies required to expand its cloud and generative AI businesses.

Demand for the offering itself was strong. Investor orders reached roughly $28 billion, making the placement almost three times subscribed. Sovereign wealth funds and long-only institutional investors accounted for a sizeable portion of allocations. The deal ranks as the largest primary follow-on share offering by a Hong Kong-listed company.

The discomfort instead centres on the scale and timing of Alibaba’s capital requirements. The company spent close to $10 billion on capital expenditure during the three months through June, an increase of about 75% from a year earlier. Net profit dropped about 75%, while free cash flow turned into an outflow of roughly $6.6 billion.

Alibaba has already deployed almost half of the 380 billion yuan it pledged last year to spend on AI and cloud infrastructure over three years. Management has argued that rapidly growing demand justifies accelerating investment and has shortened its expected payback period for AI expenditure to about two-and-a-half years from three years.

That argument is supported by Alibaba Cloud’s accelerating expansion. Revenue from the cloud business has been growing strongly, helped by demand for AI-related products, while the company continues to build computing capacity overseas. Alibaba Cloud this month opened a third data centre in South Korea, taking its network to 104 availability zones across 30 regions.

Its Qwen family of large language models has also strengthened Alibaba’s position among leading Chinese AI developers. New iterations have improved performance in coding, reasoning and agent-based tasks, helping the company compete with models from domestic rivals and leading US technology groups.

Investors nevertheless face a difficult balance between the longer-term AI opportunity and the immediate financial cost. Expensive processors, servers, data centres and networking equipment require large upfront commitments, while competition is pushing model providers towards lower prices. Alibaba is simultaneously spending heavily on quick commerce and other consumer businesses, adding pressure to margins.

The share sale has also revived scrutiny of capital allocation. Alibaba spent years repurchasing billions of dollars of its own shares, only to issue new equity at a sizeable discount as AI spending accelerated. Although the company still has substantial cash resources, investors have questioned why such a large equity raising was preferable to greater use of its balance sheet or debt financing.

Arabian Post Staff -Dubai Abu Dhabi Islamic Bank’s board has approved plans to raise up to Dh1.75 billion through a rights issue, strengthening its capital base as the lender pursues faster expansion under its Vision 2035 strategy. The proposed transaction will involve the issuance of as many as 106.38 million new ordinary shares at Dh16.45 each. The subscription price represents a discount of about 28.8 per cent […]

SINGAPORE – Media OutReach Newswire – 26 August 2026 – JOYY Inc. (NASDAQ: JOYY) (“JOYY” or the “Company”), a leading global technology company, today released its unaudited financial results for the second quarter ended June 30, 2026.

For the second quarter, JOYY reported total revenues of US$590.8 million, representing an increase of 16.3% year over year and 6.3% quarter over quarter. Social Entertainment revenue expanded 7.4% year over year and 5.6% quarter over quarter to US$422.7 million. BIGO Ads and SHOPLINE, the second growth engine of the Company, continued to deliver strong performance. BIGO Ads revenue generated US$133.7 million, up 53.1% year over year, while SHOPLINE contributed US$34.4 million, marking an accelerated year-over-year growth rate of 28.6%.

The Company continued to strengthen its profitability in the second quarter, with non-GAAP¹ operating income reaching US$49.1 million, up 28.2% year over year and 29.4% quarter over quarter. Non-GAAP¹ EBITDA reached US$56.9 million, up 18.1% year over year and 24.4% quarter over quarter. Operating cash inflow totaled US$64.9 million during the quarter, while net cash stood at US$3.06 billion as of June 30, 2026.

JOYY continued to deliver on its shareholder return commitment in 2026. Following the update of its three-year shareholder return program in May, the Company plans to return a cumulative US$1.5 billion to shareholders by the end of 2028. From January 1 to August 21, 2026, the Company returned US$358.8 million to shareholders, comprising US$216.4 million in share repurchases and US$142.4 million in dividends.

1. This press release includes certain non-GAAP financial measures as additional clarifying items to aid investors in further understanding the Company’s performance and the impact that these items and events had on the financial results. The non-GAAP financial measures provided above should not be considered as a substitute for, or superior to, the measures of financial performance prepared in accordance with GAAP. For details of the non-GAAP measures, including the reconciliations of GAAP measures to non-GAAP measures, please refer to the press release titled “JOYY Reports Second Quarter 2026 Unaudited Financial Results” issued by the Company on August 26, 2026.

Hashtag: #JOYY #FinancialReport

The issuer is solely responsible for the content of this announcement.

Bitcoin climbed back above $79,000 on Monday, extending a powerful rebound that has restored bullish momentum after weeks of pressure across cryptocurrency markets. The world’s largest digital asset briefly traded around $79,200 before encountering resistance near the psychologically important $80,000 level. The move capped a sharp recovery from levels near $63,400 earlier in the week, representing a gain of more than 20% from the trough. Bitcoin subsequently […]

Standard Chartered has become the first bank to distribute a regulated Hong Kong dollar stablecoin, opening access to Anchorpoint Financial’s HKDAP for eligible institutional clients and partners as Hong Kong pushes tokenised money deeper into mainstream financial services.

The London-headquartered banking group said it will help qualifying customers integrate HKDAP into financial and commercial operations. Planned applications include money-market fund subscriptions, settlements with asset managers, transfers between entities within the bank’s international network and cross-border payments.

The move gives HKDAP a major banking distribution channel less than two weeks after Anchorpoint began its limited institutional rollout on August 12. The stablecoin, whose name stands for HKD At Par, is designed to maintain a one-to-one value with the Hong Kong dollar and is currently available through a controlled beta programme.

Standard Chartered is the majority shareholder in Anchorpoint, which was established with HKT and Animoca Brands. The venture received one of Hong Kong’s first stablecoin issuer licences in April, alongside HSBC, following the introduction of the territory’s Stablecoins Ordinance in August 2025.

Standard Chartered’s role as distributor is distinct from Anchorpoint’s function as issuer. Under Anchorpoint’s business-to-business-to-consumer model, authorised distributors provide access to the token after conducting customer onboarding and know-your-customer checks. That structure is intended to connect regulated tokenised money with banks, exchanges, asset managers, companies and, eventually, individual users.

Access remains restricted during the beta stage to corporates and professional investors. Anchorpoint aims to broaden availability to retail users as early as the end of 2026, subject to operational and market readiness.

HKDAP currently operates on the Ethereum mainnet. Its reserves are held under a trust arrangement for token holders, with Standard Chartered Trustee acting as trustee. The token does not pay interest and is not positioned as an investment product. Instead, it is designed as digital cash for payments, settlement and movement of funds.

Early activity remains deliberately limited. Anchorpoint disclosed circulation of HK$522,000 and transaction volume of HK$658,160 as of August 19, with reserve assets of about HK$1.62 million. Issuance over the preceding 30 days totalled HK$524,130, while HK$4,170 had been redeemed. The small amounts reflect the controlled institutional testing phase rather than a mass-market launch.

The distribution agreement nevertheless represents an important step towards commercial use. Standard Chartered plans to introduce additional HKDAP applications over the coming month, expanding beyond experiments into transactions that could demonstrate whether regulated stablecoins can reduce settlement times and connect conventional banking infrastructure with blockchain-based markets.

The bank has been accelerating its digital-asset strategy across several areas. It already provides institutional trading in deliverable spot Bitcoin and Ether, has expanded digital-asset custody services and has developed blockchain-based settlement and collateral arrangements. In July, it also launched integrated institutional access to Circle’s USDC minting and redemption infrastructure.

Standard Chartered’s scale could give HKDAP a distribution advantage. The group operates across 55 markets and reported total assets of about $993.4 billion at the end of June 2026, up from roughly $920 billion at the end of 2025. First-half operating income reached a record $11.6 billion, while pre-tax profit rose to $4.8 billion.

Hong Kong’s regulated stablecoin experiment is taking shape cautiously. The monetary authority has imposed capital, reserve-management, redemption, governance, anti-money-laundering and risk-management requirements on licensed issuers, seeking to distinguish supervised fiat-backed tokens from the less regulated stablecoins that dominate global cryptocurrency trading.

HSBC, the other initial licensed issuer, is preparing its own Hong Kong dollar stablecoin for launch during the second half of 2026. The entrance of two globally significant banks places Hong Kong among the jurisdictions attempting to develop regulated alternatives to dollar-denominated tokens such as USDT and USDC, which account for the overwhelming majority of global stablecoin activity.

HKDAP’s first commercial targets centre on areas where settlement speed can offer measurable benefits. Tokenised investment products can potentially be subscribed to and redeemed using programmable money without waiting for traditional banking hours. Cross-border corporate transactions and intragroup treasury transfers could similarly move continuously while maintaining a direct link to regulated fiat reserves.

Bitcoin held close to $78,000 on Monday after its strongest weekly advance in more than three years, while gold climbed to a three-month high and major alternative cryptocurrencies paused after sharp gains. The largest cryptocurrency was trading around $77,000-$78,000 after gaining about 23% over the week ended August 23. Bitcoin briefly rose above $79,000 during the surge, its highest level in roughly three months, before profit-taking and […]

Bitcoin climbed above $75,000 on Friday, extending a sharp advance fuelled by improving liquidity conditions, heavy short-covering and renewed optimism over cryptocurrency regulation in the United States. The world’s largest cryptocurrency traded around $75,400 during early Asian hours after reclaiming the level for the first time since late May. Bitcoin gained about 8% over 24 hours and roughly 19% over the week, marking one of its strongest […]

Firmly Implementing the “Single Brand, Multi-categories, Diversified Channels” Strategy; Super BOOM Capsule Technology Achieves Full Commercialization; Deepens Global Professional Sports Resources Together with Curry

FINANCIAL HIGHLIGHTS

  • In the first half of the year, the Group recorded the following operating results:
    • Revenue rose by 2.8% to RMB15,235 million; gross profit margin increased by 0.9 percentage points to 50.9%
    • Net operating cash inflow was RMB954 million
    • Net profit attributable to equity holders was RMB1,816 million with net profit margin of 11.9%, and EBITDA margin was 22.1%
  • Working capital remained at a healthy level:
    • The percentage of gross average working capital to revenue was 7.8%
    • The cash conversion cycle was 35 days, an increase of 4 days compared with the same period last year
  • The Board resolved to declare an interim dividend of RMB35.12 cents per ordinary share of the Company issued or to be issued upon conversion of convertible securities for the six months ended 30 June 2026.

OPERATIONAL HIGHLIGHTS

  • The retail sell-through for the overall platform increased by low-single-digit from last year, including online and offline channels.
  • Offline channel new products sell-through accounted for 83% of overall offline channel sell-through, maintaining a healthy and reasonable level.
  • Channel inventory-to-sales ratio of 4 months; and inventory level and ageing structure remained at a healthy level.

HONG KONG SAR – Media OutReach Newswire – 20 August 2026 – Li Ning Company Limited (“Li Ning” or the “Company”, together with its subsidiaries, collectively the “Group”; Hong Kong Stock Exchange stock codes: 2331 (HKD counter) and 82331 (RMB counter)) today announced the unaudited interim results of the Group for the six months ended 30 June 2026 (the “Reporting Period”).

FINANCIAL RESULTS

In the first half of 2026, the Group continued to enhance product technology performance, optimise channel efficiency and deepen its professional brand mindset, maintaining steady operations. During the period, the Group’s revenue reached RMB15,235 million, up 2.8% year-on-year (2025: RMB14,817 million). Gross profit was RMB7,751 million, up 4.5% year-on-year (2025: RMB7,415 million), and the Group’s overall gross profit margin was 50.9%, up 0.9 percentage points year-on-year (2025: 50.0%).

During the period, profit attributable to equity holders of the Group was RMB1,816 million (2025: RMB1,737 million); the margin of profit attributable to equity holders was 11.9% (2025: 11.7%); and return on equity attributable to equity holders was 6.5% (2025: 6.5%). Basic earnings per share were RMB70.40 cents (2025: RMB67.43 cents). The Board resolved to declare an interim dividend of RMB35.12 cents per ordinary share of the Company issued or to be issued upon conversion of convertible securities for the six months ended 30 June 2026 (2025: RMB33.59 cents).

In terms of cash flow management, net cash generated from operating activities during the period amounted to RMB954 million (2025: RMB2,411 million). As at 30 June 2026, cash and cash equivalents (including cash at banks and in hand, and fixed term deposits with original maturity of not more than three months) amounted to RMB13,003 million, a decrease of RMB3,713 million compared with 31 December 2025. Adding back amounts recorded in bank time deposits, the cash balance was RMB19,389 million, a net decrease of RMB585 million compared with 31 December 2025. During the period, revenue increased year-on-year while cash expenses such as marketing expenses and taxes increased, resulting in a year-on-year decrease in net cash generated from operating activities; an increase in time deposits led to a significant increase in net cash used in investing activities. The Group will continue to prioritise cash flow management to ensure the stable development of the Company in the long term.

BUSINESS OVERVIEW

In the first half of 2026, the Group firmly implemented its core development strategy of “Single Brand, Multi-categories, Diversified Channels”. On one hand, it continuously strengthened the core of professional sports technology and product performance, consolidating the brand’s professional mindset in niche segments; on the other hand, it continuously deepened its highly efficient operating model, maintaining solid operating fundamentals and a healthy inventory level.

In terms of product upgrades, the Group drove iterative upgrades in the performance of its core category products through technological innovation, and coordinated the synergistic development of the core categories of running, basketball, training, badminton, table tennis and sports casual. The Group launched its “Super BOOM Capsule” technology, applied to racing running shoe series such as Feidian and Red Hare, covering the full-scenario needs of competitive training, elite and mass runners; the LI-NING Aerospace Dynamic Thermal Technology was applied to the award equipment of the Chinese Sports Delegation at the 2026 Milan Winter Olympics. The Group also expanded its outdoor product matrix and accelerated its layout in the outdoor market.

In terms of brand communication, the Group focused on building an all-round sports resource system represented by its cooperation with the Chinese Olympic Committee (the “COC”) and top international athlete IPs. During the period, the Group continued to strengthen its strategic partnership with the Chinese Olympic Committee, developing podium wear for the Chinese sports delegation competing at the 2026 Milan Winter Olympics, and establishing a presence at the “China House” in Milan, working alongside the Chinese Olympic Committee to showcase the strength of Chinese sports. In addition, the Group entered into a long-term strategic partnership with NBA superstar Stephen Curry and his brand “Curry Brand”, cooperating on the research and development of professional basketball equipment, the promotion of event culture, and the expansion of new-generation consumer groups, enhancing LI-NING’s professional sports brand perception and international exposure.

In terms of channels, the Group continued to deepen strategic synergy with leading commercial complexes and orderly carried out the planning and roll-out of innovative store formats. During the period, the standalone outdoor store “COUNTERFLOW” officially opened in Chongqing, laying the foundation for the Group’s outdoor category to deepen its presence in the Southwest regional market; the Group’s cooperation with quality commercial resources also entered a new stage, creating favourable conditions for the concentrated opening of multiple “Loong Stores” in the second half of the year. At the same time, the Group continued to optimise its rental structures and commercial cooperation models, enhancing the overall operating health of its channels.

In terms of retail operations, the Group promoted dual-driven growth in products and brand by establishing a high-tier market operating model and a distribution business operating model. In high-tier markets, the Group strengthened its brand image around three dimensions, namely channel structure optimisation, refinement of store product mix and upgrading the shopping experience, driving incremental capture of brand elevation and category depth. In terms of distribution business, the Group concurrently established a distribution management model to enhance distribution efficiency and the sustainable operating capability of the channel. In terms of terminal operating capability, the Group continued to drive the implementation of retail standards on a project basis, strengthened coordination efficiency between headquarters and terminals, and enhanced sports advisors’ customer reception capability and professional service standards, comprehensively improving consumers’ shopping experience in LI-NING stores and laying the foundation for enhanced single-store operating efficiency.

In terms of e-commerce operations, the Group leveraged key promotional opportunities including Tmall Celebration Day, Goddess Festival and 618 to precisely target new-customer acquisition and deeply reach female consumer groups, effectively driving simultaneous growth in sales scale and brand influence. The Group also converted cutting-edge technology into quality product experiences, coordinated Olympic champions and celebrity spokesperson resources, and worked with fashion magazines, trend events and social media platforms to continuously consolidate its professional sports mindset. Flagship products including basketball shoes Gamma 2, LI REN 6V2 and DLO 2, as well as the running shoe matrix of Wushi, Youzhi and Zhui Feng, all achieved notable results in expanding awareness and increasing sales, while the Feeling family remained ranked first in searches in the thin-soled shoe segment.

In terms of new retail business, the Group established a new retail department to focus on mapping out its omni-channel growth business model. Through the O2O model, it connected online and offline merchandise pools, providing consumers with a more consistent and efficient shopping experience. The Group also accelerated its layout on mainstream instant-retail platforms, making concerted efforts across three areas: channel store expansion, merchandise matching and refined single-store operations. On the one hand, it fully leveraged the Group’s multi-category advantages, expanding product coverage on the basis of core categories such as running shoes, basketball shoes and lifestyle apparel in combination with sports and lifestyle scenario needs; on the other hand, it strengthened the supply of seasonal categories such as outdoor and sun protection around consumption nodes such as holiday travel, driving stable growth in sales scale for the instant-retail channel.

In terms of product management, to respond to market competition, the Group increased its technology investment in high-end professional running shoes, leveraging the “Feidian” family driven by “Super BOOM Capsule” technology and the brand-new “Red Hare ULTRA” series to consolidate the brand’s product mindset and market position among professional runners. While the basketball shoe market faced challenges, the Group relied on core signature models combined with an e-commerce-channel-led promotion strategy to keep basketball shoe sales stable across directly-operated and e-commerce channels. The Group also actively applied flexible supply models such as segmented production and rolling replenishment orders, dynamically adjusting order scale according to actual sales and, in particular, carrying out refined control of the inventory structure for the running shoe category, maintaining healthy inventory levels amid a challenging market environment.

In terms of supply chain and logistics, the Group continued to advance the building of a large supply-chain system across five directions: planning management, quality control, cost management, development management and digital-intelligence transformation. The Group actively advanced the development of its Glory Gold Label series to safeguard the supply of top-tier event equipment, while also promoting the implementation of AI and 3DVR design and development processes for footwear, substantially shortening the R&D cycle. On the logistics front, the Group advanced omni-channel logistics integration, connecting online and offline inventory, and continued to drive warehouse automation and the application of RFID technology, improving the efficiency of goods flow and the precision of inventory management.

OUTLOOK

Looking ahead to the second half of 2026, the Group will continue to seize the development opportunities arising from the ongoing release of domestic demand potential, uphold its core value of ” Serve With Sportsmanship “, continuously refine the “LI-NING’s experience value”, and strive to become the preferred professional sports brand trusted by consumers in the sports consumption sector.

  1. Technology-driven product upgrades: The Group will continue to adhere to technological innovation as its core driving force, strengthening the core competitiveness of its products through the three major levers of its technology innovation platform, a full-scenario category matrix and Eastern aesthetics, while reinforcing its layout in high-potential tracks such as professional sports and urban outdoor.
  2. Top-tier resources empowering the brand: The Group will coordinate its domestic and overseas marketing resources. By leveraging core resource deployments such as its partnership with the Chinese Olympic Committee and collaborations with superstar IPs, the Group will build a multi-dimensional, long-term and high-conversion communication system. The Group will continue to deepen its long-term cooperation with the Chinese Olympic Committee, supporting the Chinese sports delegation as it competes in international events such as the 2026 Asian Games, and will deepen its strategic cooperation with Stephen Curry and “Curry Brand”.
  3. Elevating both the quality and efficiency of business operations: The Group will focus on the three core pillars of channel layout, merchandise systems and supply chain integration, accelerating online-offline integration, prioritising the scalable replication of innovative store formats such as “Loong Store”, and building a flexible supply chain system that is high-efficiency, low-cost and fast-response.
  4. Strengthening the foundation to safeguard development: The Group will reinforce its operating foundation across talent, finance and digital intelligence, building out its talent pipeline, maintaining ample cash flow and a rigorous risk control mechanism, and advancing the deep penetration of artificial intelligence and digital technologies across the full scenarios of R&D, production and channels.

Mr. Li Ning, Executive Chairman and Joint Chief Executive Officer of the Group, commented,“The year 2026 marks the opening year of the ’15th Five-Year Plan’. Although the external trade landscape was complex and volatile in the first half of the year and structural divergence in the domestic consumer market persisted, consumption in functional niche segments such as professional sports and urban outdoor remained resilient, supported by a series of national policies to expand domestic demand and promote consumption. Facing a challenging external environment, the Group firmly implemented its core development strategy of ‘Single Brand, Multi-categories, Diversified Channels’, achieving steady growth in both revenue and profit while maintaining healthy inventory and working capital levels, a clear demonstration of the resilience of the Group’s operating fundamentals.

Looking ahead to the second half of the year, we will stay rooted locally while looking to the future, seizing the structural opportunities brought by the ’15th Five-Year Plan’ policies to expand domestic demand and build a leading sports nation, advancing the scalable replication of innovative store formats such as ‘Loong Store’, deepening the dual drivers of technological innovation and top-tier sports resources, so as to deliver higher-quality and more sustainable steady operations in return for the long-term trust of our consumers and shareholders.”

Hashtag: #LiNing

The issuer is solely responsible for the content of this announcement.

About Li Ning Company Limited

Li Ning Company Limited is one of the leading sports brand companies in China, mainly operating professional and leisure footwear, apparel, equipment and accessories under the LI-NING brand. The Group has comprehensive research and development, design, manufacturing, marketing, distribution and retail management capabilities. It has established an extensive retail distribution network and supply chain management system in China. We are committed to be the most prominent, stylish, world-leading sports brand from China.

In addition to its core LI-NING brand, the Group also manufactures, develops, markets, distributes, sells various sports products which are self-owned by or licensed to the Group, including Double Happiness (table tennis), AIGLE (outdoor sports) and Kason (badminton), which are operated through joint venture/associate with third parties of the Group.

Navigating Market Cycles with Operational Resilience, Core Business Stabilizes and Rebounds, Marking a Strategic Turnaround and New Growth Phase

HONG KONG SAR – Media OutReach Newswire – 20 August 2026 – ZJLD Group Inc. (“ZJLD” or the “Company”, together with the Company’s subsidiaries, collectively the “Group”) (SEHK stock code: 06979.HK), a flagship enterprise in China’s baijiu industry and the first baijiu company listed on the Hong Kong Stock Exchange, is pleased to announce its interim financial results for the six months ended 30 June 2026 (“FY 2026 1H” or the “Period”)

In the first half of 2026, the broader baijiu industry operated within a demanding macroeconomic environment characterized by structural adjustments and sluggish consumer demand. In response to cyclical headwinds during the Period, the Group proactively optimized its operational strategies, strengthened healthy channel management, and accelerated digital innovation, resulting in comprehensive stabilization and an operational rebound. The year 2026 marks a pivotal strategic inflection point for ZJLD, signaling the completion of a two-year industry-driven consolidation and the onset of a new high-quality growth cycle.

The key financial and business highlights are as follows:

FY 2026 1H

(for the six months ended June 30, 2026)

(RMB‘000)

FY 2025 1H

(for the six months ended June 30, 2025)

(RMB‘000)

Changed by
Revenue 2,546,069 2,497,106 +2.0%
Gross profit 1,520,856 1,474,284 +3.2%
Gross profit margin 59.7% 59.0% +0.7percentagepoints
Profit attributable to equity holders of the Company 580,717 574,771 +1.0%
Net cash generated from/(used in) operating activities (234,035) (322,274) –27.4%
Adjusted net profit (non-IFRS measure) 626,064 613,202 +2.1%
Adjusted net profit margin (non-IFRS measure) 24.6% 24.6% —


Optimized Product Mix Drives Profitability; Multi-Brand Synergy Amplifies Resilience

  • During the Period, the Group recorded revenue of RMB 2,546.1 million, representing a 2.0% year-on-year increase. Gross profit increased by 3.2% to RMB 1,520.9 million, while Adjusted Net Profit reached RMB 626.1 million, up 2.1% year-on-year. Benefiting from an expanded revenue contribution of Sub-premium products and the Li Du brand, alongside streamlined production efficiencies, the Group’s gross margin expanded by 0.7 percentage points to 59.7%. Net cash operation cash outflow narrowed significantly by 27.4%, underscoring rigorous cash flow management and prudent risk control.
  • Zhenjiu (Flagship Brand): Generated RMB 1,342.4 million in revenue during the Period, accounting for 52.7% of total revenue. The Group exercised disciplined control over channel fulfilment ahead of the launch of the next-generation Zhen 15 to safeguard channel pricing integrity. Meanwhile, the strategic flagship product “Da Zhen” achieved strong growth and explosive nationwide expansion across 31 provinces and 280 cities, driving Zhenjiu’s gross margin up to 59.8%.
  • Li Du (Second Growth Engine): Accelerated its growth momentum, recording revenue of RMB 788.0 million, sharply up 28.9% year-on-year. Driven by the national expansion of its Sub-premium and Mid-tier product portfolio, such as Li Du Sorghum 1975 (李渡高粱 1975), Li Du Sorghum * Changyin Collection Series (李渡高粱酒 · 暢飲珍藏版), and the Li Du King Series (李渡王系列), Li Du demonstrated formidable, explosive market penetration and volume growth.
  • Xiangjiao & Kaikouxiao (Regional Powerhouse): Maintained solid market share within Hunan Province, generating RMB 282.8 million, up 2.0% year-on-year, and RMB 81.8 million, up 1.0% year-on-year, respectively in revenue, both delivering sustained market stabilization and modest growth.
  • Sub-Premium Baijiu Segment: Delivered exceptional performance, achieving revenue of RMB 1,366.1 million, up 39.1% year-on-year. The segment’s contribution to overall revenue surged from 39.3% to 53.7%, reflecting the Group’s agile realignment with evolving consumer shifts toward rational spending and banquet occasions (e.g., weddings and celebrations), successfully capturing growth opportunities in the sub-premium segment.
  • The Board of Directors does not recommend the declaration of an interim dividend for the six months ended 30 June 2026 (FY 2025 1H: nil).


Strategic Agility: Pioneering Channel Innovation & Digital Synergy as Dual-Engine

The Group’s proprietary “Premier Retailers Alliance” model and the Monthly Profit-sharing Model (“月月分利模式”) designed for the 5th Generation Zhen 15 have effectively resolved long-standing industry pain points, such as price inversion and distributor margin compression. By establishing competitive monthly margins, automating online ordering, and offering a share-linked sales incentive plan with certain distributors, the Group successfully attracted and retained high-calibre distributors with strong group-selling capabilities and direct access to end consumers. As of 30 June 2026, the Group’s distributor network expanded to 8,993 partners, an increase of 710 from the end of 2025.

Complementing this channel evolution, the Group adopted an omnichannel marketing framework combining “Community Penetration + Digital Empowerment”. Chairman Wu Xiangdong’s executive video channel (“Wu Jindong – ZJLD, 吳金東-珍酒李渡“) and regional cultural livestreams topped the “Entrepreneur Video IP 100 List” (企業家視頻IP100榜單) for seven consecutive months, averaging over one million views per broadcast. This sparked widespread co-created content with members of the Premier Retailers Alliance (萬商聯盟), creating a powerful online-to-offline traffic funnel. Simultaneously, Zhenjiu’s brand value rose to RMB 34.685 billion, a 103% gain over five years, solidifying among China’s top three sauce-aroma baijiu brands.

Forward-Looking AI Integration and Enterprise Digitization
The Group anchors its digital transformation strategy on operational capability and sustainable value creation. During the Period, in partnership with China Unicom, the Group developed an “AI + Expert Blending” framework powered by Large Language Models (LLMs). This synthesis of traditional heritage and advanced AI enables intelligent blending, elevating consistency, efficiency and craft precision. Furthermore, the Group upgraded Da Zhen‘s digital coding system to a “Six-Code” integration architecture, incorporating NFC anti-counterfeiting and ceramic jar storage metrics, as well as an RFID smart case labelling system to track and ensure precise volumetric measurement and end-to-end lifecycle traceability for every Da Zhen product. Zhenjiu was also awarded the national Data Management Capability Maturity Model (DCMM) Level 3 (Robust) accreditation, further validating its AI deployment and digital leadership.

Deepening Operational Foundations to Drive the New High-Quality Growth Cycle
Looking ahead to the second half of 2026 and beyond, ZJLD will maintain strategic poise by extending proven operational frameworks, such as the “Premier Retailers Alliance” and “Monthly Profit-sharing Model” to Zhen 30 and other core product lines. This initiative will precisely activate high-end and mid-tier markets while strengthening portfolio synergies across all price ranges. Concurrently, the Group will deepen its operation-sales decoupling (營銷分離) mechanism, rigorously monitor channel pricing, protect distributor profitability, and prioritize storage facility construction across its five major production facilities, namely Zhen Jiu Mao Tai Shuang Long (茅台鎮雙龍), Zhen Jiu Bai Yan Gou (白岩溝), Zhen Jiu Zhao Jia Gou (趙家溝), Li Du Zheng Jia Shan (鄭家山) and Xiang Jiao Jiang Bei (江北) to reinforce its long-term competitive moat.

Mr. Wu Xiangdong, Founder and Chairman of ZJLD Group, remarked, “Baijiu is a business that demands patience and reverence—time speaks through quality, and authentic fragrance endures. Over two years of industry rebalancing, our distributor partners and we have navigated genuine challenges and hardships; yet this period offered an invaluable window for reflection, consolidation, and self-reinvention. The deeper the valley, the more vital it is to stay grounded and focus on disciplined execution. Our stabilization in the first half of 2026 is the natural reward of diligent work and marks the dawn of a new growth phase. There are no shortcuts in business—only an uncompromising pursuit of quality, continuous market exploration, and adaptability in the face of change. In times of adversity, we chose to brew finer liquor, preserve channel profitability, and deliver utmost sincerity to our consumers. The launch of the ‘Premier Retailers Alliance’ and ‘Monthly Profit-sharing Model’ models ensures that every partner who trusts ZJLD enjoys security, clarity, and equitable rewards amid challenging conditions.

Engaging directly with consumers and merchants through digital broadcasts has reinvigorated my entrepreneurial passion and joy, which I felt when I first entered the baijiu industry. The consumers’ appreciation for fine baijiu remains undiminished, and their yearning for a better life remains passionate. 2026 serves as ZJLD’s springboard for a renewed journey. We remain a dedicated team of idealistic distillers, honoring nature’s harvest, grateful for the passage of time, and optimistic about the industry’s future. ZJLD will move forward with resilience, innovation, and an open heart alongside all our companions—cheers to bright moments and the journey ahead.”

Hashtag: #ZJLDGroup

The issuer is solely responsible for the content of this announcement.

About ZJLD Group Inc.

Zhen Jiu was established in 1975 in Zunyi, Kweichow, China’s primary production area of sauce-aroma baijiu. In 1988, it was honored with the National Quality Award at the 5th National Wine Appreciation Conference. In the same year, it was announced by the Protocol Department of the Ministry of Foreign Affairs, the Communication Department of the Ministry of Economy and Trade, and the Great Hall of the People Management Bureau to become one of the two sauce-aroma baijiu served at state banquets. It is also known as one of the “Three Representative Baijiu Brands in Kweichow”.

ZJLD Group Inc. is a leading baijiu group in China devoted to offering premium baijiu products, including sauce-aroma, mixed-aroma, and strong-aroma varieties. According to Frost & Sullivan statistics, the flagship brand Zhenjiu has maintained its position for two consecutive years (2023 and 2024) as the fourth-largest sauce-aroma baijiu brand in China and the third-largest in Guizhou Province, by revenue. The Company operates four baijiu brands in China, including two national baijiu brands, Zhen Jiu and Li Du, and two regional brands, Xiangjiao and Kaikouxiao. ZJLD prides itself on inheriting the time-honored baijiu-brewing techniques and reinvigorating them to develop iconic products. It strives to create a wide variety of aromatic and mellow baijiu products to meet consumers’ diverse preferences, seize broader market opportunities, and promote traditional Chinese baijiu culture.

Matein Khalid So far, 2026 has been the best of all possible worlds for US money centre bank shares and Wall Street brokers, a Panglossian season of peak profits and blowout capital markets revenue growth. While software, memory and AI infrastructure stocks took a bungee jump on the Nasdaq in July, the major banks benefited from the SpaceX mega IPO, which generated a $500 million fee jackpot for […]

Arabian Post Staff -Dubai ADQ has proposed buying all remaining shares in AD Ports Group for cash, potentially giving Abu Dhabi’s sovereign investment structure full ownership of one of the emirate’s most important ports, shipping and logistics businesses. The Abu Dhabi investment company, whose assets and investments were brought under the umbrella of sovereign investment platform L’IMAD earlier this year, holds about 75.42% of AD Ports Group. […]

Arabian Post Staff -Dubai Mubadala Investment Company has increased its stake in Aldar Properties to 28.03 per cent, deepening its exposure to one of Abu Dhabi’s largest listed property groups as the developer expands its residential, commercial and recurring-income businesses. The Abu Dhabi sovereign investor raised its holding from 27.01 per cent through Mamoura Diversified Global Holding, its wholly owned subsidiary. The additional shares were accumulated through […]

Arabian Post Staff -Dubai Dubai stocks ended lower on Friday as disappointing corporate earnings and escalating tension around the Strait of Hormuz weighed on investor sentiment, while Abu Dhabi’s benchmark managed a marginal gain. The Dubai Financial Market’s main index fell 0.4%, extending losses for a second consecutive session. Air Arabia and contractor ALEC Holdings were among the biggest drags after their quarterly results disappointed investors. Emaar […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA
Just in:
Jaiedco and Golden Bridge Announce Strategic Collaboration for a New Dubai Islands Development // Singapore regulator cautions against AI access to bank logins // Phancy Announces Business Performance for the Nine Months Ended September 30, 2026 //
Centre grants aircraft cabin access for Sabarimala pilgrims’ irumudi
// Energy Markets Find Little Substance In Shenzhen Summit Promises // PayerMax and ShopeePay Strengthen Strategic Partnership to Advance Digital Payment Collaboration in Southeast Asia // Saudi Arabia schedules multinational top-up tax for 2027 // Technology at Work, Heritage for All: The “Chinese Approach” to Safeguarding the Leshan Giant Buddha // Promoting Common Human Development Through Exchanges and Mutual Learning Among Civilizations // Dubai Introduces SHARH, an AI-Powered Platform Helping Entrepreneurs Buy, Sell and Manage Businesses in the UAE // Padmini follows Padmaja for ‘ghar vapsi’ // Crypto market loses $150 billion amid broad sell-off // Workday targets Honeydew purchase to unify AI metrics // Balagopal challenges CM over tax revenue // ED searches five districts in probe against hawala // Sui activates Hashi Bitcoin lending across partner network // Russia permits retail cryptocurrency purchases under regulated framework // Diabetes Malaysia And Alpro Pharmacy Set National Record With 11,007 Most Blood Glucose Screenings Conducted Across Malaysia In Just 48 Hours // Saudi defences destroy three Houthi missiles targeting Riyadh // Dalilk Academy reaches 27 million, targets 100 million by 2030 //