Articles written by
arabian post staff

Dubai has rolled out a new initiative aimed at recognizing exceptional educators within its private school system. Sheikh Hamdan bin Mohammed bin Rashid Al Maktoum, Crown Prince of Dubai, announced the eligibility criteria for private school teachers to apply for the UAE Golden Visa. The program, which was introduced on World Teachers’ Day, is part of a broader effort to appreciate the crucial role educators play in shaping Dubai’s future generations.

The Knowledge and Human Development Authority (KHDA) detailed the selection criteria that will allow teachers to qualify for the long-term residency permit. Only those who demonstrate outstanding achievements in their profession will be eligible to apply for the visa. This move is seen as a significant boost to Dubai’s private education sector, providing long-term stability and rewards to teachers who make substantial contributions to their students’ success.

Saudia and Delta Air Lines have announced a strategic partnership aimed at significantly enhancing their global network, promising to expand travel options for passengers around the world. This collaboration is expected to strengthen their respective positions in the aviation market, allowing for a more integrated travel experience for customers flying between the United States and the Middle East.

Under the agreement, both airlines will offer reciprocal codeshare flights, facilitating smoother connections and increased travel options. This partnership is set to take effect soon, allowing travelers to book flights seamlessly across the two carriers’ networks. Customers will benefit from access to a broader range of destinations and improved connectivity between major cities in the United States, Saudi Arabia, and other international locations.

The collaboration comes at a time when the aviation industry is gradually rebounding from the challenges posed by the COVID-19 pandemic. Demand for air travel has been on the rise, particularly in the long-haul market, and both Saudia and Delta are eager to capitalize on this trend. The partnership allows both airlines to leverage their strengths, with Saudia providing extensive connections in the Middle East and Delta offering a robust presence in North America.

Delta Air Lines, based in Atlanta, Georgia, has long been a key player in the U.S. aviation sector, known for its extensive domestic and international network. Saudia, the national carrier of Saudi Arabia, boasts a strong foothold in the Middle East and Asia, operating flights to numerous destinations across the globe. By joining forces, both airlines aim to enhance their operational efficiencies while providing better service to their customers.

The expansion of the partnership is particularly timely as travel demand surges in key markets. The Middle East, in particular, has seen a significant increase in tourism and business travel, driven by a growing appetite for international travel. Saudia’s existing routes to cities like Riyadh, Jeddah, and Dammam complement Delta’s offerings from various U.S. hubs, creating a more attractive proposition for travelers looking to explore these regions.

This alliance reflects a broader trend in the aviation industry where airlines are increasingly seeking strategic partnerships to bolster their networks and market share. Codeshare agreements allow airlines to collaborate on pricing, scheduling, and marketing, thereby enhancing their competitive edge. As air travel continues to evolve, such partnerships are likely to become more common as airlines adapt to changing market conditions.

With this partnership, passengers will also have the advantage of combined loyalty programs, allowing travelers to earn and redeem miles across both airlines. This integration is expected to enhance customer satisfaction and encourage loyalty, as travelers increasingly prefer airlines that provide seamless travel experiences.

The collaboration aligns with the growing focus on sustainability in the aviation industry. Both Saudia and Delta have committed to reducing their carbon footprints and improving operational efficiencies. This partnership is expected to facilitate more efficient route planning and flight scheduling, ultimately contributing to a greener aviation sector.

Industry analysts view this collaboration as a significant move, potentially reshaping the competitive landscape in international air travel. By combining their resources, Saudia and Delta can provide more comprehensive travel solutions, catering to the needs of both leisure and business travelers. As global travel restrictions ease and demand for air travel grows, this partnership positions both airlines well to capture a larger share of the market.

In addition to expanding their network, this collaboration is likely to benefit cargo operations as well. Both Saudia and Delta have strong cargo divisions, and the partnership may lead to increased efficiency in cargo transportation between the U.S. and the Middle East. This could be particularly advantageous for businesses looking to streamline their supply chains and enhance their logistics capabilities.

The partnership is expected to evolve further, with both airlines exploring additional areas of collaboration. This may include joint marketing initiatives, shared airport lounges, and other customer-centric services that enhance the overall travel experience. As the aviation industry continues to recover, partnerships like this one will be crucial for airlines seeking to innovate and adapt to new market realities.

As the collaboration between Saudia and Delta Air Lines unfolds, it will be essential for both airlines to maintain a keen focus on customer service and operational excellence. Travelers will be looking for reliable, efficient, and enjoyable travel experiences, and both carriers will need to deliver on these expectations to ensure the partnership’s success.

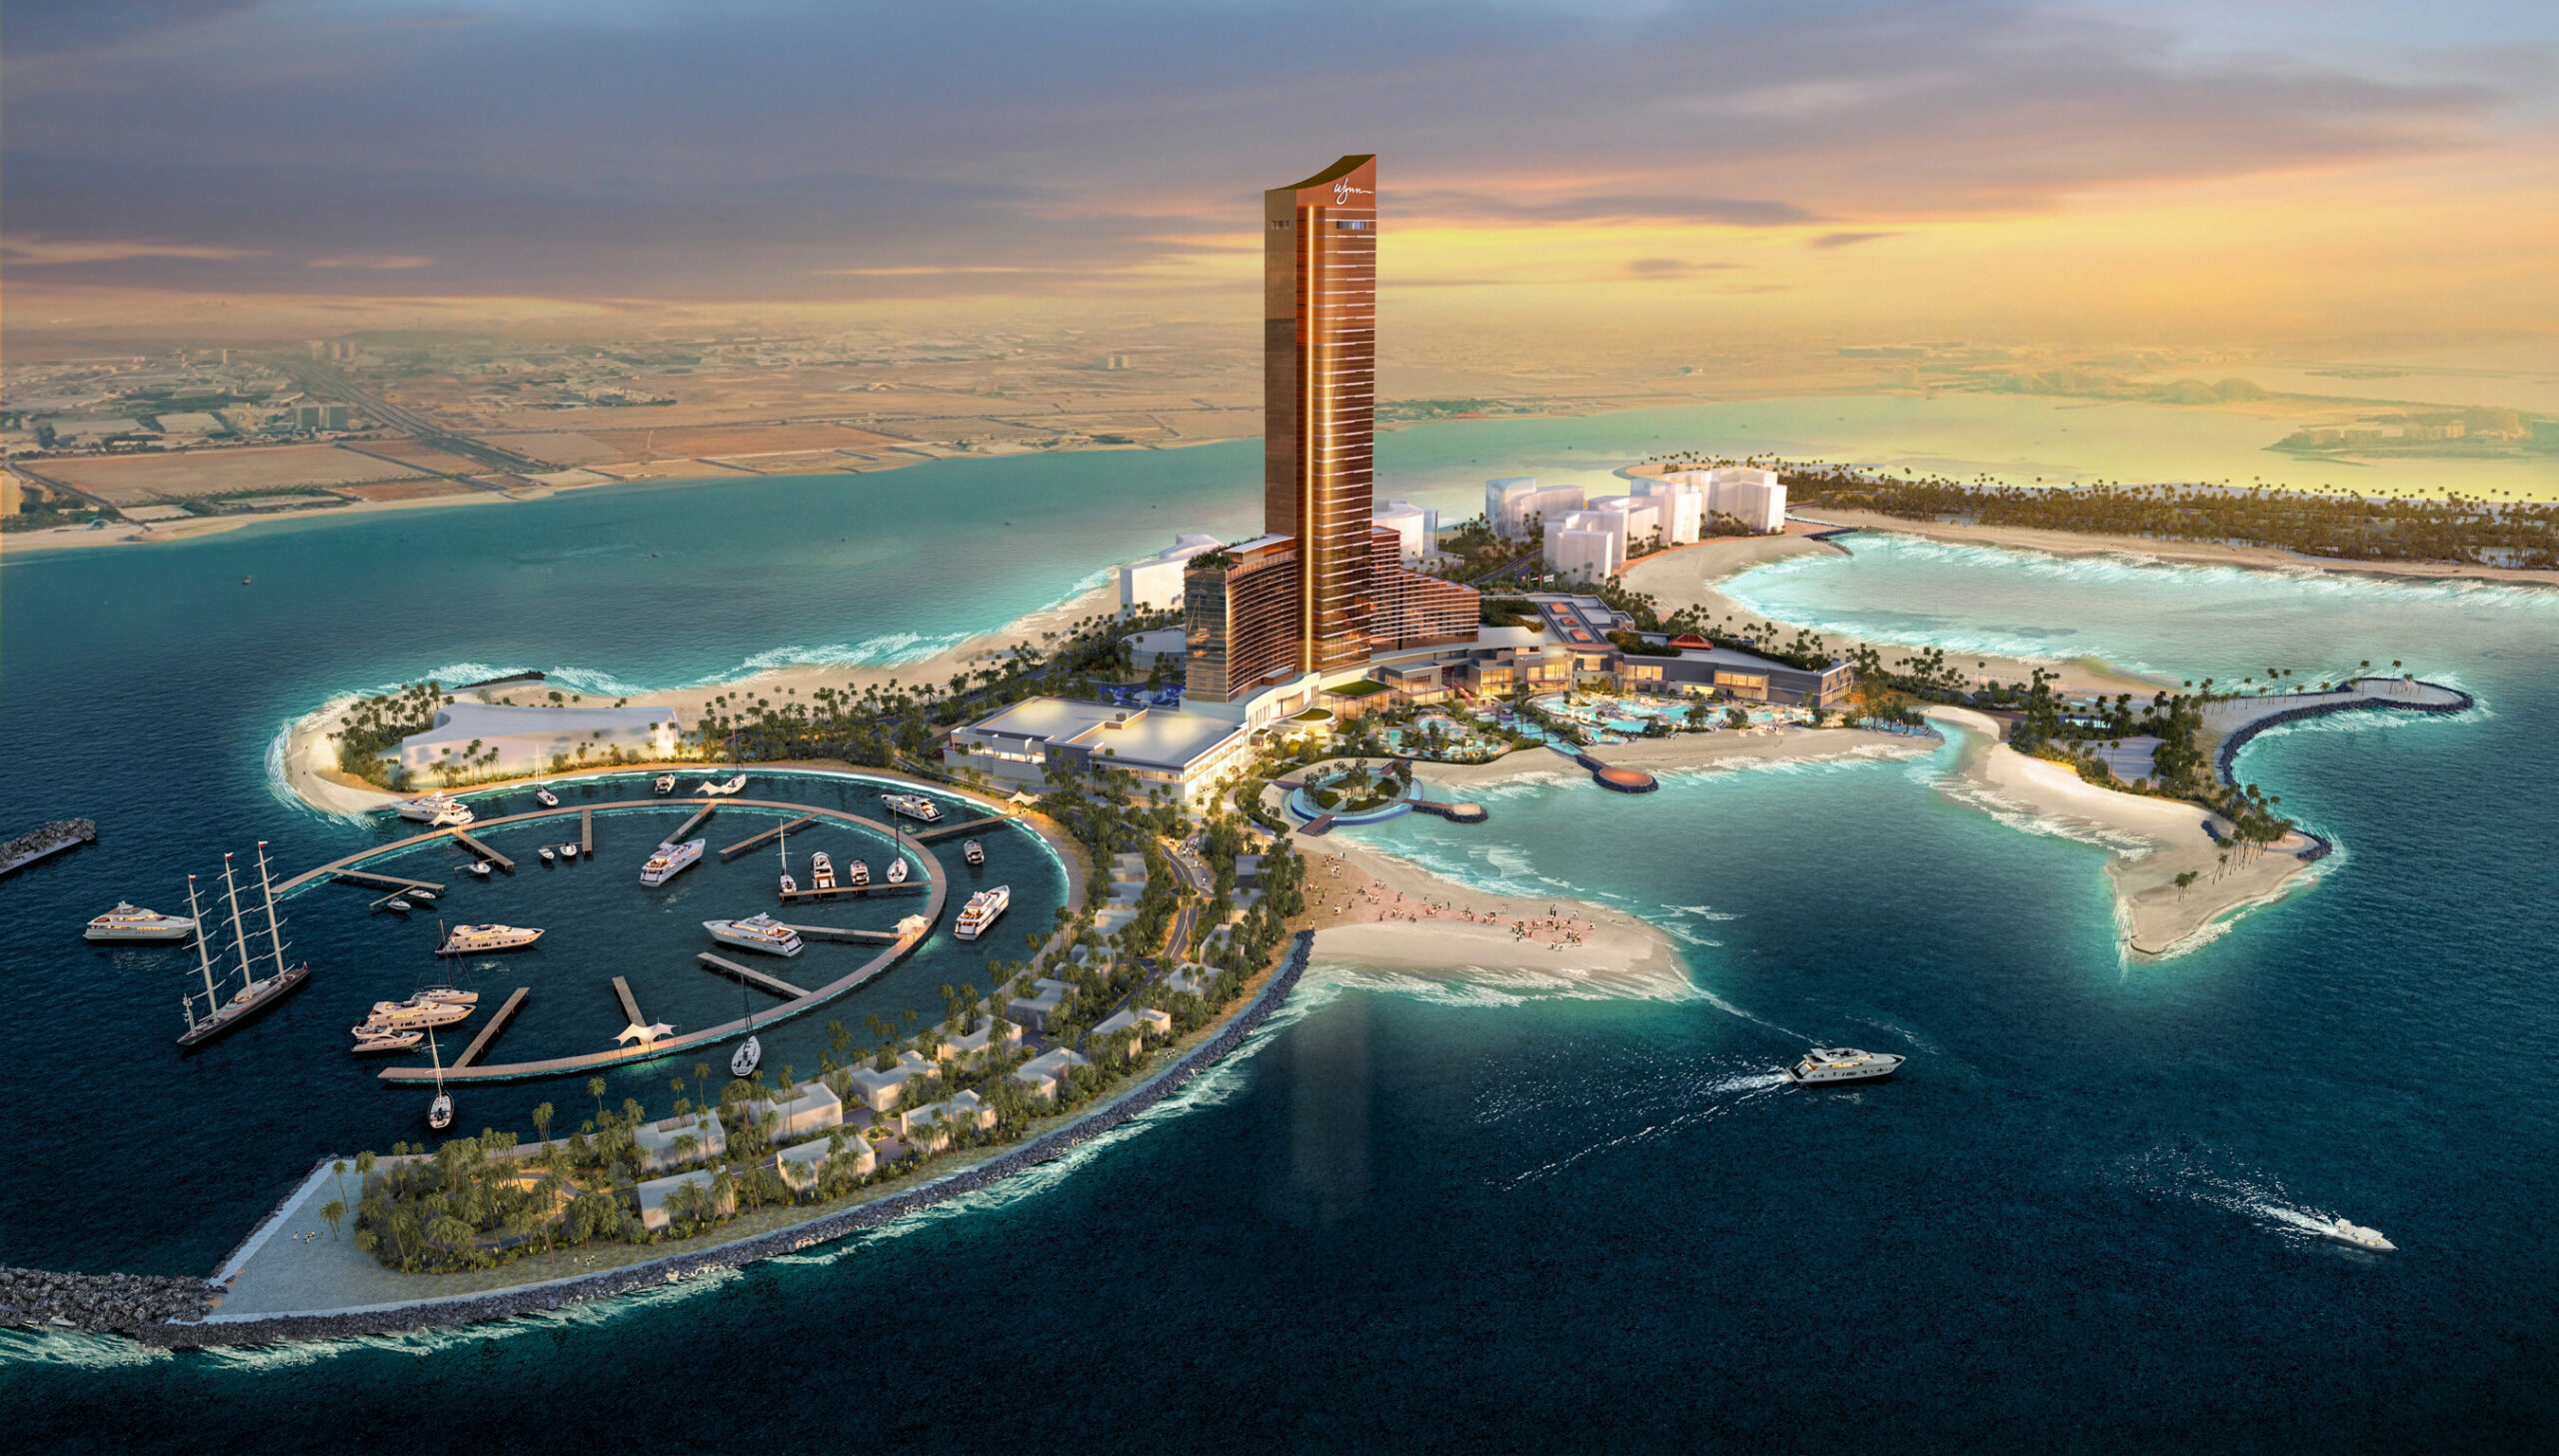
Wynn Resorts has officially received the first gaming license ever granted in the United Arab Emirates (UAE), marking a pivotal moment in the nation’s evolving stance towards regulated gambling. This approval paves the way for the company’s new multibillion-dollar integrated resort, which is currently under construction in Ras Al Khaimah and slated to open by 2027.

This significant development follows months of anticipation regarding the UAE’s potential move toward legalizing gambling, with Wynn Resorts at the center of the speculation. The project, titled Wynn Al Marjan Island, will include a luxury hotel, entertainment venues, and the nation’s first licensed casino, offering a highly curated experience that mirrors the glamour of Wynn’s Las Vegas operations. Wynn Resorts has expressed confidence in its ability to navigate the cultural and regulatory landscape in the region, highlighting that the gaming element will be incorporated sensitively to align with local expectations.

Ras Al Khaimah’s Tourism Development Authority has been instrumental in enabling this venture, introducing a new regulatory framework specifically to manage gaming activities. The Emirate’s regulations, crafted to uphold international standards of compliance, ensure responsible gaming practices are adhered to, with a focus on safeguarding social and economic interests. Ras Al Khaimah’s move appears strategic, aiming to bolster its tourism industry and compete with regional hubs, such as Dubai and Abu Dhabi, that have traditionally attracted tourists for non-gaming entertainment and luxury experiences.

For Wynn Resorts, this project marks its first foray into the Middle Eastern market, a bold step that positions the company as a trailblazer in the region’s nascent gaming sector. While Las Vegas Sands and MGM Resorts have also shown interest in expanding into Middle Eastern markets, Wynn’s success in securing the first license puts it ahead of its competitors.

As discussions about regulated gambling gain momentum across the UAE, it remains unclear whether this approval will set a precedent for future gaming licenses or whether Ras Al Khaimah will maintain its unique status. The UAE has long maintained strict regulations prohibiting gambling, making this decision a watershed moment for the country’s economic and social policies.

The investment is anticipated to bring significant economic benefits, with the resort set to create thousands of jobs and drive tourism to Ras Al Khaimah. Industry experts expect that the integrated resort could attract high-net-worth individuals from across the Gulf region, Europe, and Asia, helping to diversify the Emirate’s economy. This new focus on gaming as part of a broader tourism strategy represents a notable shift in Ras Al Khaimah’s ambitions to compete on a global scale.

Wynn Resorts, which operates successful properties in Las Vegas, Macau, and Boston, has stated that it aims to replicate the high standards of luxury and entertainment that it is known for worldwide. The company remains tight-lipped about the specifics of the gaming offerings, although it has been suggested that the casino will cater primarily to international tourists rather than local residents.

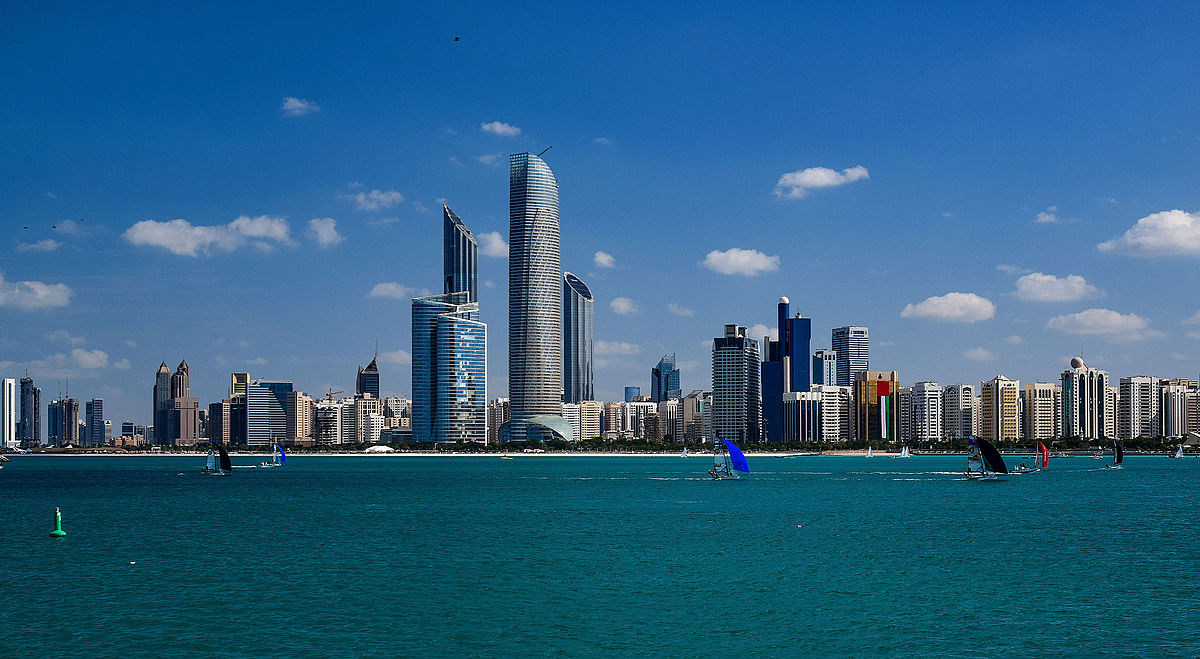
Family offices are playing a transformative role in Abu Dhabi’s economic landscape, driving diversification and growth across various sectors. Representing a significant portion of privately owned businesses in the UAE, these entities have expanded beyond traditional investments in real estate and finance, contributing to the emirate’s ambitions for sustainability and innovation.

Key developments in Abu Dhabi, such as the Abu Dhabi Industrial Strategy (ADIS), highlight the growing importance of family offices in fostering industrial growth, technology advancement, and clean energy projects. Under this strategy, the industrial sector’s GDP saw a remarkable surge from AED 83 billion in 2022 to AED 101 billion by 2023, with family offices continuing to boost these efforts through large-scale investments.

Family offices are now focusing on high-impact sectors like infrastructure, technology, and renewable energy, aligning with the emirate’s long-term goals. Their involvement is particularly notable in collaborative initiatives with the Abu Dhabi government, exemplified by agreements under programs like the Musataha initiative, which fosters private investment in state-owned land for community-driven projects.

The leadership in Abu Dhabi, including figures like Ahmed Jasim Al Zaabi, chairman of the Abu Dhabi Department of Economic Development, has been vocal about the strategic role of these family-owned businesses. Al Zaabi emphasized how initiatives like ADIS are not only growing the industrial sector but also positioning the emirate as a hub for innovation, advanced manufacturing, and clean technology.

Dubai’s Roads and Transport Authority (RTA) has lifted the restriction on foldable e-scooters within the Dubai Metro and Tram system, marking a shift in transport policy that comes with a firm set of guidelines. The RTA had initially introduced the ban in March 2024, citing concerns for commuter safety. However, with revised safety protocols in place, e-scooter riders are once again permitted to carry their devices on public transit, provided they adhere to stringent conditions aimed at maintaining safety and order within metro and tram stations.

The decision to relax the ban coincides with an increase in the popularity of e-scooters as a convenient mode of transport, especially for the last-mile commute in Dubai’s growing urban landscape. Foldable e-scooters have now been given the green light, provided they meet specific criteria set by the RTA. These scooters must be no larger than 120cmx70cmx40cm and weigh no more than 20kg. Additionally, they must be folded and placed in designated areas when inside stations or on public transport. This move comes as part of Dubai’s broader strategy to enhance eco-friendly transportation options, integrate diverse mobility solutions, and alleviate congestion in high-density areas.

Safety, however, remains a top priority. The new rules emphasize that riding e-scooters inside stations or on public transport is strictly prohibited, with the RTA reiterating that passengers must fold their scooters upon entering metro or tram premises. Failure to comply with these rules could lead to penalties, as part of the city’s drive to maintain high safety standards in public areas.

This policy adjustment reflects Dubai’s commitment to promoting sustainable transport, aligning with global trends that see cities embracing micro-mobility solutions. With e-scooters gaining traction in urban areas worldwide, especially in Europe and the US, cities are increasingly adopting frameworks to ensure these devices coexist safely with other forms of transport.

RTA’s renewed focus on safety is also evident in the broader context of its micro-mobility regulations. In addition to the size and weight restrictions, users are reminded that scooters must meet specific technical standards, such as brake functionality and proper lighting. Moreover, the RTA has announced that it will continue to monitor compliance and may introduce further updates to these regulations as necessary.

This regulatory shift follows a period of deliberation and review after the initial ban was imposed earlier this year. Public feedback and input from safety experts were reportedly considered in developing the new rules, ensuring that e-scooters can be integrated into the city’s public transport network without compromising the safety of metro and tram passengers.

By lifting the ban and putting these guidelines in place, Dubai joins a growing number of global cities that are actively working to incorporate micro-mobility solutions into their transport networks. It is yet another step in Dubai’s transformation into a smart city, enhancing the quality of life for residents by providing more flexible and sustainable transport options.

For e-scooter users, the easing of restrictions offers new convenience, particularly for commuters looking to bridge the gap between metro stations and their final destinations. As this mode of transport continues to evolve, the RTA is expected to remain vigilant in enforcing safety measures and adapting to the needs of a rapidly changing urban mobility landscape.

The International Monetary Fund (IMF) has raised serious concerns over the potential economic fallout from the escalating conflict in the Middle East. As violence spreads and tensions rise, the conflict threatens not only the region’s stability but also the global economy, particularly through disruptions in energy supplies, trade routes, and investor confidence.

The war in Gaza has intensified, drawing in multiple countries and raising fears of broader regional involvement. The IMF’s latest assessments highlight the possibility of severe economic impacts, particularly on energy markets. With the Middle East responsible for a significant portion of the world’s oil production, any disruptions could lead to increased volatility in oil prices. The IMF warned that sustained conflict could push oil prices higher, potentially surpassing $100 per barrel, a figure already approached during earlier hostilities this year. This price surge would have far-reaching consequences, especially for oil-importing nations, straining budgets and intensifying inflationary pressures.

Global financial markets have already shown signs of nervousness. Investors, traditionally wary of instability in key regions, have begun reallocating assets, with several stock indices experiencing sharp drops. Analysts suggest that if the conflict escalates further, the damage could spread beyond energy markets, affecting sectors such as manufacturing and technology that rely heavily on supply chains running through or near conflict zones.

The IMF’s mission chief underscored that while oil prices are the most immediate concern, the broader economic picture is equally troubling. Trade disruptions, particularly in critical shipping lanes like the Suez Canal, could severely impact the flow of goods, exacerbating the already fragile global supply chains. For nations in the region, the toll could be devastating. Countries like Lebanon and Egypt, already grappling with economic crises, could face further destabilization, compounding their debt issues and putting millions more at risk of poverty.

While energy exporters such as Saudi Arabia and the UAE may temporarily benefit from higher oil revenues, the broader economic instability could erode those gains, particularly if conflict spreads further across the region. Additionally, prolonged unrest could deter much-needed foreign investment in the Gulf region, which has been aggressively pursuing diversification away from oil dependency.

The IMF’s warning also extends to food security concerns, as the Middle East plays a crucial role in global grain trade. Egypt, for instance, is one of the world’s largest wheat importers, and disruptions to shipping could lead to shortages and price hikes. This would disproportionately affect lower-income nations, already struggling with inflationary food costs and economic stagnation.

As the situation continues to evolve, the IMF has urged regional governments and the international community to take immediate steps to prevent further escalation. In addition to diplomatic efforts, the IMF is advocating for emergency economic measures to protect the most vulnerable economies. These include securing financial aid, stabilizing food supply chains, and safeguarding energy markets from excessive speculation.

However, the global response remains uncertain. While Western powers and international organizations have expressed concern, efforts to mediate the conflict have so far been limited. The longer the fighting continues, the higher the economic risks become, making it crucial for governments to work towards de-escalation before the crisis spirals further out of control.

Dubai’s booming real estate market reached a record-breaking milestone in Q3 2024, posting an unprecedented $38.6 billion (Dh141.9 billion) in sales. This new benchmark represents the highest quarterly sales in the city’s history, surpassing the $33.8 billion (Dh124 billion) set in the previous quarter, underscoring a sustained surge in demand across the property sector.

The latest figures show a significant 30.1% year-on-year growth, signaling robust momentum that has been building throughout 2024. A total of 50,423 property sales were completed during the third quarter, marking a 16.6% rise from Q2 and an impressive 37.9% increase compared to the same period last year.

Apartments remained the dominant driver of this expansion, contributing 77% of all transactions. Over 39,000 apartment sales accounted for a combined value of $19.2 billion (Dh70.5 billion), representing a 43.9% surge in volume from Q3 2023. Villas, too, saw strong performance, with 8,156 units sold, generating $10.7 billion (Dh39.2 billion) in sales, up 16.6% in volume and 18.4% quarter-over-quarter. This marks the continued preference for premium residential living and underscores the growing interest in lifestyle-oriented properties.

The median price per square foot also climbed to $411 (Dh1,511), reflecting the rising property values in the city. The ongoing price appreciation is notable when compared to previous years, with a sharp rise from Dh1,017 per square foot in 2021 to Dh1,405 last year, illustrating the long-term trajectory of property value growth in Dubai.

Advertisements

KEZAD Group has launched a new business vertical named KZ Media, marking its foray into the media services sector. This initiative aims to leverage the increasing demand for integrated media solutions in the United Arab Emirates, catering to both local and international markets. KEZAD Group, a subsidiary of AD Ports Group, is already known as the largest operator of integrated economic zones in the UAE, focusing on providing customized services that enhance business efficiency and growth.

KZ Media is poised to become a comprehensive media outlet offering a diverse portfolio of services. These include content creation, branding, marketing strategies, and digital media management, aimed at assisting businesses in maximizing their outreach and engagement. The establishment of KZ Media reflects KEZAD’s strategy to diversify its offerings and meet the evolving needs of businesses operating within its economic zones. This move underscores the group’s commitment to supporting the growth of various sectors by providing essential services that enhance operational effectiveness.

The launch of KZ Media comes at a time when the media landscape in the UAE is rapidly evolving, driven by advancements in technology and changing consumer preferences. Businesses are increasingly seeking innovative media solutions that not only promote their products and services but also resonate with their target audiences. KZ Media aims to fill this gap by providing tailored media services that are both strategic and creative.

KEZAD Group has positioned itself as a key player in the economic development of the UAE through its focus on creating a conducive environment for businesses to thrive. The introduction of KZ Media aligns with the broader objectives of the group, which include fostering innovation, enhancing competitiveness, and facilitating the growth of a knowledge-based economy. By integrating media services into its portfolio, KEZAD Group is not only expanding its capabilities but also reinforcing its role as a catalyst for business development in the region.

The media sector in the UAE has been witnessing significant growth, with the government actively promoting initiatives to bolster the industry. This is evident from the various media-related events and exhibitions that take place annually, attracting global media players and professionals. The establishment of KZ Media is expected to contribute to this vibrant ecosystem by providing local businesses with access to high-quality media services that were previously limited or unavailable.

KZ Media’s team is expected to comprise seasoned professionals with extensive experience in media and communications, further enhancing the quality of services offered. This expertise will allow the new entity to deliver innovative and impactful media solutions that address the unique challenges faced by businesses in a competitive market. As the media landscape continues to evolve, KZ Media aims to stay at the forefront of industry trends, ensuring that its clients benefit from the latest advancements in media technology and strategy.

The introduction of KZ Media underscores KEZAD Group’s commitment to sustainability and corporate social responsibility. The new entity will focus on creating content that promotes positive narratives and fosters community engagement. By prioritizing socially responsible media practices, KZ Media aims to build trust and credibility among its clients and the broader public.

KEZAD Group’s expansion into the media sector aligns with global trends where integrated services are increasingly becoming a necessity for businesses. Organizations are seeking to consolidate their media and marketing efforts to enhance efficiency and effectiveness. KZ Media is positioned to address these needs by offering a one-stop solution for businesses looking to enhance their media presence and engage their target audiences effectively.

As KZ Media embarks on its journey, it will likely explore strategic partnerships with other media organizations, technology providers, and marketing firms to expand its service offerings further. This collaborative approach will enable KZ Media to enhance its capabilities and offer clients a broader range of innovative solutions tailored to their specific needs.

A groundbreaking initiative has been announced by Dubai Airports, marking the launch of the world’s largest solar rooftop project in collaboration with Etihad Clean Energy Development Company, a fully owned subsidiary of the Dubai Electricity and Water Authority (DEWA). This ambitious project aims to enhance the airport’s sustainability efforts and significantly contribute to Dubai’s clean energy targets.

The project involves the installation of solar photovoltaic panels on the rooftops of Dubai International Airport (DXB) and Dubai World Central (DWC). This effort is part of a broader commitment by Dubai Airports to adopt sustainable practices and support the emirate’s goal of becoming a global leader in renewable energy. The installation will generate a substantial amount of electricity, contributing to the operational energy needs of the airports while reducing carbon emissions.

Expected to generate up to 8 megawatts of power, the solar rooftop installation will occupy over 60,000 square meters of rooftop space across both airports. This initiative aligns with Dubai’s Clean Energy Strategy 2050, which aims to increase the share of clean energy in the city’s total energy mix to 75 percent by 2050. The solar project not only enhances the airports’ sustainability profile but also sets a benchmark for energy efficiency in the aviation sector.

This collaboration underscores the commitment of both Dubai Airports and DEWA to drive sustainable growth and innovation. The installation of solar panels at the airports is a pivotal step towards enhancing energy resilience and reducing reliance on fossil fuels. As part of the project, it is anticipated that the solar energy generated will power various airport facilities, thus optimizing operational efficiency.

The strategic partnership between Dubai Airports and Etihad Clean Energy Development Company highlights the importance of public-private collaborations in achieving sustainability goals. This project is poised to pave the way for similar initiatives in other sectors, reinforcing the UAE’s leadership in renewable energy adoption. Moreover, it exemplifies the proactive measures being taken by Dubai to address environmental challenges while supporting economic growth.

Several key players have contributed to the formulation and execution of this initiative. The project was developed following extensive feasibility studies and consultations with industry experts to ensure that it meets the highest standards of efficiency and effectiveness. DEWA, recognized for its commitment to innovation and sustainability, has been instrumental in supporting the integration of renewable energy solutions across the emirate.

Dubai Airports has a history of implementing sustainability measures, including the introduction of energy-efficient technologies and practices aimed at minimizing the environmental footprint of airport operations. The launch of the solar rooftop project represents a significant milestone in this ongoing effort and showcases Dubai’s ambition to lead by example in the global aviation industry.

In addition to the environmental benefits, the project is expected to have positive economic implications, providing job opportunities in the renewable energy sector and stimulating growth within the local economy. The focus on sustainability aligns with the broader vision of the UAE to diversify its economy and reduce its dependence on oil.

As part of its commitment to sustainability, Dubai Airports continues to explore innovative solutions to reduce energy consumption and enhance operational efficiency. The implementation of solar energy solutions is just one aspect of a comprehensive sustainability strategy that encompasses various initiatives aimed at minimizing waste, conserving resources, and promoting environmentally friendly practices.

This project represents a significant step forward in Dubai’s journey towards achieving a more sustainable future. The commitment to renewable energy aligns with the global shift towards cleaner energy sources and highlights the potential for airports and other major infrastructure to contribute positively to environmental sustainability.

Dubai’s leadership has emphasized the importance of such projects in realizing the emirate’s long-term sustainability goals. The solar rooftop initiative not only demonstrates the feasibility of large-scale renewable energy projects but also serves as a model for other cities and countries looking to enhance their sustainability efforts.

Ajman Municipality and Planning Department (MPDA) signed a significant Memorandum of Understanding (MoU) with TRENDS Research and Advisory, signaling a step forward in enhancing research cooperation. This partnership will focus on conducting joint social, political, economic, and future studies, field surveys, and the exchange of expertise between both organizations. It aims to leverage the skills of experts and researchers from both entities to generate research reports, encouraging professionals to write and contribute to their respective fields.

The agreement outlines collaborative efforts in the areas of social and economic development, aligning with Ajman’s long-term strategy for growth. TRENDS Research and Advisory, known for its robust analytical capabilities and global research projects, will provide Ajman’s municipality with the tools needed to tackle emerging challenges in urban planning and governance.

This agreement will also facilitate a deeper understanding of regional issues through comprehensive research, fostering innovative solutions in governance, policy-making, and infrastructure development. By pooling resources, the two entities will work toward producing reliable data to inform decisions affecting the Emirate’s future.

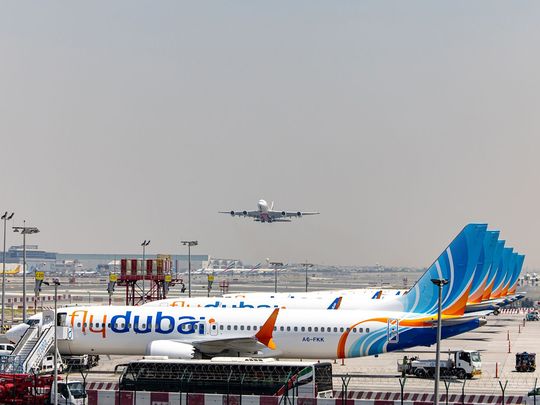
flydubai has confirmed that it will resume operations to key Middle Eastern destinations—Iran, Iraq, Israel, and Jordan—starting from October 4, 2024. This announcement follows temporary suspensions caused by the escalating geopolitical tensions, particularly the outbreak of hostilities between Israel and Hamas on October 1. The airline is closely monitoring the situation and has stated that it will remain flexible with its schedule should circumstances change.

While services to Iran, Iraq, Israel, and Jordan are set to resume, flights to Beirut remain grounded until at least October 7 due to the volatile security environment. Other UAE carriers, including Emirates and Etihad Airways, have extended their suspension of Beirut-bound flights until October 8. Emirates also announced the temporary halt of its flights to Baghdad, Basra, Tehran, and Amman for October 4 and 5, citing security concerns across the region.

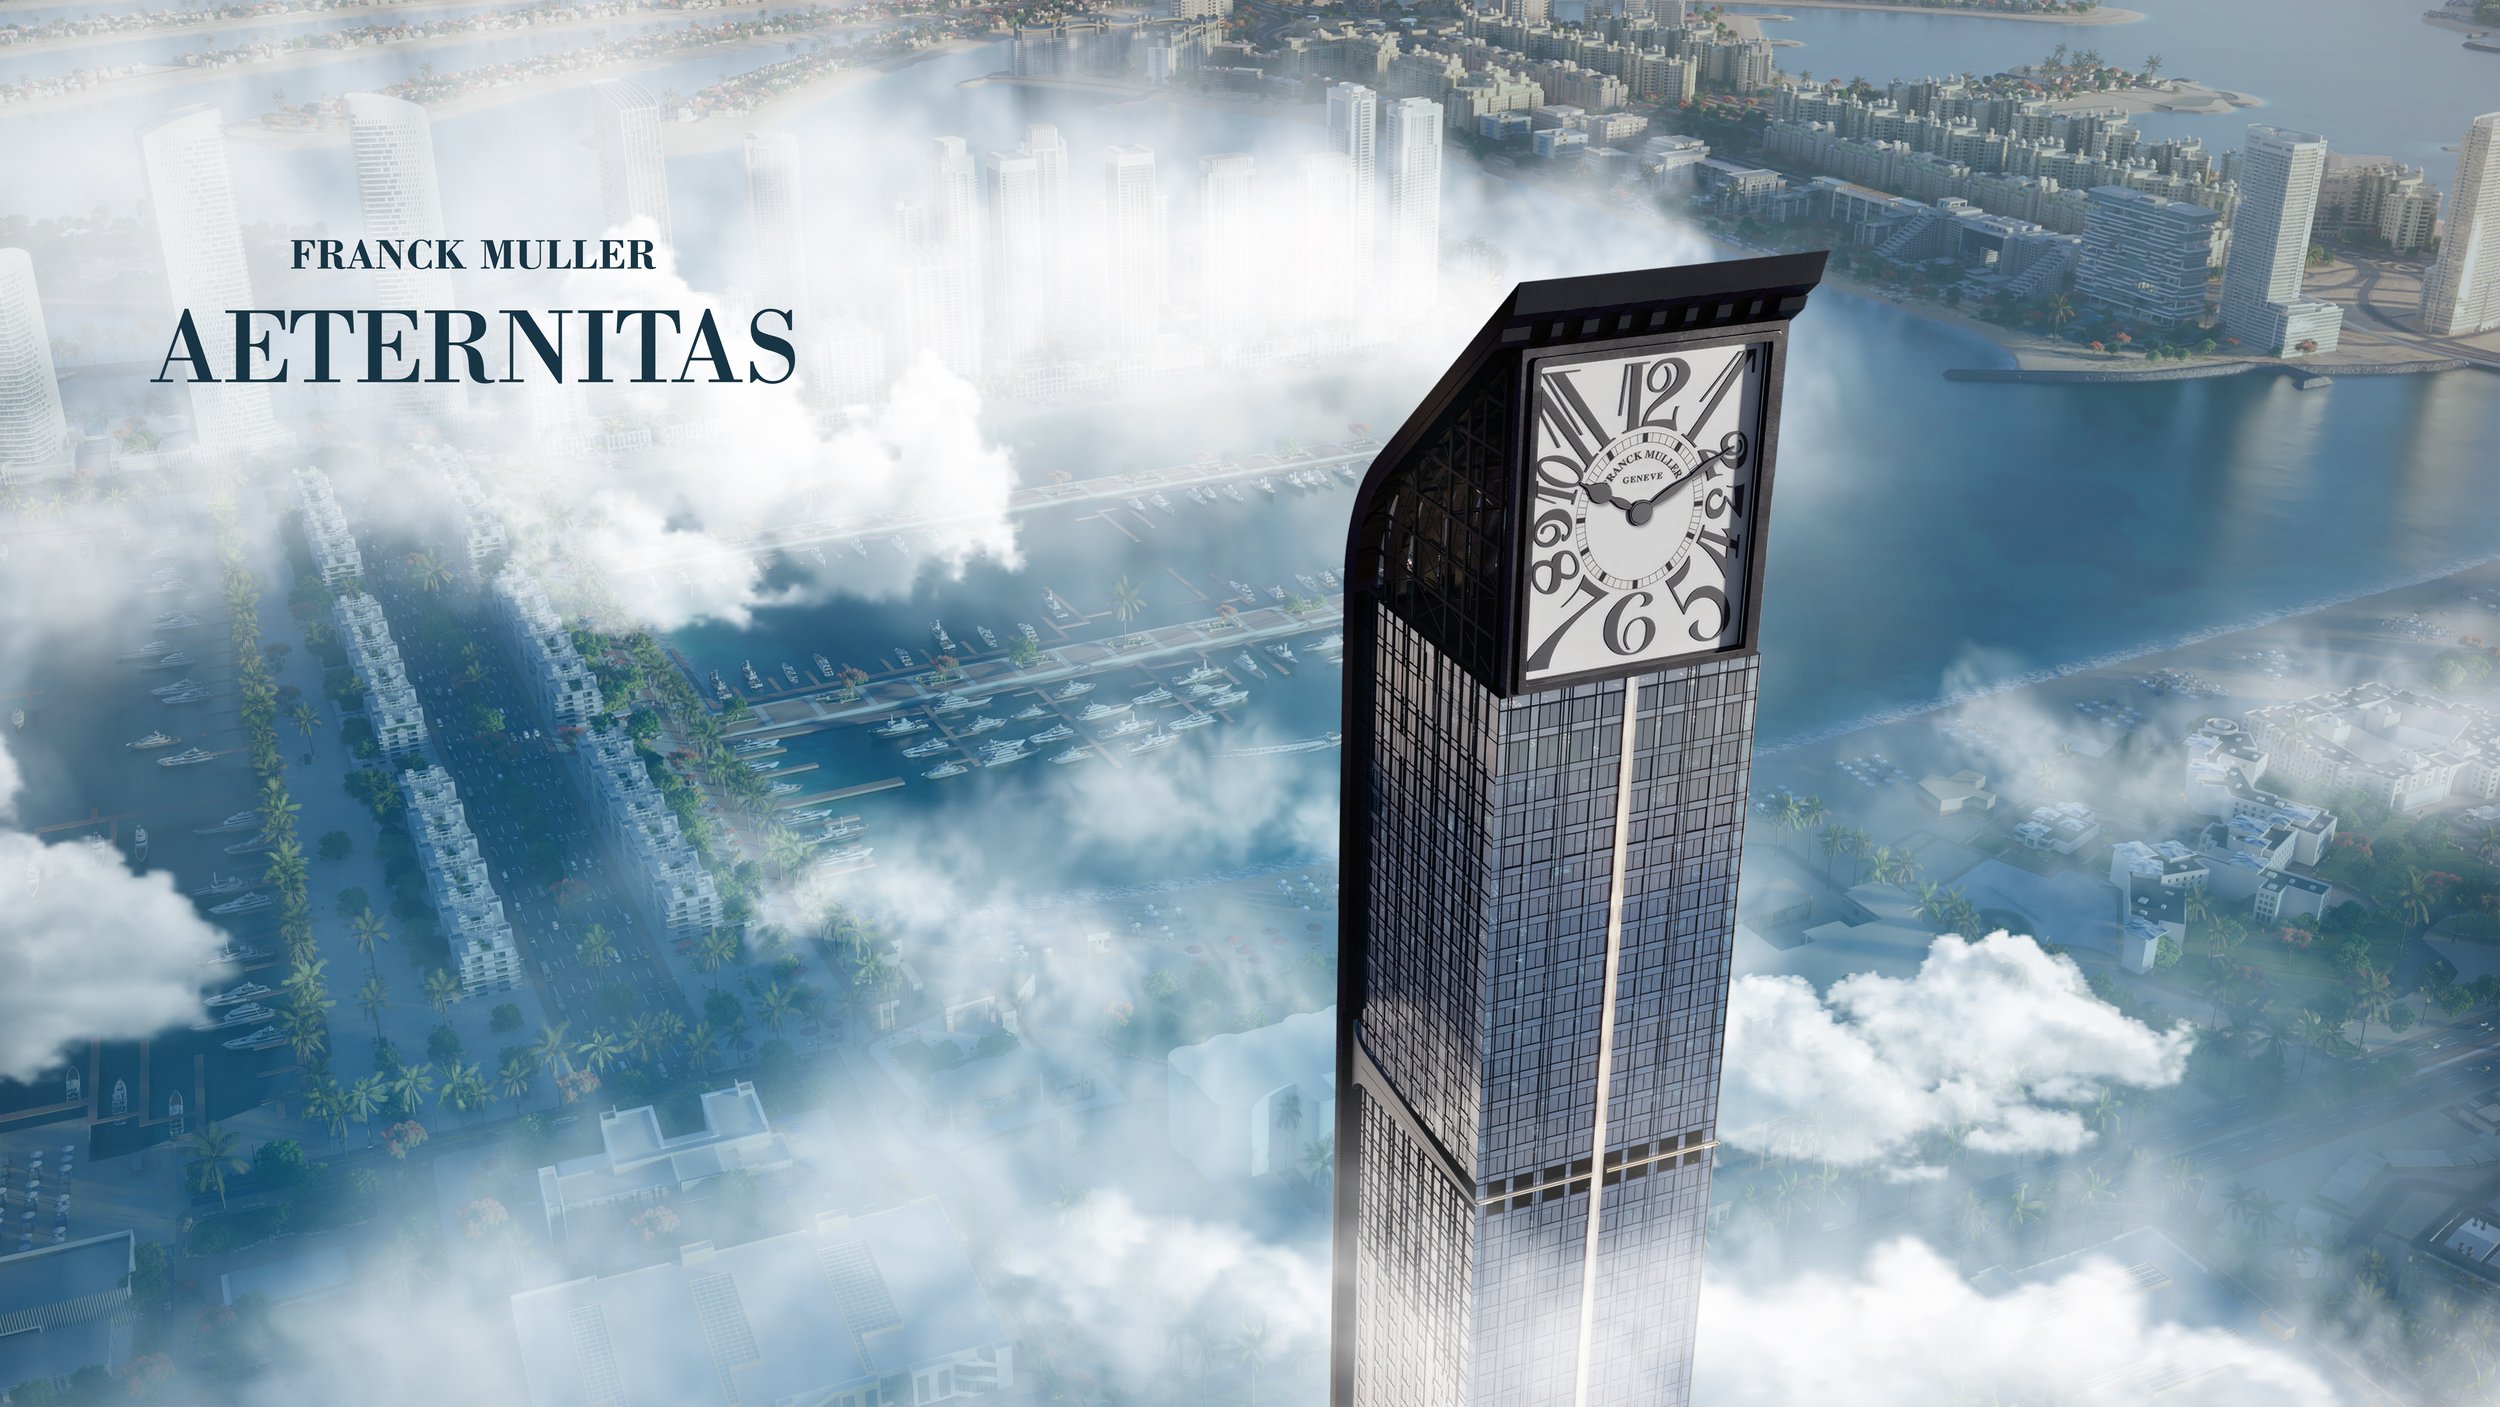
Luxury real estate in Dubai has taken another leap forward as London Gate, a prominent UAE-based developer, and renowned Swiss watchmaker Franck Muller, have unveiled the Franck Muller Vanguard Tower. Set in Dubai Marina, this is their second major collaboration following the successful launch of Franck Muller Aeternitas Tower, which sold out swiftly after its release. The new residential tower promises to raise the bar for high-end living, combining Swiss precision with modern design and cutting-edge amenities.

This latest development continues the partnership between the two luxury brands, targeting an elite segment of homebuyers and investors looking for exclusive real estate in one of Dubai’s most sought-after areas. With its prime location in Dubai Marina, the Vanguard Tower aims to redefine contemporary luxury, blending Franck Muller’s craftsmanship with London Gate’s innovative architectural concepts.

The 38-story tower, designed by DAR Consult, will offer an array of upscale apartments, ranging from studios to three-bedroom units. It will feature state-of-the-art amenities such as a rooftop swimming pool, 24/7 security, dedicated retail spaces, and recreational areas for residents to relax and socialize. Notably, the building will integrate elements inspired by Franck Muller’s watchmaking heritage, reflecting the brand’s ethos of precision and artistry. Delivery is scheduled for the fourth quarter of 2027.

Blackstone Inc. is preparing to launch its third Asia-focused private equity fund, with an ambitious goal of raising more than $10 billion. The move comes as the investment giant continues its aggressive expansion in Asia, particularly in key markets like Japan and India. Sources familiar with the matter indicate that Blackstone’s latest initiative underscores its growing commitment to the region, which has seen heightened interest from global investors seeking opportunities in the fast-evolving economies of Asia.

The firm’s third fund for Asia is anticipated to be one of its largest regional efforts to date, following its previous Asia funds, the last of which closed at $6.4 billion in 2020. Blackstone’s decision to target $10 billion or more signals confidence in its ability to capitalize on a range of investment opportunities across various sectors, including technology, healthcare, consumer goods, and real estate.

Asia has become an increasingly vital part of Blackstone’s global strategy, with the firm steadily building its presence across the continent. Over the past several years, Blackstone has poured resources into expanding its portfolio in Asian markets, with particular emphasis on acquiring and managing assets in Japan and India. Japan, in particular, has emerged as a focal point for the firm, with Blackstone making significant moves in the country’s real estate and corporate sectors.

India, meanwhile, continues to draw attention from private equity players due to its fast-growing economy and the increasing prominence of its tech and startup ecosystem. Blackstone’s latest fund is expected to allocate a substantial portion of its resources to investments in Indian companies, where the firm has already established a solid presence through earlier deals. The firm’s expanding footprint in India mirrors its global strategy of targeting high-growth, scalable businesses that can offer long-term returns.

Blackstone’s decision to pursue such a large fund also highlights the growing appetite for private equity in Asia, where institutional investors are seeking higher returns in the face of ongoing global economic uncertainties. With interest rates rising in Western markets and concerns over inflation, investors are increasingly looking toward Asia as a source of steady, long-term growth. Blackstone’s expertise in asset management, coupled with its deep knowledge of the region, positions it well to attract capital from both existing and new investors.

The fund comes at a time when private equity firms are witnessing increasing competition in Asia, with several global players such as KKR, Carlyle, and Bain Capital also raising significant amounts of capital to deploy in the region. The race for assets in markets like Japan, China, and Southeast Asia has intensified in recent years, as firms vie for control of lucrative businesses poised for growth amid the region’s continued economic transformation.

Despite the competition, Blackstone remains one of the largest and most influential players in the private equity space, with a long track record of successful investments in Asia. The firm has leveraged its size and global reach to secure deals that have delivered significant returns for its investors, and the latest fund is expected to follow a similar strategy, focusing on buyouts, growth equity, and strategic investments in promising sectors.

As Blackstone moves forward with its fundraising efforts, the firm is likely to benefit from its strong reputation among institutional investors, particularly those looking for exposure to Asian markets. The firm’s past performance in the region, combined with its ability to manage large-scale investments across multiple industries, is expected to attract substantial interest from investors seeking to diversify their portfolios with high-quality assets.

Blackstone’s latest Asia fund is expected to play a crucial role in the firm’s broader global strategy, which has increasingly focused on expanding its presence in fast-growing economies. With Asia playing an ever-larger role in the global economy, Blackstone’s commitment to the region signals its recognition of the long-term potential of these markets, as well as its intention to remain a dominant force in the world of private equity.

In Japan, Blackstone has made headlines with several high-profile acquisitions, including the purchase of real estate and logistics assets. The firm’s interest in Japan reflects a broader trend among global investors, who see the country’s corporate sector as ripe for restructuring and consolidation, providing opportunities for buyouts and other forms of private equity investment.

The UAE’s telecommunications regulatory authority has initiated a crackdown on telemarketers by suspending the mobile numbers of numerous firms engaged in unsolicited marketing practices. The move aims to protect consumers from persistent spam calls and enhance overall telecommunication standards in the region. The Telecommunication and Digital Government Regulatory Authority (TDRA) reported that it has imposed significant fines on multiple entities for violating the established regulations governing telemarketing operations.

This proactive stance by the TDRA aligns with the government’s commitment to ensure a secure and pleasant communication environment for its residents. The authority has been increasingly vigilant against unwanted marketing calls, which have been a growing concern for consumers. The actions taken underscore the TDRA’s dedication to curbing intrusive marketing practices and fostering a more user-friendly telecommunications landscape.

The TDRA’s investigations revealed that many telemarketers had not obtained the necessary permissions to initiate marketing campaigns via phone calls, violating the established legal frameworks. The regulatory authority emphasized that all telemarketing activities must be conducted with the explicit consent of consumers and in accordance with the regulations outlined in the Telecommunications Law. This includes obtaining prior consent before contacting potential customers and providing an option for them to opt out of future communications.

As part of its enforcement measures, the TDRA has begun issuing penalties to non-compliant telemarketers. These fines are intended to deter future violations and ensure adherence to the regulations. By enforcing strict compliance, the TDRA aims to enhance consumer protection and uphold the integrity of the telecommunications industry.

The crackdown comes amid growing complaints from consumers about aggressive telemarketing tactics that have led to a significant rise in spam calls. Many residents have voiced their frustration over receiving unsolicited calls, prompting the TDRA to act decisively. The authority has encouraged consumers to report any unwanted calls, providing a dedicated platform for them to register their grievances. This initiative not only empowers consumers but also helps the TDRA identify persistent offenders and take appropriate action.

In addition to suspending mobile numbers, the TDRA is actively collaborating with telecommunications providers to develop more effective solutions to combat telemarketing abuses. These efforts include enhancing caller identification systems and implementing stricter controls on marketing permissions. The authority aims to create a robust framework that protects consumers from unwanted marketing communications while allowing legitimate businesses to operate within the legal parameters.

Emerging technologies are also playing a crucial role in addressing telemarketing issues. The TDRA is exploring innovative solutions, such as machine learning algorithms and artificial intelligence, to analyze call patterns and identify potential spam calls proactively. By leveraging these technologies, the regulatory body can enhance its monitoring capabilities and streamline the enforcement process against violators.

Industry experts have lauded the TDRA’s decisive actions, emphasizing the importance of establishing clear regulations in an era where digital marketing is increasingly prevalent. The push for stricter regulations reflects the growing recognition of consumer rights and the need to create a fair marketplace for both businesses and consumers. Additionally, it highlights the ongoing challenges faced by regulatory bodies in keeping pace with evolving marketing practices.

The UAE’s telecommunication market has witnessed rapid growth, driven by advancements in technology and an expanding digital landscape. However, this growth has also given rise to challenges, particularly in the realm of consumer privacy and unsolicited marketing. The TDRA’s recent actions serve as a critical reminder of the need for regulatory oversight to ensure that the rights of consumers are protected.

As the TDRA continues to address telemarketing violations, businesses operating within the telecommunications sector are urged to comply with regulations and respect consumer preferences. Organizations must prioritize transparency in their marketing practices and foster trust with their customers. By adopting ethical marketing strategies, companies can not only avoid penalties but also enhance their brand reputation and customer loyalty.

Standard & Poor’s has downgraded Israel’s credit rating from A+ to A, primarily citing increased security risks stemming from escalating tensions in the region. The decision reflects the rating agency’s assessment that the current geopolitical climate may hinder Israel’s economic stability and growth prospects.

The S&P report highlighted that the downgrade is attributed to the intensification of military conflicts, particularly involving militant groups in Gaza and Hezbollah in Lebanon. This situation has led to rising security expenditures and concerns over potential disruptions to the economy. Analysts argue that the ongoing conflict could deter foreign investment, impact tourism, and affect the overall economic environment.

Israel’s military actions, particularly in response to rocket fire from Gaza, have drawn international scrutiny. The cycle of violence and retaliatory strikes has strained relationships with neighboring countries and raised fears of a broader regional conflict. The deteriorating security situation has also sparked protests within Israel, with citizens demanding a reevaluation of the government’s military strategy and its implications for daily life.

The economic implications of the downgrade are significant. Israel’s economy has shown resilience in recent years, bolstered by technological advancements and a robust startup ecosystem. However, analysts fear that the heightened security risks could stifle this growth, particularly as the nation grapples with the dual challenges of military expenditures and maintaining investor confidence.

The downgrading comes at a time when Israel’s economy is experiencing inflationary pressures, further complicating the financial landscape. Rising living costs, coupled with increased defense spending, pose challenges to fiscal stability. Policymakers may need to implement measures to counteract these pressures, potentially involving budget reallocations and strategic economic initiatives.

Economists have pointed out that the current security environment may necessitate increased dialogue and diplomatic efforts aimed at stabilizing the region. There is a growing consensus among experts that sustainable peace initiatives could alleviate some of the financial burdens linked to security expenditures. Strengthening diplomatic relations with neighboring states may be essential for fostering an environment conducive to economic growth and stability.

Reactions to the downgrade have varied among local political leaders. While some have criticized the government’s handling of security issues, others argue that the rating reflects broader geopolitical realities that are beyond Israel’s immediate control. As the nation navigates these complex dynamics, the government’s approach to national security and foreign relations will likely play a pivotal role in shaping future economic trajectories.

In response to the downgrade, Israeli Finance Minister Bezalel Smotrich emphasized the importance of a balanced approach to security and economic growth. He stated that maintaining robust defense capabilities is crucial while also recognizing the need for economic resilience. Smotrich’s comments indicate an understanding that both aspects are interlinked, and a sustainable approach will be necessary to bolster investor confidence.

The impact of the downgrade on Israel’s bond market has been immediate, with yields rising as investors reassess risk levels. The move by S&P may prompt other rating agencies to reevaluate their assessments, further complicating Israel’s financial standing in international markets. Observers are closely monitoring how the government responds to these challenges and whether it can implement effective policies to stabilize the economy amidst security concerns.

As Israel grapples with these challenges, key sectors such as technology and tourism are being scrutinized for their resilience. The technology sector, a significant driver of economic growth, may face increased pressure if security concerns impact investment flows. Conversely, the tourism industry, already affected by the pandemic, may struggle to recover fully without improved security conditions.

Investors and analysts are also concerned about the long-term implications of the downgrade on Israel’s geopolitical strategy. The current environment necessitates a recalibration of priorities, with potential shifts in foreign investment patterns and trade relationships. Maintaining a favorable business climate while addressing security challenges will require careful policy considerations.

International reactions to the S&P downgrade have been mixed, with some analysts suggesting that it underscores the need for global stakeholders to engage more actively in peace initiatives in the region. Collaborative efforts to address underlying tensions may not only enhance regional stability but also contribute positively to Israel’s economic outlook.

A significant investment is on the horizon as an Omani consortium prepares to establish a data center in Egypt’s Suez Canal Economic Zone, with an allocation of $450 million earmarked for the project. This initiative is part of Egypt’s broader strategy to transform the Suez Canal region into a technological and logistical hub, enhancing its role in global trade and digital services.

The investment is spearheaded by the Oman Information Technology Company (OITC) and several local partners. This collaboration marks a critical step in fostering economic ties between Oman and Egypt, with both nations recognizing the potential of digital infrastructure in driving economic growth. The data center is expected to support the burgeoning demand for cloud services and digital storage, driven by an increasingly digitized global economy.

The announcement of the data center project aligns with Egypt’s strategic plan to attract foreign direct investment and bolster its technological capabilities. The Suez Canal Economic Zone has been pivotal in this vision, with the Egyptian government actively promoting investment opportunities in sectors such as logistics, manufacturing, and technology. The zone’s geographical advantage, situated at the crossroads of major trade routes, offers unparalleled access to international markets.

By establishing a state-of-the-art data center in this zone, the Omani consortium aims to enhance digital connectivity not only within Egypt but also across the broader Middle East and North Africa (MENA) region. The center will provide essential services such as cloud computing, data storage, and disaster recovery solutions, catering to both local and international clients.

The data center project is expected to generate significant employment opportunities for the local workforce. With the ongoing investment in education and training programs in Egypt, there is a concerted effort to equip young professionals with the necessary skills to thrive in the digital economy. The collaboration between OITC and local partners is likely to enhance knowledge transfer and foster innovation within the Egyptian tech landscape.

This investment comes at a time when global data center demand is surging, driven by trends such as the rise of e-commerce, the proliferation of the Internet of Things (IoT), and the increasing reliance on digital solutions across various sectors. As businesses and governments prioritize digital transformation, the need for robust and secure data infrastructure has become paramount.

The Suez Canal Economic Zone’s strategic position allows for efficient connectivity to Europe, Asia, and Africa, making it an attractive location for data center operations. This development not only supports Egypt’s ambitions to become a regional technology hub but also enhances its competitiveness in the global market.

The partnership is set to leverage advancements in renewable energy, aligning with global sustainability trends. As data centers are known for their high energy consumption, the integration of renewable energy sources will be pivotal in minimizing the environmental impact of this project. The Omani consortium is expected to explore partnerships with renewable energy providers in Egypt to power the data center sustainably.

Egypt’s government has been proactive in creating a favorable environment for foreign investments, implementing reforms aimed at improving the business climate. The country’s economic stability, coupled with its young and tech-savvy population, positions it as a viable destination for tech investments. The collaboration between OITC and Egyptian partners reflects a growing trend among Gulf countries to diversify their investments beyond traditional sectors, focusing instead on technology and digital services.

This project is also anticipated to strengthen Egypt’s position in the regional tech ecosystem, attracting additional investments and partnerships from global tech giants. With the establishment of the data center, Egypt aims to position itself as a competitive player in the MENA tech landscape, potentially drawing in international businesses looking for reliable digital infrastructure.

As the project progresses, it will be essential for stakeholders to ensure that the data center adheres to international standards for security and data privacy. The rise in cyber threats has made data protection a critical concern for businesses and consumers alike. Establishing robust cybersecurity measures will be crucial to gain the trust of clients and stakeholders.

Growing concerns surrounding geopolitical instability in the Middle East are contributing to heightened volatility in the oil markets, as traders anticipate further price increases. Recent analyses indicate that the tensions between various regional players and broader global dynamics are significantly influencing supply concerns, leading to increased buying activity in oil options. This is particularly evident as major crude benchmarks, including Brent crude and West Texas Intermediate (WTI), have seen notable fluctuations driven by investor sentiment and strategic positioning.

Market data reveals a surge in options trading, suggesting that traders are preparing for potential price movements. Open interest in call options, which give the buyer the right to purchase oil at a predetermined price, has risen sharply. This indicates that market participants expect prices to climb, driven by fears of supply disruptions due to geopolitical unrest, particularly in key oil-producing countries such as Saudi Arabia, Iran, and Iraq. Analysts suggest that the current landscape is reminiscent of past crises, wherein escalating tensions have historically led to significant price spikes.

As oil prices approach the $100 per barrel mark, analysts warn that sustained increases could have broader economic implications. The International Energy Agency (IEA) has projected a potential supply shortfall if geopolitical tensions escalate, particularly with ongoing conflicts in Ukraine and regional disruptions in the Middle East. In this context, market experts emphasize the importance of monitoring geopolitical developments closely, as these factors will be critical in shaping oil price trajectories in the coming months.

The dynamics of oil trading have shifted, with many investors now viewing geopolitical events as pivotal catalysts for price changes. The strategic importance of the Middle East, often referred to as the world’s energy hub, cannot be overstated. The region accounts for a significant portion of global oil supply, and any disruptions can lead to immediate and substantial price reactions in the market.

In light of these developments, the oil market is exhibiting signs of increased speculation. Hedge funds and other large investors have ramped up their positions in oil futures and options, further reflecting the bullish sentiment permeating the market. This trend has been particularly pronounced in the context of the ongoing discussions regarding production cuts by the Organization of the Petroleum Exporting Countries (OPEC) and its allies. OPEC’s decisions will play a crucial role in determining supply levels and influencing price stability.

Saudi Arabia, a leading member of OPEC, has signaled its willingness to adjust production levels in response to market dynamics. The kingdom’s recent commitments to reducing output in order to stabilize prices have fueled discussions regarding potential collaborative efforts among OPEC members to manage supply effectively. This strategy aims to counterbalance the impact of external geopolitical risks and market volatility.

Iran’s continued efforts to revitalize its oil production in the wake of sanctions further complicates the scenario. The Iranian oil sector is poised for growth, but any increase in output is contingent upon the delicate diplomatic landscape. Investors are acutely aware that shifts in U.S. policy towards Iran can have immediate repercussions for oil supply and pricing, leading to a cautious approach in trading activities.

Market sentiment is also influenced by macroeconomic factors, including inflation and interest rates. Recent data suggest that rising inflationary pressures are leading to increased uncertainty regarding economic growth, which could, in turn, impact oil demand. Investors are weighing the potential for a slowdown in global economic activity against the backdrop of supply-side constraints. This balancing act adds another layer of complexity to trading strategies.

Analysts are observing emerging trends in the energy sector, particularly the transition towards renewable energy sources. As nations grapple with climate change initiatives, the demand for traditional fossil fuels is being challenged. However, in the short term, oil remains a critical component of the global energy mix, especially amid geopolitical uncertainties that necessitate a reliable energy supply.

The current landscape underscores the importance of strategic foresight for traders and investors. Understanding the interconnectedness of geopolitical developments, production decisions, and market sentiment will be essential in navigating the complexities of oil trading. Traders are increasingly incorporating a broader range of indicators and data points into their analyses, reflecting the dynamic nature of the oil market.

Marex Group, a prominent global financial services firm, has announced its decision to acquire Aarna Capital, a leading asset management company based in Abu Dhabi. This acquisition marks a significant move in the financial landscape of the region, enhancing Marex’s operational capacity and broadening its investment portfolio. The deal is seen as a strategic step for Marex to expand its footprint in the Middle East and take advantage of the growing investment opportunities in the area.

Established in 2020, Aarna Capital has quickly established itself as a key player in asset management, focusing on providing innovative solutions tailored to the evolving needs of its clients. The firm specializes in various investment strategies, including private equity, real estate, and alternative investments. With a strong local presence and a deep understanding of the regional market dynamics, Aarna has attracted a diverse client base that includes institutional investors, family offices, and high-net-worth individuals.

Marex Group’s acquisition of Aarna Capital is expected to create synergies that will benefit both firms. Aarna’s expertise in the regional market will complement Marex’s existing capabilities, particularly in derivatives and commodities trading. This strategic alignment aims to enhance Marex’s service offerings while providing Aarna’s clients with access to a broader range of financial products and expertise.

The deal is anticipated to close within the next few months, pending regulatory approvals. Following the acquisition, Aarna will continue to operate under its brand while integrating Marex’s operational strengths. This dual-brand strategy is intended to retain Aarna’s established client relationships while leveraging Marex’s global reach and resources.

Marex Group’s Chief Executive Officer, Ian Lowitt, expressed confidence in the acquisition, highlighting Aarna’s impressive track record and local market knowledge. He noted that this acquisition is a testament to Marex’s commitment to growing its presence in key financial hubs around the world. The UAE’s strategic location, robust regulatory framework, and rapidly growing economy make it an attractive market for financial services firms.

Industry analysts view this acquisition as a reflection of the increasing competition in the asset management sector, particularly in the Middle East. As more global financial institutions look to establish a presence in the region, strategic partnerships and acquisitions are becoming essential for growth. Marex Group’s move to acquire Aarna Capital underscores the importance of localized expertise in navigating the complexities of regional markets.

The deal also comes at a time when the UAE is positioning itself as a global financial center, attracting investments from various sectors. The government’s initiatives to diversify the economy and foster a business-friendly environment have led to a surge in foreign direct investment. As a result, firms like Marex Group are keen to capitalize on this growth potential through strategic acquisitions.

Investors are optimistic about the potential for enhanced performance resulting from this acquisition. The combined strengths of Marex and Aarna are expected to deliver innovative investment solutions that cater to the unique needs of clients in the region. This collaboration aims to enhance operational efficiencies, enabling both firms to compete more effectively against larger global players.

Marex Group, headquartered in London, has been actively expanding its global operations over the past few years. This acquisition of Aarna Capital aligns with its strategy to enhance its service offerings and strengthen its position in the financial markets. With a workforce that spans multiple continents and a diverse range of financial products, Marex is well-equipped to navigate the complexities of the global financial landscape.

Aarna Capital’s founders, who will remain involved post-acquisition, emphasized their excitement about joining Marex Group. They believe that the partnership will unlock new growth opportunities and enable them to serve their clients with an expanded suite of financial products. The founders expressed confidence that the collaboration will further enhance Aarna’s reputation as a leading asset manager in the region.

As the financial sector in the UAE continues to evolve, the acquisition of Aarna Capital by Marex Group represents a strategic move that aligns with broader industry trends. The need for localized expertise, innovative solutions, and strong client relationships has never been more critical. This acquisition positions both firms to leverage their strengths and capitalize on the burgeoning opportunities within the asset management space.

Qatar is set to witness a transformative shift in its telecom sector as the Qatar Investment Authority (QIA) plans to merge two key entities in a move that could reshape the region’s digital landscape. The decision to unite Ooredoo, the country’s largest telecommunications company, with Vodafone Qatar, signals a strategic consolidation aimed at creating a formidable player in the Middle Eastern market, positioning Qatar as a leader in digital infrastructure development.

The merger is expected to streamline operations and enhance competitiveness in the global arena, as QIA looks to capitalize on the evolving demands for faster connectivity, robust data networks, and cutting-edge technology. Analysts have pointed out that combining the assets and expertise of both companies could significantly boost Qatar’s telecom capabilities, paving the way for investments in 5G networks, cloud computing, and smart city initiatives.

The global telecommunications industry has been undergoing rapid transformations, with digital infrastructure becoming a cornerstone for future economic growth. Qatar’s move is seen as a bold step toward aligning with these global trends, as the country seeks to strengthen its position as a regional hub for technological innovation. The timing of this merger is particularly significant, given the growing importance of 5G technology and the increasing reliance on digital platforms for economic and social activities.

Industry insiders have described the merger as a logical progression for Qatar’s telecom landscape, which has been characterized by rapid growth and increasing competition. Ooredoo, with its vast market share and extensive network across the Middle East, North Africa, and Southeast Asia, is a critical player in the region’s telecommunications infrastructure. Vodafone Qatar, while smaller in scale, brings international expertise and brand recognition, complementing Ooredoo’s operations. The merger is expected to create synergies that will enable the combined entity to compete more effectively, not only regionally but also on a global scale.

QIA’s involvement underscores the importance of the telecom sector in the country’s broader economic strategy. As one of the world’s largest sovereign wealth funds, QIA has been actively investing in infrastructure, real estate, and technology, with a focus on long-term growth and diversification of Qatar’s economy. The telecom sector has become a priority for QIA, given its critical role in supporting Qatar’s Vision 2030, a national strategy aimed at transforming the country into a knowledge-based economy. The merger of Ooredoo and Vodafone Qatar is expected to play a crucial role in realizing these ambitions, enabling Qatar to lead the charge in digital transformation across the region.

The newly merged entity is anticipated to leverage the strengths of both companies, combining Ooredoo’s established regional presence and Vodafone’s global expertise. This alignment is expected to not only improve service offerings within Qatar but also extend the reach of its digital infrastructure to international markets. The merger will likely result in enhanced data services, more competitive pricing, and improved customer experience, benefiting both consumers and businesses.

Experts have noted that the consolidation of telecom operators is not unique to Qatar, as many countries have pursued similar strategies to address challenges in the sector, including high capital expenditures and the need for constant innovation. The merger will allow the combined entity to reduce costs, optimize resources, and invest in new technologies that are essential for future growth. The increased scale of operations will enable the company to negotiate better terms with equipment providers and technology partners, providing a competitive edge in the rapidly evolving telecom landscape.

Qatar’s telecommunications sector has grown substantially over the past decade, driven by rising demand for mobile services, internet access, and digital content. The country boasts some of the highest mobile penetration rates in the world, and its government has made significant investments in building world-class digital infrastructure. The merger will further strengthen these efforts by creating a telecom giant that is better positioned to meet the growing demand for high-speed internet and data services, particularly as businesses and consumers increasingly rely on digital platforms for communication, entertainment, and commerce.

The merger aligns with global trends toward the digitalization of economies, as countries around the world race to develop advanced telecommunications networks to support emerging technologies such as artificial intelligence, the Internet of Things (IoT), and autonomous vehicles. By consolidating its telecom assets, Qatar aims to position itself as a leader in these fields, attracting foreign investment and fostering innovation.

G42, a prominent technology holding group based in Abu Dhabi, has reportedly decided to halt a significant investment partnership with Ray Dalio’s Bridgewater Associates, which was aimed at forming a $1 billion venture. The move comes amid a backdrop of changing dynamics in the investment landscape and economic uncertainties. G42, known for its focus on artificial intelligence and cloud computing, was expected to leverage Bridgewater’s expertise in managing investments but has now opted to refocus its strategic priorities.

Sources indicate that the partnership was intended to integrate G42’s technological prowess with Bridgewater’s investment acumen, particularly in AI-driven financial solutions. However, ongoing evaluations of market conditions, regulatory challenges, and internal assessments may have influenced the decision to shelve the project.

This decision aligns with a broader trend of investment firms reassessing their strategies in light of fluctuating economic indicators and evolving market demands. G42 had previously engaged in various high-profile partnerships, including a notable collaboration with Microsoft, which infused $1.5 billion into the company to enhance AI development and infrastructure.

The cancellation of the investment venture reflects not only G42’s shifting focus but also highlights the challenges faced by firms in the technology and finance sectors as they navigate complex market environments. As technology firms increasingly prioritize responsible AI development and compliance with international regulations, strategic pivots such as this may become more common.

Peng Xiao, G42’s Group Chief Executive Officer, has emphasized the importance of aligning with partners who share the company’s vision of responsible innovation. This includes commitments to enhance security and compliance frameworks within their projects. The decision to pause the collaboration with Bridgewater could signal G42’s intent to prioritize these principles in future endeavors.

Aiming to enhance transparency and streamline access to economic data, the UAE’s Ministry of Economy has launched the National Economic Registry (NER). The initiative is set to serve as a centralized platform, providing comprehensive information on companies and economic activities across the country, supporting businesses, investors, and government entities in their decision-making processes. The move underscores the UAE’s commitment to fostering a more open and transparent business environment, vital to attracting foreign investments and promoting sustainable growth.

The NER is designed to consolidate data from various economic departments and authorities, enabling users to access up-to-date and accurate information about companies operating within the UAE. This includes company registration details, ownership structures, legal statuses, and economic licenses. By facilitating the quick and reliable retrieval of business information, the platform is expected to contribute significantly to improving the ease of doing business in the country. The government’s efforts to enhance regulatory transparency are aligned with its broader strategy to position the UAE as a global business hub.

In addition to promoting transparency, the NER aims to combat financial crime, including money laundering and terrorist financing. By providing government agencies with access to consolidated economic data, the registry will support efforts to monitor suspicious financial activities and ensure compliance with international financial regulations. Authorities view the NER as a critical tool in maintaining the UAE’s standing as a responsible global financial player, while also ensuring that businesses adhere to stringent compliance standards.

This move is part of the UAE’s broader economic reform agenda, which has seen the country implementing several initiatives aimed at enhancing competitiveness and facilitating business growth. The NER is expected to complement existing reforms, such as the introduction of new foreign investment laws and changes to the country’s commercial and corporate governance frameworks. These reforms are part of the UAE’s broader vision to diversify its economy away from oil dependency, creating a more resilient and sustainable economic model.

Business leaders in the UAE have expressed optimism about the NER, noting its potential to improve operational efficiency and foster greater trust in the country’s regulatory framework. The centralized nature of the platform is seen as a significant improvement over previous systems, which required businesses and investors to engage with multiple entities to gather necessary information. By simplifying access to economic data, the NER is expected to reduce bureaucratic hurdles and enhance the overall business environment, making the UAE a more attractive destination for both local and foreign investors.

The UAE’s Ministry of Economy has emphasized the user-friendly nature of the NER, ensuring that the platform is easily accessible to businesses of all sizes. Whether small enterprises or large multinational corporations, companies will benefit from the streamlined processes offered by the platform. Additionally, the NER is expected to aid start-ups and entrepreneurs, providing them with crucial insights into the economic landscape, helping them navigate the complexities of establishing and growing businesses in the UAE.

This initiative also aligns with the UAE’s digital transformation efforts, which have accelerated across various sectors in recent years. The development of the NER reflects the government’s commitment to leveraging technology to enhance administrative efficiency and support the country’s economic growth. The digitalization of business information is expected to reduce paperwork, improve accuracy, and allow for real-time updates, ensuring that the economic data available on the platform remains current and reliable.

Experts note that the success of the NER will depend on the seamless integration of data from different economic departments and authorities across the UAE. The Ministry of Economy has worked closely with local authorities to ensure that the platform includes comprehensive and accurate data, with mechanisms in place to update the information regularly. This collaboration between federal and local entities is seen as a crucial factor in the long-term success of the registry.

The launch of the NER comes at a time when global economic conditions remain volatile, underscoring the importance of transparency and trust in attracting foreign investments. Countries around the world are increasingly focusing on improving their business environments to stay competitive in a post-pandemic global economy. In this context, the UAE’s efforts to bolster transparency through the NER are viewed as a proactive step towards reinforcing its position as a leading global business destination.

The NER is expected to support the UAE’s ambitions in international trade, providing foreign companies with reliable data that can help them assess business opportunities in the country. By offering greater visibility into the UAE’s economic landscape, the registry will likely strengthen international business partnerships and trade relations, further integrating the UAE into the global economy.

Oil-producing nations in the OPEC+ alliance have decided to maintain the current output policy following a key meeting. The gathering of ministers, which occurred as global energy markets continue to experience volatility, focused on compliance with production cuts and compensatory measures for countries that have exceeded their allocated quotas. As tensions persist over global supply and demand dynamics, this decision underscores OPEC+’s cautious approach in navigating the uncertain landscape.

The meeting, involving some of the world’s largest oil producers, was closely watched by analysts and industry leaders. Observers had anticipated possible adjustments to production levels, but the alliance chose to keep its policy steady for the time being. A source close to the talks confirmed the decision, emphasizing the group’s intent to maintain stability amid unpredictable economic conditions. OPEC+ has long been the primary driver behind oil supply strategies, and its decisions significantly impact global oil prices.

Attention was also directed at countries that have been overproducing relative to their targets. The meeting delved into how these nations might adjust their production in the coming months to align with the overall quotas set by the group. According to one of the sources within OPEC+, ministers discussed altering the schedules for compensating the excess oil production. While compliance remains a key issue, the group’s commitment to ensuring market equilibrium is evident through its continued discussions on corrective actions for overproducers.

OPEC+ includes the 13-member Organization of the Petroleum Exporting Countries (OPEC) along with other major oil producers, including Russia, forming an extended alliance that has managed global oil production since 2016. The group’s coordinated efforts in limiting production have played a critical role in managing global oil supply, especially after demand shocks like the COVID-19 pandemic. OPEC+ agreements, including the output cuts initiated in response to these shocks, have helped stabilize the market, albeit with ongoing challenges.

The current production cuts are part of a broader strategy adopted by OPEC+ to counterbalance the global oil supply. This strategy was designed to address the fluctuating demand patterns caused by economic slowdowns, geopolitical conflicts, and environmental concerns. Although many expected the group to consider tightening production further, the decision to maintain the status quo suggests that ministers are awaiting clearer market signals before making significant adjustments.

Concerns over compliance have surfaced repeatedly within the OPEC+ framework, particularly regarding the member nations that have consistently exceeded their production targets. The alliance had previously implemented a compensation mechanism that allows such countries to compensate for their overproduction by reducing future outputs. Discussions during the latest meeting reiterated the importance of this mechanism, with proposals to recalibrate the compensation schedules for non-compliant members gaining traction.

Market analysts are closely evaluating how these compensation schedules might influence oil prices in the coming months. For many overproducing countries, the challenge lies in balancing domestic energy demands with international commitments. The talks have underscored the need for greater transparency and enforcement within the OPEC+ framework, as stricter compliance will be crucial for the alliance’s long-term credibility and effectiveness.

The broader geopolitical context remains an important factor in OPEC+’s decision-making. Ongoing concerns over global inflation, coupled with fears of economic recessions in key markets, continue to shape the group’s cautious approach. Energy prices have become a focal point of debate in several regions, with governments under pressure to address rising costs while maintaining economic growth. OPEC+, mindful of these dynamics, is likely to continue adjusting its strategies in response to global macroeconomic shifts.

Despite the current output freeze, many industry experts believe that OPEC+ may consider changing its production policies in future meetings, especially if market conditions warrant it. The delicate balance between supply and demand remains a persistent challenge for oil producers, who must navigate not only the economics of energy but also the geopolitical pressures associated with oil dependency.

The global energy landscape continues to evolve, driven by factors such as the transition to renewable energy, geopolitical tensions, and the demand recovery in major economies. OPEC+ is increasingly viewed not just as a traditional oil cartel but as a central player in global energy governance. This meeting further highlights the alliance’s critical role in shaping the future of oil production and pricing.

OPEC+’s production strategies are also being influenced by longer-term shifts in the global energy mix. As the world gradually pivots toward more sustainable energy sources, fossil fuel producers face mounting pressure to diversify their portfolios while continuing to meet the immediate energy needs of a growing global population. For many OPEC+ members, the dual challenge of meeting these short-term and long-term goals will define the future of oil production policy.

Petronas, the Malaysian oil and gas company, has achieved a significant milestone by securing an onshore concession license in Abu Dhabi. This development signals a noteworthy expansion for Petronas in the Middle East, positioning the company for increased engagement in the region’s burgeoning energy sector.

The agreement grants Petronas the right to explore, develop, and produce hydrocarbons in the concession area, an endeavor that aligns with the company’s strategic focus on enhancing its international upstream portfolio. The concession spans a 30-year term, during which Petronas aims to leverage its technological expertise and innovative solutions to optimize production while adhering to the highest environmental standards.

Abu Dhabi’s hydrocarbon-rich landscape has long attracted major oil players due to its substantial reserves and favorable investment climate. The emirate is keen on diversifying its economy and enhancing energy sustainability, and Petronas’s involvement is anticipated to contribute positively to these objectives. This concession license aligns with Abu Dhabi’s broader strategy to attract foreign investment while ensuring a sustainable energy future.

The licensing agreement underscores the UAE’s commitment to maintaining its status as a pivotal player in the global energy market. It also reflects Petronas’s strategic intention to capitalize on growth opportunities outside its home market, thereby enhancing its global footprint. The partnership with the Abu Dhabi National Oil Company (ADNOC) is expected to facilitate knowledge transfer and collaboration, fostering innovation within the energy sector.

ADNOC has actively sought international partners to strengthen its upstream capabilities, and Petronas’s involvement is seen as a testament to ADNOC’s strategy of forging alliances with leading global energy firms. The collaboration will focus on advanced technologies, including digitalization and artificial intelligence, to enhance exploration and production efficiencies.

Petronas has been expanding its international operations over the past few years, with significant investments in various countries, including Canada, Brazil, and Mozambique. The company aims to maintain a balanced portfolio while exploring opportunities in renewable energy, aligning with global shifts towards sustainable practices. The Abu Dhabi concession marks a continuation of Petronas’s efforts to adapt to evolving market dynamics and shifting energy demands.

Industry analysts view this agreement as a positive step for both Petronas and ADNOC, as it creates synergies that can drive value creation. The partnership is expected to leverage ADNOC’s extensive experience in the region along with Petronas’s technical capabilities, thereby enhancing operational efficiencies. With the global energy landscape undergoing significant transformations, this collaboration is poised to bolster the resilience and competitiveness of both entities.

The concession also comes at a time when oil prices are experiencing volatility, prompting many companies to reassess their strategies and investments. By securing this license, Petronas is positioning itself to navigate these fluctuations effectively. The company’s focus on innovation and sustainability is anticipated to enhance its adaptability to market challenges, ensuring its long-term growth prospects.

As the energy transition accelerates, the partnership between Petronas and ADNOC is likely to explore opportunities beyond traditional oil and gas. The companies may jointly investigate initiatives in carbon capture and storage, as well as investments in renewable energy projects. This strategic approach is essential for maintaining relevance in a rapidly changing energy landscape.

Both companies are well-positioned to contribute to Abu Dhabi’s goal of achieving net-zero emissions by 2050. The collaboration could lead to groundbreaking advancements in energy efficiency and sustainability practices, setting a benchmark for future partnerships in the region.

While the immediate focus is on hydrocarbon production, the strategic collaboration may pave the way for broader initiatives that align with global sustainability goals. This could include exploring alternative energy sources, enhancing energy efficiency measures, and investing in clean technologies that reduce carbon footprints.

The successful acquisition of the onshore concession license by Petronas not only highlights its commitment to expanding its operational footprint but also underscores the importance of collaboration in achieving energy sustainability. The agreement reflects a shared vision between ADNOC and Petronas to develop innovative solutions that meet the demands of an evolving energy landscape while prioritizing environmental stewardship.

As global energy markets continue to transform, Petronas’s expansion into Abu Dhabi marks a significant development in the region’s oil and gas sector. This venture is expected to enhance both companies’ operational efficiencies, drive technological innovation, and contribute to the sustainable development goals set forth by the UAE. The collaboration serves as a model for future partnerships, illustrating the potential of strategic alliances in navigating the complexities of the energy industry.

The Karl Lagerfeld brand is venturing into the luxury real estate market, announcing ambitious plans to expand its portfolio of branded residences both in the UAE and globally. This move marks a significant shift for the iconic fashion house, which has primarily been associated with haute couture, accessories, and lifestyle products. The expansion aligns with a broader trend in the luxury sector, where fashion brands are increasingly diversifying their offerings to include real estate as a means to enhance their brand presence and engage consumers in new ways.

The announcement comes as part of a collaboration between the Karl Lagerfeld brand and the luxury real estate developer, K. Group, headquartered in Dubai. The partnership aims to develop exclusive residential projects featuring the distinctive design and aesthetic synonymous with Lagerfeld’s legacy. The first of these projects is expected to launch within the next two years in one of Dubai’s upscale neighborhoods, further solidifying the city’s reputation as a global luxury hub.

This strategic expansion into branded residences capitalizes on the growing demand for luxury living spaces that offer personalized experiences, combining opulence with the allure of high fashion. Branded residences have become increasingly popular among affluent buyers seeking unique living experiences that reflect their lifestyle preferences. This trend is particularly pronounced in regions such as the Middle East, where luxury and exclusivity are paramount.

Lagerfeld’s iconic design sensibility, characterized by clean lines, bold colors, and a contemporary aesthetic, will play a central role in shaping the residential projects. Each residence is expected to showcase custom interiors inspired by Lagerfeld’s distinct style, ensuring that residents will experience a unique living environment that embodies the brand’s ethos. The integration of high-quality materials, innovative design features, and cutting-edge technology will further enhance the allure of these properties.

As the luxury real estate market continues to evolve, fashion houses like Karl Lagerfeld are leveraging their brand equity to tap into new revenue streams. This strategy not only enhances brand visibility but also creates a sense of community among residents who share an affinity for the brand. Moreover, the collaboration with K. Group will enable the Karl Lagerfeld brand to benefit from the developer’s extensive market knowledge and expertise in the real estate sector.

The global luxury real estate market is witnessing a surge in interest from high-net-worth individuals seeking investment opportunities that combine lifestyle with financial returns. According to industry analysts, the branded residences market is projected to grow significantly, driven by increasing demand for luxury properties in prime locations. The trend is particularly evident in cities like Dubai, where luxury developments have consistently attracted wealthy investors from around the world.

The partnership between Karl Lagerfeld and K. Group represents a broader trend among luxury brands diversifying their portfolios. Similar ventures have been seen with brands like Versace, Bulgari, and Armani, each establishing their own branded residences in various markets. These projects not only serve as a revenue stream but also deepen the emotional connection between consumers and the brand, fostering loyalty and enhancing the overall brand experience.

The move into branded residences also aligns with the growing consumer preference for experiential luxury, where buyers are increasingly looking for more than just a property. They seek a lifestyle that is intricately woven with the values and aesthetics of the brands they admire. By offering residences that reflect the essence of the Karl Lagerfeld brand, the company is poised to capitalize on this shift in consumer behavior, providing potential buyers with a unique living experience that transcends traditional luxury.

With the Karl Lagerfeld brand’s expansion into branded residences, the fashion house is set to redefine the luxury living experience. The move underscores the evolving landscape of the luxury market, where boundaries between fashion, lifestyle, and real estate continue to blur. As the brand prepares to unveil its first residential projects, anticipation is building among potential buyers eager to experience the unique fusion of high fashion and luxury living.

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA