Articles written by
arabian post staff

Bitwise has launched a new exchange-traded product on Deutsche Börse Xetra under the ticker AVNB, offering regulated exposure to Avalanche’s native token AVAX along with integrated staking rewards.

The ETP is physically backed and domiciled in Germany, aiming to deliver price-tracking performance plus yield, while eliminating the need for investors to manage staking infrastructure or custody themselves. Staking rewards are credited daily and automatically reinvested. The product references the “CF AVAX Staked Return Index” as its benchmark.

Bitwise positions the AVAX staking ETP as part of its growing European suite of institutional crypto products. Earlier offerings in its staking line-up include Ethereum and other digital assets. The firm emphasizes that this launch addresses demand from institutional and professional investors seeking yield-bearing digital asset exposure within regulated frameworks.

Under the terms, the ETP carries a total expense ratio of 0.85 per cent annually. Bitwise retains roughly one-third of the staking rewards generated, as a staking service fee to cover operational costs including validator services and infrastructure. The remainder is passed to investors, net of protocol fees and slashing risk.

Bradley Duke, Head of Europe at Bitwise, stated that AVNB “opens the door for investors to access price movements in AVAX coupled with staking rewards through an exchange-traded total return product.” He noted that its regulated structure and transparency aim to bridge the traditional capital markets with crypto infrastructure. John Wu, President of Ava Labs, welcomed the development, saying that offering access through established market systems expands participation in Avalanche’s ecosystem.

Avalanche has gained traction as a scalable, energy-efficient layer-1 blockchain capable of supporting subnetworks tailored for compliance, governance and performance. Its adoption extends across tokenisation, decentralised finance, gaming and payment systems. The ability to stake AVAX is an integral feature of the network’s consensus, making yield products a natural extension for investors.

Oil prices are sliding as traders cite mounting unsold Middle Eastern crude and weakening demand from key importers. This shift raises prospects of a global oversupply even as OPEC+ debates its next policy move.

Estimates from trading houses place unsold crude cargoes for November loading in the Middle East between 6 million and 12 million barrels. These volumes represent a departure from usual patterns where discount-seeking buyers quickly absorb surplus cargoes. Market participants point to a combination of subdued Chinese demand and logistical bottlenecks as contributing factors.

Spot premiums on benchmark grades such as Oman, Dubai and Murban have plunged below $2 per barrel, reflecting the discounts sellers are forced to offer to entice buyers. One trading analyst noted that the drop in premiums signals heightened desperation amid a buyer’s market for Middle Eastern crude.

China, a traditional backstop for surplus exports, is showing signs of pulling back. In May, China recorded a crude surplus of 1.4 million barrels per day—indicating that imports significantly outpaced refinery throughput. That accumulated surplus suggests refiners are prioritising inventory building over active processing, perhaps in anticipation of future market volatility.

Iran adds another layer of complexity. Tanker-tracking firms estimate that between 23 million and 33 million barrels of Iranian crude are currently held in floating storage. While Iran’s oil minister has denied any unsold inventory, satellite and maritime data paint a different picture. Analysts say the discrepancy reflects the country’s use of ship-to-ship transfers and “ghost fleet” operations to obscure the origin and movement of crude, especially in shipments headed for China.

These movements coincide with a broader recalibration in OPEC+ strategy. Some member states, notably Iraq, have increased destination-free exports, signalling an intent to saturate markets and regain influence with trading partners. Iraq’s shipment of Basrah Medium crude is projected to rise significantly in the coming month, following a period in which pledged output increases by coalition members have lagged deliveries.

Many analysts believe that OPEC+ will proceed cautiously in its production decisions. A sudden output cut might stoke accusations of market manipulation, while continued supply expansion could exacerbate falling price trends. Ahead of its upcoming meeting, the group faces the dilemma of balancing the need to safeguard revenue against the risk of triggering a price collapse.

Meanwhile, U. S. domestic supply is contributing to uncertainty. The Energy Information Administration reports that U. S. output has strengthened marginally, offset by curtailed imports of Russian crude under tightened sanctions. But some industry observers warn that U. S. production may have peaked. One petroleum engineer pointed to a 12 percent decline in output from October 2024 to June 2025, citing state-level data that may undercut EIA projections.

Oil futures reflect growing anxiety. Brent crude and West Texas Intermediate have posted their steepest weekly drops since June, falling over 8 percent in some benchmarks amid concerns that global inventories will build significantly. Traders increasingly view OPEC’s next move as critical in determining whether markets stabilise or cede ground to excess supply.

In this environment, floating storage becomes a more active tool. The accumulation of oil held offshore is not just a symptom of imbalance but a way to temporally manage supply pressure. Floating oil reserves enable sellers to delay deliveries until market conditions improve—or until buyers return.

Refiners in Asia and Europe are approaching capacity constraints. Some are cutting processing rates or entering maintenance periods, reducing appetite for new crude. Because many surplus cargoes are being offered on destination-free terms, they face competition across regions—and the lack of clear demand is forcing suppliers to lengthen delivery offers or scale back premiums.

If the pricing squeeze deepens, some producers may respond by cutting output unilaterally. Others might seek to promote further cooperation on coordinated supply restraint, though such moves carry reputational risk if markets judge them as manipulative. Meanwhile, importers in developing markets—particularly in Africa and Southeast Asia—could benefit from cheaper crude. But those gains may not offset pressure on oil-producing economies that rely heavily on export revenue to fund budgets and social programmes.

Goldman Sachs and a subsidiary of the Abu Dhabi Investment Authority have entered into a co-investment alongside PAI Partners in Froneri, valuing the ice­cream conglomerate at around €15 billion, including debt. The transaction restructures PAI’s 50 per cent stake in Froneri by rolling it into a new vehicle, with ADIA as a “significant minority” and a Goldman-led continuation vehicle also taking a position.

PAI has formally completed the €3.6 billion equity transaction, creating a fresh ownership arrangement for its Froneri shareholding. The Goldman Sachs Alternatives instruments, deployed via a single-asset continuation vehicle, attracted oversubscription, while the ADIA subsidiary secured its role as co-investor. PAI emphasised the move underscores confidence in Froneri’s trajectory and enables further growth ambitions. The firm also appointed Weil as legal counsel for the transaction.

Froneri, launched in 2016 as a 50:50 joint venture between PAI’s R&R Ice Cream and Nestlé’s European ice cream operations, now reports annual revenues near €5.5 billion and over 12,000 employees across 25 markets. In 2019 it further expanded by acquiring Nestlé’s U. S. ice cream arm—bringing brands such as Häagen-Dazs, Drumstick, and Outshine into its portfolio. That acquisition elevated Froneri’s global presence and sharpened the competition with Unilever’s Ice Cream business, soon to be spun off as Magnum Ice Cream Company.

Nestlé is retaining its circa 50 per cent share in Froneri and has expressed support for this new capital injection and structural reset. PAI, on its part, expects the new format to help it maintain alignment with institutional investors while reaping long-term value from an asset already showing consistent growth.

The ADIA involvement aligns with the sovereign fund’s strategy to diversify into private equity and alternative investments. ADIA was among the most active sovereign wealth funds in the first nine months of 2025, particularly in co-investment deals and private equity events across global markets. Placing capital into a well–established consumer goods platform like Froneri helps balance its portfolio between growth and stability.

Continuation vehicles, such as the one orchestrated by Goldman Sachs in this case, have seen increasing adoption in private equity markets. They allow firms to extend holding periods for assets beyond the life of original funds, while offering liquidity options to existing limited partners. In this Froneri transaction, demand exceeded expectations—signalling investor appetite for high-quality consumer assets.

China’s largest state banks have committed over $3.75 billion in debt financing to Saudi Aramco’s Jafurah gas project, while Chinese investment funds have declined to take equity stakes in the venture, sources told Reuters.

The bulk of this funding comes from Bank of China, ICBC and China Construction Bank, each contributing around $1 billion, and Agricultural Bank of China adding roughly $750 million. This debt financing accounts for more than one-third of the total capital sought for what is expected to be the largest shale gas development outside the United States.

Aramco’s deal involves an $11 billion lease-and-leaseback agreement signed in August with a consortium led by Global Infrastructure Partners, an arm of BlackRock. Under the arrangement, a new entity called Jafurah Midstream Gas Company will lease processing assets to Aramco for 20 years. Aramco retains a 51 per cent stake, while the consortium holds the remaining 49 per cent.

Despite the opportunity to join the equity syndicate, several Chinese state-linked funds declined to participate, a move that sources attribute to heightened U. S.–China tensions. Beijing is said to have discouraged fund-level engagement with U. S.-affiliated private capital firms, even when such firms do not have overt U. S. exposure.

The Chinese banks’ decision to provide senior debt but avoid equity signals a calibrated strategic posture: backing the project financially without direct governance alignment with U. S.-linked investors.

Aramco’s broader ambition is to expand its gas production capacity by 60 per cent over 2021 levels by 2030. The Jafurah basin is estimated to contain 229 trillion standard cubic feet of raw gas and 75 billion stock tank barrels of condensate.

The BlackRock-led consortium is also negotiating additional capital of around $10.3 billion with a mix of debt instruments; participants in those talks include JPMorgan and Sumitomo Mitsui Banking Corporation. Those financial structures are intended to support the lease-and-leaseback model without ceding control of core infrastructure assets to external parties.

Within the Gulf, Chinese lenders’ prominent involvement in Jafurah’s financing echoes a broader trend. Analysts note that China is repositioning its role in Gulf energy infrastructure by leveraging its strengths in project debt and export credit rather than co-investment in U. S.-sponsored equity schemes.

Saudi Arabia is concurrently expanding its gas network. It has signed over $25 billion in contracts for the second phase of Jafurah development and further gas-network enhancements, including pipeline extensions of 4,000 km to increase capacity by 3.2 billion standard cubic feet per day. Chinese firms, such as Sinopec, are among the contractors participating in these projects.

For Aramco, the dual approach of securing large-scale debt from Chinese banks while partnering with international investors via the leaseback model helps it mobilise capital without relinquishing decisive control. The arrangement offers investors predictable tariff-based returns.

Chinese banks’ exposure gives them influence over covenant terms, loan pricing and repayment schedules. That leverage, without the burdens or political friction associated with equity, aligns with Beijing’s financial diplomacy toward strategic energy corridors.

The full constellation of debt and equity deals around Jafurah—and the dynamics among Gulf producers, Chinese state capital, and U. S.-linked private investors—will be among the key nodes shaping the next wave of energy infrastructure financing.

Space42 has issued its Foresight Constellation Viewpoint, a strategic dossier that underscores how Synthetic Aperture Radar satellite systems, when paired with artificial intelligence, can reshape decision making for governments and industries. The viewpoint emphasises the capacity for persistent imaging, all-weather operation and near-instant analytics — capabilities that are becoming mission-critical in an era of intensifying climate, security and infrastructure challenges.

At the heart of the Viewpoint is GIQ, Space42’s AI engine that converts raw SAR data streams into decision-grade intelligence within minutes. The report argues that the combination of high-resolution persistent coverage and AI transforms Earth observation from static imagery into a dynamic intelligence layer for monitoring, planning and emergency response. Launching Foresight-1 in August 2024 and Foresight-2 in January 2025 has already bolstered the UAE’s Earth observation capability.

Space42 frames its approach as not just a technological upgrade, but a sovereign asset: reliance on third-party satellite data leaves states vulnerable to disruptions, but a domestic SAR-analytics ecosystem offers resilience and control. The global SAR market, currently estimated around $5.8 billion, is forecast to nearly double to $9.8 billion by 2030. According to the Viewpoint, deployment of integrated SAR systems can yield cost savings — for instance, reducing predictive maintenance expenses by up to 30 per cent while improving emergency response by as much as 90 per cent.

The technical backbone of this strategy depends on both the satellite constellation and ground systems. Space42 has entered into a joint venture with ICEYE to localise manufacturing of SAR satellites in the UAE, aiming to strengthen supply chains and transfer expertise. The joint venture builds on prior collaboration: ICEYE’s technology underpins the Foresight satellites, and cooperation is intended to deepen over coming years.

Foresight-2 was successfully deployed via a rideshare launch on 14 January 2025, expanding the constellation’s capabilities and reinforcing its ability to revisit areas multiple times per day. With Foresight-1 and 2 in orbit, the full constellation is expected by 2027. The satellites exploit SAR’s unique ability to image through clouds and in darkness — a significant advantage over optical systems, especially in disaster and high-latency environments.

The Viewpoint also positions its narrative with real-world scenarios. It cites the 2023 Turkey earthquake, in which optical systems were hindered by cloud cover, while SAR satellites continued functioning — enabling assessments of a major dam’s structural integrity in crisis conditions. That example supports the argument that SAR ecosystems must be treated not as supplements but as core infrastructure for resilience and security.

Space42 positions itself as a full-stack player: not merely a satellite operator but a systems integrator combining space services, geospatial analytics and AI. Its dual business units—Space Services and Smart Solutions—serve satellite operations and downstream intelligence markets respectively. Among its touted use cases are border surveillance, maritime monitoring, infrastructure health, mobility and disaster management.

Yet challenges remain. Building sovereign SAR ecosystems demands investment in ground infrastructure, antenna networks, data processing centres and skilled personnel. Market competition is increasing: global players—commercial and governmental—are accelerating developments in miniaturised SAR payloads, hybrid optical/SAR systems and edge AI processing. Moreover, the cost dynamics of deploying dense constellations must be managed against returns from clients in defence, environment and infrastructure sectors.

Dubai’s ride-hailing landscape has shifted dramatically as the UAE-based Zed app now encompasses 10,764 taxis across the emirate—equivalent to more than four in five licensed cabs. The move was enabled through strategic partnerships with Dubai Taxi Corporation and National Taxi, folding in the fleets of three major operators.

Under the new arrangement, DTC’s entire fleet and those of National Taxi and Kabi by Al Ghurair become bookable via the Zed platform, effectively making Zed the host of Dubai’s second-largest taxi fleet. Zed executives describe the expansion as a means of enhancing coverage, cutting cancellations, and lowering wait times, especially across areas traditionally underserved.

Badr Al Ghurair, Zed’s Chief Executive, emphasised the home-grown nature of the platform and its deep knowledge of Dubai’s commuting patterns: “this collaboration … further strengthens Dubai’s mobility ecosystem while ensuring that our communities have access to reliable, everyday transport solutions” he said. Abhinav Patwa, Zed’s EVP and Head, added that the alliances provide scale and reliability without losing sight of a customer-first approach.

The accord comes amid Dubai’s broader ambition of converting 80 per cent of taxi bookings to digital platforms—a target within reach through the emirate’s Smart City 2025 programme. The integrated fleet also introduces more electric and hybrid taxis into Zed’s pool, aligning with the city’s sustainability goals.

This consolidation represents a notable realignment in Dubai’s mobility market. For years, taxis and e-hailing apps operated largely in parallel, with limited overlap in booking channels. The new model bridges that divide, bringing traditional operators into the digital fold via a single platform. Analysts say the move may accelerate the decline in usage of standalone taxi apps and push rivals to forge similar alliances or risk falling behind.

Dubai Taxi Company, now a public joint stock firm under Law No. 21 of 2023, operates more than 10,000 vehicles, of which 6,200 taxis were folded into the agreement. Kabi by Al Ghurair contributed another 3,680 vehicles under the tie-up. According to RTA data, Dubai’s taxi sector expanded by 7 per cent in the first half of 2025 compared with the same period in 2024, signalling growing demand for urban mobility services.

Through the arrangement, newly commissioned taxis across the partner fleets will automatically integrate into Zed’s system—making service expansion incremental and scalable. Several of the added vehicles are electric or hybrid, helping Zed accelerate its greening efforts.

Passengers can now access all these taxis via Zed’s iOS and Android apps, with the platform continuing to offer features such as guaranteed on-time pickups for pre-booked premium rides. The enhanced capacity is expected to reduce wait times during peak hours, improve service in remote zones, and lower the incidence of ride cancellations.

Visitors in Saudi Arabia will be able to open local bank accounts using their “Visitor ID,” following a decision by the Saudi Central Bank to accept the identification document issued by the Ministry of Interior. This marks a major regulatory shift in how non-residents can access financial services in the Kingdom.

SAMA’s directive mandates that banks recognise the Visitor ID—traditionally used for immigration and internal tracking—as a valid identity document for account onboarding, provided it is digitally verifiable through government-authorised platforms. According to SAMA, this adjustment will enable banks to reach new customer segments without altering their existing account-opening rules.

This change aligns with Saudi Arabia’s push under Vision 2030 to expand financial inclusion and improve the visitor experience. By lowering barriers to formal banking, the Kingdom aims to reduce dependence on cash, support digital payments, and draw more tourists, business travellers and pilgrims into regulated financial channels.

Banks will be required to adjust verification systems and compliance protocols to integrate the new policy. Many are expected to link the Visitor ID to local digital check platforms and mobile wallets, allowing holders to conduct everyday transactions. Some limitations may apply: banks may restrict access to credit, loans or other advanced banking services until further identification or residency status is established.

Under existing SAMA account rules, banks already require robust customer identification steps for all new accounts. These include verifying identity documents, screening for anti-money laundering, and collecting customer contact and address details. The updated regulation does not eliminate those checks but changes the baseline identity document accepted for visitors.

Observers see this as one of several steps in a broader regional movement. While Gulf states have long required residence permits or more rigid documentation to open standard accounts, the Saudi reform may test whether similar access models are feasible elsewhere. Already, financial technology and tourism stakeholders are evaluating the competitive edge this gives Saudi Arabia.

Critics caution that implementation risks must be managed carefully. Allowing visitor-based accounts introduces potential anti-money laundering and fraud vulnerabilities. Banks will need to balance user convenience with real-time monitoring, transaction limits, and strong identity verification safeguards.

From the visitor standpoint, the reform reduces friction in accessing local banking: new arrivals will no longer have to rely solely on foreign banks, prepaid cards or cash. Pilgrims and business travellers handling local payments, donations, or services should benefit directly.

SAMA emphasised that the change came through its periodic policy review, intended to keep regulations in line with evolving financial technology trends and market needs. The central bank said it expects the reform to reinforce the Kingdom’s cashless payments infrastructure and strengthen the banking ecosystem’s responsiveness to global customer expectations.

The policy rollout may occur in phases, as banks update internal systems, train staff, and obtain approvals from compliance units. Over the coming weeks, banks are likely to issue guidelines explaining account features, permissible transaction types, and validity periods tied to the Visitor ID status.

Advertisements

Kuwait has issued $11.25 billion in sovereign bonds split across three maturities, marking its first successful US dollar debt sale since 2017 and signalling a renewed re-entry into global capital markets. The offering drew strong investor demand, allowing the country to secure attractive pricing even as it seeks to diversify its funding amid mounting fiscal pressures.

The issuance comprised $3.25 billion in three-year bonds at 40 basis points over US Treasuries, $3 billion in five-year bonds also at 40 bps, and $5 billion in ten-year bonds at 50 bps. Order books reached as high as $28 billion—roughly 2.5 times oversubscribed—enabling Kuwait to tighten guidance from initial levels. Over two-thirds of the allocations went to investors outside the Middle East and North Africa, with significant participation from the United States, Europe, the United Kingdom and Asia.

Acting Finance Minister Subaih Al-Mukhaizeem described the deal as “historic”, citing that it reflects “global markets’ confidence in Kuwait’s financial strength, prudent policies, and solid reserves.” He added that this issuance reinforces Kuwait’s reputation as a credible sovereign issuer while supporting the New Kuwait 2035 vision of economic transformation.

Analysts noted that the spreads achieved in this issuance are significantly tighter than Kuwait’s inaugural dollar bond sale in 2017, underscoring market optimism about its credit metrics and macro outlook. Its low debt burden—currently less than 10 percent of GDP—offers the space for measured borrowing, even while the International Monetary Fund projects that the ratio may rise toward 25 percent by 2030 as deficits widen.

The path to this issuance was opened in March with the passage of a long-delayed public debt law, which raised the borrowing ceiling from KD 10 billion to KD 30 billion and permitted longer maturities. That law had been stalled for years due to clashes between the appointed government and the elected parliament; in response, the emir dissolved parliament for up to four years, clearing the way for reform.

Kuwait is the latest Gulf sovereign to take advantage of favourable global interest rates and strong investor appetite, joining others such as Saudi Arabia, the United Arab Emirates and Bahrain in tapping dollar markets to address fiscal gaps and finance diversification programmes.
While the bond sale delivers fresh funding, questions remain about Kuwait’s strategy for deploying the proceeds. Its economy remains heavily dependent on hydrocarbon revenues, which accounted for nearly 90 percent of government income in the most recent fiscal year. Previous reporting indicates that proposed projects include infrastructure upgrades such as a new port and airport expansion, intended to generate non-oil revenue streams.

GlobalSource Partners had speculated earlier that Kuwait’s general deficit could rise to between 7 and 8 percent of GDP in the current year, with this issuance expected to cover a large portion of the shortfall. The country has also tapped local debt markets, issuing about $5 billion in domestic bonds before turning to international markets.

Riyadh has unveiled a bold draft plan to permit all non-resident foreign investors direct access to the main Saudi stock market, eliminating the need for the current Qualified Foreign Investor framework and abolishing swap agreements. The Capital Market Authority has opened a 30-day public consultation on the proposal, which, if adopted, would mark a major liberalisation in the Kingdom’s capital markets.

Under the draft, non-resident investors would no longer need to satisfy eligibility thresholds currently required for QFI status, and would be permitted to hold shares in listed companies in their own names. The plan would also phase out swap arrangements that allow foreign parties to obtain economic exposure to Saudi stocks without holding legal title. The consultation period runs until 31 October 2025.

The CMA says the changes aim to broaden the investor base, increase liquidity and attract a wider pool of capital. Foreign holdings in the main market had already reached SAR 412 billion by mid-2025, comprising more than 471 percent growth from SAR 72 billion in 2015. Non-resident capital under the QFI regime, combined with swap exposure, totals over SAR 528 billion.

The QFI system currently imposes strict entry criteria — one requirement is minimum assets under management of SAR 1.875 billion. QFIs also enjoy direct ownership and voting rights, whereas swap-based investors operate indirectly. Under the rules, non-resident foreign investors face a cap of 10 percent in any listed firm, while aggregate foreign ownership in a company is capped at 49 percent. Swap contracts are legally structured to grant economic benefits without formal shareholding rights under the depositary centre system.

Market analysts say lifting QFI restrictions could lower barriers for small and mid-sized international asset managers that presently cannot meet the QFI thresholds. “This is a structural shift — it moves Saudi from a screened-access regime to an open one,” commented a Gulf region investment strategist. Observers note, however, that tightening surveillance, settlement and disclosure mechanisms will be essential to managing risks of volatility and capital flight.

Under the draft, swap accounts held by foreign investors would need to be converted to direct shareholding accounts within a transition period of up to 12 months. The CMA also proposes adjustments to reporting, market conduct and corporate governance rules to ensure fairness.

The consultation draft aligns with broader reforms introduced in 2025, including simplification of account opening for some foreign investor categories, especially GCC-residents or overseas investors with prior residency in the region. That move had already signalled a gradual loosening of restrictions.

Equity markets in the Gulf contrast in openness. The UAE and Qatar allow broader foreign participation, while Saudi’s incumbent QFI plus swap structure has long been viewed as more restrictive. Proponents of liberalisation contend that full direct access may raise Saudi’s appeal as a regional hub and deepen cross-border portfolio flows.

The U. S. Securities and Exchange Commission’s Division of Investment Management has issued a no-action stance confirming that registered advisers and regulated funds may use state-chartered trust companies for custody of crypto assets without fear of enforcement under certain conditions.

Under the letter released on 30 September, the SEC staff stated it “would not recommend enforcement action” against advisers or funds that treat state trust companies as a “bank” for purposes of holding digital assets and related cash, provided they adhere to strict safeguards and eligibility requirements. The letter stops short of legal advice, but marks a shift in how crypto custody might evolve under federal oversight.

While the no-action relief does not carry the force of a rule, it addresses long-standing ambiguity over whether state trust companies qualified as custodians under the Investment Advisers Act and the Investment Company Act. The guidance is conditional on advisers performing due diligence to confirm the trust’s authority, maintaining audited financial statements, segregating client assets, restricting rehypothecation without client consent, and verifying internal controls.

The SEC’s letter was precipitated by a request from law firm Simpson Thacher & Bartlett on behalf of financial advisers seeking formal assurances about using state trust entities for crypto custody. This marks the second such no-action letter from the agency in short order, reflecting a trend towards regulatory clarity in crypto frameworks.

Proponents argue the move broadens the pool of eligible custodians beyond a small set of federally chartered institutions. Many prominent crypto custodians already operate under state trust charters, including affiliates of Coinbase, Paxos, and others. Under previous regulatory interpretations, these firms faced uncertainty about whether they satisfied the “qualified custodian” requirement.

SEC Commissioner Hester Peirce applauded the letter, saying it ends the “guessing game” that advisers confronted in choosing custody providers. She suggested the guidance could pave the way for future reforms of custody rules that are more flexible and technology-aware. However, Commissioner Caroline Crenshaw dissented, warning that the agency’s move bypasses formal rulemaking and could undermine trust in the regulatory process by favouring state trust firms over applicants seeking national charters.

Market observers welcomed the clarity. James Seyffart, an ETF analyst, described the letter as “a textbook example of more clarity for the digital asset space.” Institutional participants, previously wary of custody risk, may now consider deeper allocations to crypto. The move may also prompt competition from new entrants able to operate under state trust frameworks.

The city-state’s employers have set a striking pace as they head into the final quarter of 2025: a Net Employment Outlook of 45 per cent signals that nearly three in five organisations expect to expand their workforces. That optimism comes amid shifting global headwinds, structural reforms, and a rising demand for specialised talent.

The ManpowerGroup Employment Outlook Survey canvassed 525 UAE employers across sectors to assess hiring intentions. A positive balance of 45 per cent means that those anticipating workforce increases outnumber those expecting reductions by nearly half. This figure places the UAE among the world’s more aggressive labour markets, especially given challenges such as global trade uncertainty, rising automation, and fluctuating commodity prices.

This projected hiring boom is not evenly distributed. The strongest demand lies in transport, logistics and automotive, energy and utilities, and consumer goods and services. These sectors appear ready to leverage infrastructure projects, green energy transitions, and regional consumption growth. Meanwhile, the information technology sector is showing solid demand at +48 per cent, reflecting sustained digital transformation pushes.

Driving much of this confidence is corporate expansion: 40 per cent of participating firms cited scaling operations as their primary reason for hiring. Another 28 per cent pointed to pivoting business models and growth into new areas. In addition, nearly 30 per cent of respondents acknowledged that talent shortages—and competition for specialised skills—are influencing recruitment strategies.

Yet the buoyant sentiment is tempered by caution. Roughly 10 per cent of employers still expect to trim staff, particularly in roles vulnerable to automation or in sectors facing structural disruption. Around 15 per cent responded that they will hold staffing constant, prioritising internal upskilling over external recruitment. In interviews, some HR executives noted that while they want to hire aggressively, wage inflation, geopolitical uncertainty, and regulatory shifts may prompt them to phase recruitment over several quarters.

Regional and global context strengthens the UAE’s position. In the third quarter of 2025, the UAE recorded a world-leading NEO of +48 per cent. That marked a standout alignment with its long-term growth strategy, and the Q4 figure of +45 per cent suggests sustained momentum rather than a cyclical spike. Elsewhere, the global average NEO stood at +24 per cent during Q3 — placing the UAE’s outlook nearly double the global benchmark.

Analysts view this hiring optimism as part of a broader strategy to reposition the UAE as a knowledge-economy hub. Recent government initiatives have focused on advanced manufacturing, artificial intelligence, sustainability, and logistics corridors. These programs have triggered demand not only for engineers and technicians but also for data scientists, sustainability consultants, and cross-disciplinary professionals. In one corporates sector round-table, a senior UAE CEO observed that “the competition for deep tech talent is global, and we must offer not just pay but opportunity, stability and a pathway for growth.”

Labour authorities are also aligning policies with employer needs. New visa frameworks, targeted Emiratisation programmes, and regulatory incentives for R&D investment are being synchronized with workforce forecasts. At the same time, the UAE’s PMI for non-oil activity has held above the expansion threshold, underlining demand growth across private sectors and supporting hiring intent.

However, potential headwinds remain significant. Global supply chain disruptions, slowing demand in key export markets, and monetary tightening in major economies could dampen growth. Employers may delay or scale back hiring plans if external pressures intensify. Some labour economists warn of mismatches between skills supplied locally and those demanded, especially in emerging fields.

Gold surged to an unprecedented high on Wednesday, driven by investor flight to safe assets after the United States entered a federal government shutdown that threatens to delay key economic data releases.

Spot gold climbed above $3,875 per ounce, and U. S. gold futures for December touched $3,887.40, marking fresh peaks in the metal’s dramatic rally this year. The dollar weakened, while U. S. stock futures slid, reflecting the heightened uncertainty gripping global markets.

The shutdown froze large swathes of federal operations after Congress failed to approve funding for the 2026 fiscal year, triggering furloughs for approximately 750,000 federal workers and imposing a daily cost to the government of around $400 million.

With the shutdown effectively halting the release of critical economic indicators—most notably the September non-farm payrolls data—the Federal Reserve is being forced to rely on alternate data sources to assess conditions ahead of its October meeting. Chicago Fed President Austan Goolsbee warned that central bankers will need to “turn to other data sources” if official reports are suspended.

In labor market reports released earlier, the JOLTS data showed only marginal growth in job openings in August, while hiring declined—signalling cooling momentum in the U. S. labour market. This, combined with the shutdown, has increased market expectations that the Fed will move to cut interest rates in October. Futures now price in a 96 per cent likelihood of a 25-basis-point cut.

Institutional demand has bolstered the gold rally: central banks have continued to accumulate bullion, even as inflows to gold-backed exchange-traded funds have surged. Analysts point to a powerful confluence of safe-haven inflows and speculative momentum. Deutsche Bank and other firms have flagged upside targets in the $3,900–$4,000 range if current conditions persist.

Silver also posted gains, hitting a 14-year high, while platinum and palladium lagged modestly. In India, gold prices on the MCX breached all-time highs, crossing ₹1,17,351 per 10 grams as global and domestic investors sought shelter from volatility.

Analysts caution, however, that the rally faces key risks. A rebound in the dollar, a surprise hawkish tilt from the Fed, or a sudden resolution of the funding impasse could reverse momentum. The longer the shutdown endures, the greater the danger that data collection becomes impaired—threatening the quality of future releases such as inflation, GDP, and employment statistics.

The valuation of the U. S. Treasury’s gold reserves has also gained attention: the gold holdings—officially booked at historical rates—now command a market value exceeding $1 trillion, driven by the steep rise in bullion prices.

Wall Street insiders note that the shutdown has injected a new element of volatility into markets already stretched by geopolitical tensions and macro imbalances. Equity futures were already under pressure on Wednesday, with the S&P 500 and Nasdaq both down nearly 0.5 per cent in early trade.

Abu Dhabi — The Federal Authority for Identity, Citizenship, Customs and Port Security has introduced sweeping changes to the UAE’s visa regime, adding four new visit-visa categories tailored to specialists in artificial intelligence, entertainment, events, and cruise or leisure-boat tourism, while also rolling out humanitarian and widow/divorcee residence permits.

Under the new framework, the AI Specialist Visit Visa allows single or multiple entries, provided applicants submit a sponsorship letter from a recognised technology or AI institution. The Entertainment Visit Visa is intended for individuals engaging in licensed entertainment or gaming activities, while the Event Visit Visa covers attendance at festivals, exhibitions, conferences, sports, or cultural events, sponsored by public or private hosts. The Cruise & Leisure-Boat Visit Visa offers multiple-entry permits for travellers arriving via marine routes, on condition of submitting a detailed itinerary and engaging a licensed host in the tourism industry.

Alongside these targeted visit visas, the ICP now issues a Humanitarian Residence Permit, valid for one year, with possible extension under certain conditions. This permit is designed to assist individuals from countries experiencing conflict, natural disasters, or severe unrest. Notably, it can be granted without a guarantor or host, though it may be cancelled or voided if the holder departs the UAE. In exceptional cases involving relatives or in-laws, the authority may waive requirements like financial solvency or degree of kinship.

The revisions also extend protections to foreign widows and divorcees. A one-year renewable residence permit is available to foreign women whose UAE-based husband died or divorced, provided applications are submitted within six months. If the husband was a non-UAE national, eligibility depends on whether the woman held residency at the time, whether she has custody of children, and whether she was previously sponsored. Provisions for adequate housing and financial stability apply, and custody disputes will be adjudicated by a designated committee.

Revised rules for sponsoring friends or relatives now incorporate income thresholds: sponsors must earn at least AED 4,000 per month to sponsor first-degree relatives, AED 8,000 for second- or third-degree relatives, and AED 15,000 to sponsor friends. The updated system also introduces a structured schedule defining visit-visa durations and extension rules.

Other key visa reforms include tightening the Business Exploration Visa criteria and easing Truck Driver Visas—allowing single or multiple entries provided drivers are sponsored by licensed freight or transport companies and meet health, fee, and financial guarantee conditions.

In a statement, Major General Suhail Saeed Al Khaili, Director General of ICP, said the reforms emerge from “careful studies and forward-looking assessments” that considered global residency trends, client feedback, and the UAE’s strategic demands. He described the changes as intended to “meet the needs of customers while considering humanitarian and economic circumstances” and to drive technology, tourism, and economic diversification.

The Central Bank of the UAE and Dubai Finance today formalised an agreement to deepen collaboration in the development of the country’s capital markets, enabling Dubai to draw on the central bank’s infrastructure to issue dirham-denominated government bonds.

Khaled Mohamed Balama, Governor of the CBUAE, and Abdulrahman Saleh Al Saleh, Director-General of Dubai’s Department of Finance, signed the Memorandum of Understanding in Abu Dhabi before senior officials and assistant governors.

Under the pact, Dubai Finance gains access to the central bank’s systems and platforms to support bond issuance, while both parties commit to joint efforts in fintech, payment systems, and digital currency development. The agreement further encompasses capacity building, knowledge exchange and coordination in regulatory and infrastructural domains.

Balama described the partnership as “an important step toward advancing the country’s financial markets, supporting their growth, and ensuring their readiness to adapt to future changes.” He affirmed that the nation’s leadership is focused on promoting innovation and digitisation in financial services to boost private-sector participation and investor confidence.

Al Saleh said the MoU would help diversify the UAE’s investment tools and align capital market expansion with the vision of the country’s leadership. He emphasised the importance of collaboration with regulatory bodies at both federal and local levels to elevate the nation’s reputation as an investment hub.

The MoU aligns with broader moves by the central bank in strengthening financial infrastructure and market regulation. The central bank has recently advanced its “Financial Infrastructure Transformation” programme, which includes the rollout of the domestic card scheme Jaywan and development of a Central Bank Digital Currency, known as the Digital Dirham. The institution also introduced regulations on Open Finance platforms and has conducted stress tests affirming resilience in the banking sector under diverse macroeconomic pressures.

The UAE’s push to build robust capital markets fits into a regional trend of using debt instruments to broaden funding sources beyond oil and real estate. In December 2024, the CBUAE signed an MoU with the Hong Kong Monetary Authority to enhance cross-border debt issuance and settlement between the UAE and Asia, aiming to foster deeper connectivity between debt markets.

Analysts see the newly inked agreement as a mechanism to centralise the infrastructure layer of government debt issuance under one roof, avoiding fragmentation across emirates. Doing so could lower costs, standardise procedures, and deepen liquidity in domestic markets. It may also foster greater issuance activity from state and municipal entities.

Arabian Post Staff -Dubai Tokyo — Casio Computer Co. has introduced its first mechanical timepiece within its EDIFICE family, unveiling the EFK-100 series that incorporates a forged-carbon dial in one variant and combines motorsport aesthetics with traditional watch engineering. The flagship model, EFK-100CD-1A, features a dial made of forged carbon—never before used in an EDIFICE timepiece—and is powered by an automatic movement visible through a display case […]

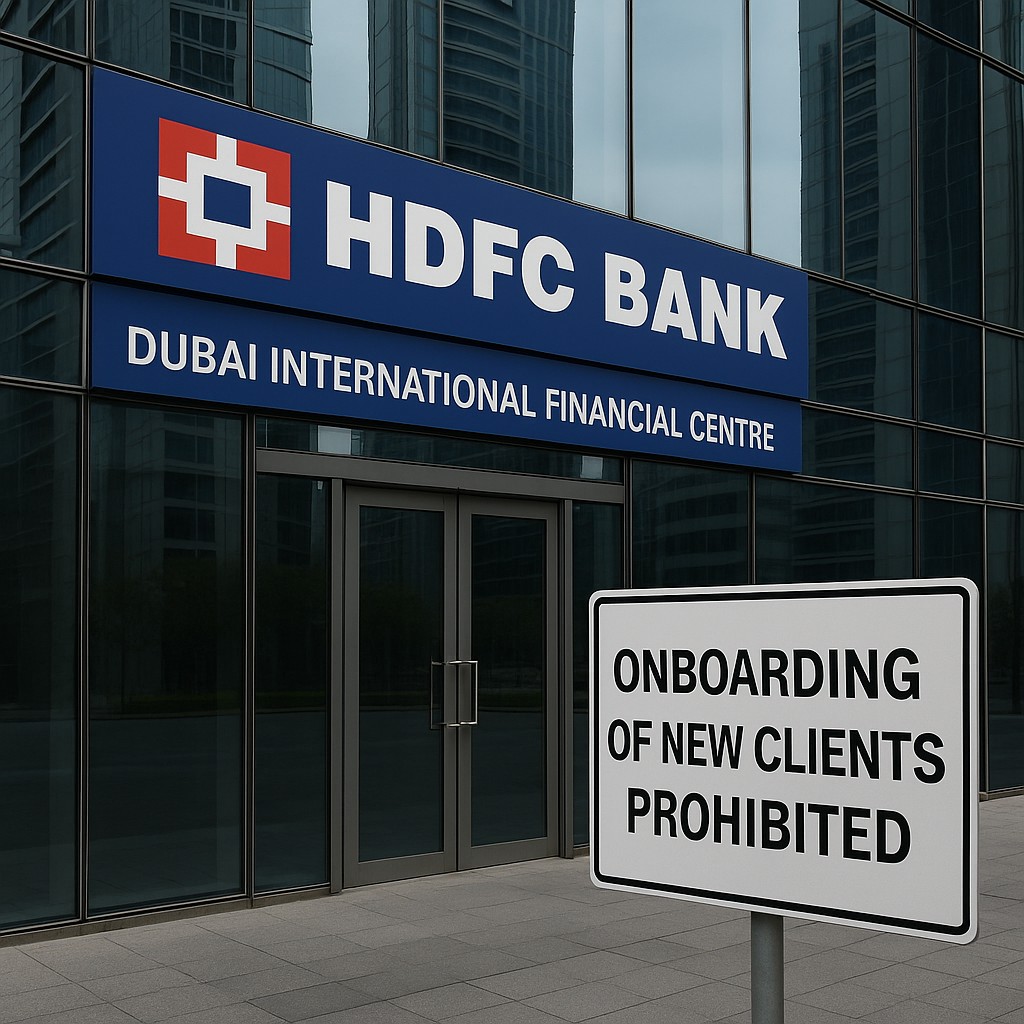
Dubai’s financial regulator has barred HDFC Bank’s Dubai International Financial Centre branch from soliciting, onboarding or servicing new clients, citing compliance lapses.

The order, issued by the Dubai Financial Services Authority and effective from 26 September, remains in force “until otherwise amended or revoked,” the bank stated. HDFC said it is taking steps to comply with the directive while engaging with the DFSA to address concerns.

HDFC clarified that the restriction does not apply to existing clients of the DIFC branch, nor to those who had already been offered services prior to the notice. As of 23 September, the branch had 1,489 customers, including joint holders.

According to HDFC, the bank does not expect this to materially affect its overall operations or financial position, noting that the Dubai branch’s business is not significant relative to its global activities.

The DFSA’s decision notice accuses the branch of servicing clients who were not properly onboarded, deficiencies in client onboarding processes, and other unspecified compliance shortcomings. The prohibition extends to advising on financial products, arranging deals, extending credit, custodial services, and financial promotions for new clients.

Analysts point to a backdrop of scrutiny over HDFC’s role in selling risky instruments—particularly Credit Suisse additional tier-1 bonds—to retail investors in the UAE. Those clients accused the bank of misclassification and inadequate risk disclosures. Investor accounts allege that KYC records were manipulated to designate them as “professional clients,” a requirement under DIFC rules for high-risk products.

Some UAE-based investors welcomed the DFSA’s move but urged stronger action, stating the suspension of new client intake is a limited measure given potential damage already done.

HDFC has a broader international presence including representative offices in Abu Dhabi, Kenya, London and Singapore, and branches in Bahrain and Hong Kong. The bank faces parallel scrutiny in India regarding related sales practices, prompting investigations by Indian enforcement agencies.

As the DFSA and HDFC engage in remediation talks, markets will closely watch whether the regulator escalates sanctions or lifts the ban after compliance is demonstrated.

A widespread veil of fog has prompted the National Centre of Meteorology to raise red and yellow alerts across several emirates, with parts of Abu Dhabi reporting visibility under 1,000 metres and road users urged to exercise extreme caution.

Fog enveloped numerous regions across the UAE, including Al Dhafra, Ghiyathi, Yaw Al Nadhrah, Baynounah and Um Al Ashtan, as well as parts of Dubai, resulting in variable speed limits on key highways and frequent warnings from traffic authorities. In Abu Dhabi, electronic signboards are being used to dynamically adjust permissible speeds in response to shifting visibility. Authorities also issued repeated reminders to follow traffic signals and stay alert to sudden changes in road conditions.

The NCM forecast clear to partly cloudy skies for the day, but cautioned that humidity levels would rise overnight, which may cause fog formation to persist into early Monday morning in inland and coastal areas. Winds are expected to be light to moderate, occasionally gusting to 40 km/h over sea areas. Sea conditions are likely to remain slight to moderate in the Arabian Gulf, becoming rough toward the western zones, while the Gulf of Oman is expected to stay relatively moderate.

Temperature highs for the day are projected to reach around 40 °C in Abu Dhabi and Dubai, while overnight lows may dip to between 25 °C and 31 °C, further elevating the risk of condensation and mist formation by dawn. Humidity is set to reach levels as high as 90–95 percent, especially in coastal zones.

Abu Dhabi Police, in a public advisory, urged motorists to keep lights on, maintain safe following distances and heed variable speed signs. They reiterated that foggy patches may develop unpredictably along inter-emirate and rural routes. Traffic safety officers are being stationed at vulnerable corridors to assist drivers and manage flow.

Dubai has secured a position among the world’s top four FinTech centres, according to the latest Global Financial Centres Index published on 25 September, signalling a pivotal shift in the emirate’s financial technology trajectory.

The GFCI report places Dubai at 11th globally in the overall ranking of financial centres, but underscores its standing as one of the most dynamic hubs for FinTech innovation. The Dubai International Financial Centre has played a central role in driving this transformation.

DIFC now houses over 1,500 companies focused on AI, FinTech, and innovation, making it the region’s largest cluster of its kind. These firms have collectively raised more than US$4.2 billion in funding, strengthening the UAE’s appeal as a destination for growth-stage tech ventures. Sheikh Maktoum bin Mohammed bin Rashid Al Maktoum, First Deputy Ruler of Dubai and Minister of Finance, credited the rise to the strategic goals of the Dubai Economic Agenda D33 and to Dubai’s business-friendly infrastructure and regulatory regime.

Essa Kazim, Governor of the DIFC, stressed that the momentum reflects long-term planning and deep investment. He noted that positioning Dubai among the top global FinTech players has required calibrated incentives, robust legal frameworks, and international partnerships. Arif Amiri, Chief Executive Officer of the DIFC Authority, said the locale’s success stems from synergy among institutional support, talent attraction, and ecosystem-building efforts.

Dubai’s ascent in the FinTech league emerges amid intensifying global competition. Traditional financial centres such as London, Singapore, and Hong Kong continue to maintain strong footholds, leveraging established networks, global institutions, and mature regulatory systems. Yet Dubai’s rapid rise indicates that newer hubs with nimble regulation and aggressive incentives can leapfrog in the tech-driven financial services landscape.

The GFCI 38 ranking shows Dubai overtaking several peers in the Gulf and Asia, with the city gaining one rank to 11th place overall and closing gaps in score metrics used to assess competitiveness, such as human capital, reputation, and business environment. The GFCI emphasises that “expected future significance” is one of the domains in which Dubai leads globally—an indication that market participants foresee further growth in its influence.

Arabian Post Staff -Dubai Google has begun deploying firmware version 4.467 to Pixel Buds Pro 2 units, introducing several enhancements designed to make the earbuds more context-aware, safer, and easier to control without touching your phone. The most significant addition, Adaptive Audio, lets the device adjust noise cancellation in real time rather than forcing users to pick between full ANC, transparency mode or off. The system analyses […]

Kuwait Petroleum International and payments provider WEX have launched a joint fuel card in Italy, called CartissimaQ8-WEX, offering business customers access to a network of more than 3,400 service stations, including Q8, Q8easy, and authorised partners.

Under the partnership, WEX cardholders will be able to refuel across Italy’s Q8 network and partner sites, gaining visibility over fuel consumption and simplified billing. KPI said the initiative is part of its strategy to deepen its footprint in the Italian market by introducing a new sales channel in collaboration with a payments specialist.

The agreement provides WEX customers access to a broad distribution system spanning Q8, Q8easy and authorised stations across Italy. KPI’s network in the country already includes several hundred stations, and this card linkage aims to consolidate its reach by leveraging WEX’s fleet and payments infrastructure.

WEX has been actively expanding its European fuel network via partnerships in countries such as France and the Netherlands, tying up with Carrefour and Sakko to broaden its acceptance footprint. That expansion effort dovetails with this new agreement, enabling cross-market leverage.

While KPI is the local operating arm of Kuwait Petroleum Corporation, WEX is a US-based payments and fleet services firm. The alliance represents a fusion of upstream fuel retailing and downstream payments infrastructure. It also reflects a broader trend in the energy sector: fuel retailers seeking to strengthen customer retention through integrated payment and fleet management services.

Stakeholders in the Italian fuel and mobility markets view the move as a response to intensifying competition from independent fleet card providers and mobility fintechs. By embedding payments into its fuel ecosystem, KPI hopes to capture a larger share of corporate fleet spend and lock in recurring usage.

Industry analysts note that acceptance scale is key to fleet card uptake; the more stations that accept a given card, the more attractive it becomes for fleet operators. With 3,400 stations accessible under CartissimaQ8-WEX, the offering is immediately competitive.

Arabian Post Staff -Dubai Dubai-based lifestyle and hospitality conglomerate FIVE Holdings has secured a $460 million revolving credit facility that will be used to repay its $350 million green bond ahead of schedule and free up capital for further growth. The facility, arranged with Commercial Bank of Dubai, AAIB and Santander, enables the group to retire its green bond three years before it matures, leaving it with […]

The UAE Ministry of Finance, acting as issuer with the Central Bank of the UAE as issuing and payment agent, has completed the September 2025 auction for dirham-denominated Islamic Treasury Sukuk, issuing AED1.1 billion in two tranches.

Investor appetite proved robust: total bids reached AED5.1 billion, representing an oversubscription rate of 4.6 times. The two tranches mature in August 2028 and May 2030. Yields to maturity were set at 3.64 percent for the 2028 tranche and 3.72 percent for the 2030 tranche, with spreads of up to 5 basis points over comparable US Treasuries. The new Sukuk are now listed under the UAE Treasury Islamic Sukuk Programme on Nasdaq Dubai, bolstering their tradability in secondary markets.

This issuance is part of the 2025 T-Sukuk programme designed to deepen the UAE’s domestic Islamic capital market and to help establish a dirham yield curve. Authorities view it as a tool for liquidity management and as a mechanism to broaden investment options for both regional and international investors participating in the UAE’s fixed-income markets.

Market observers note that the oversubscription signals confidence in the UAE’s fiscal credentials and its commitment to injecting dynamism into its debt capital markets. The tight pricing relative to US Treasuries is seen as competitive and attractive for institutional players seeking yield in the Gulf region.

In recent months, the UAE has steadily pursued domestic sovereign Islamic issuances as a complement to conventional instruments, seeking to accommodate demand from Islamic financial institutions as well as conventional banks’ Shariah-compliant units. The coordination between the Ministry of Finance and the Central Bank ensures that these issuances are integrated into broader monetary and financial stability objectives.

Across the Gulf, sovereign issuers have increasingly leaned into domestic currency Islamic instruments to reduce dependence on external funding, develop local capital markets, and provide alternative yield playbooks for investors. Within that context, the UAE’s T-Sukuk programme is gaining traction as a benchmark vehicle.

Primary dealers participating in the auction included eight banks, all mandated under the program to support both primary and secondary market activity. Their participation is key to maintaining liquidity and encouraging wider investor participation beyond the initial subscription.

Dubai’s Roads and Transport Authority has unveiled a new strategic focus for the 5th Dubai World Challenge for Self-Driving Transport, scheduled for 2027: smart integrated infrastructure. Mattar Al Tayer, Director-General and Chairman of the Board of Executive Directors of the RTA, said the competition will pivot to challenges that bind sensing, connectivity and analytics to urban infrastructure across Dubai.

At the closing of the Dubai World Congress for Self-Driving Transport held at the Dubai World Trade Centre, RTA inked four key agreements with Emaar Properties, Al Futtaim Group, and the winners of the 2025 challenge—WeRide and Deutsche Bahn consortium, together with Zelos Technology—to deploy and test autonomous systems in Festival City, Creek Harbour and other strategic urban zones. Al Tayer affirmed that the move aligns with Dubai’s ambition to serve as a global testbed for mobility innovation.

This year’s theme shifts from discrete vehicle-centric competition to a systems-level mandate: entrants will be judged on how well their solutions embed into city-wide networks of sensors, roads, communication links and data platforms. The RTA framework calls for designs that anticipate traffic dynamics, weather variations and public transit interaction, while maintaining safety, resilience and sustainability.

Over 3,000 participants and more than 80 expert speakers participated in the Congress, spanning government, academia and industry. The gathering marked the formal launch of the 2027 edition. The Congress also highlighted Dubai’s strategic goal that by 2030, one quarter of all journeys within the emirate will be autonomous or smart-enabled—an ambition already embedded in the RTA’s transport roadmap.

Stakeholders see this shift as an essential maturation of the challenge format. Rather than focusing only on individual vehicle prototypes, the next competition will test ecosystem coherence and scalability across urban modules. According to industry analysts, the new direction presses participants to align with evolving demands in mobility, where digital and physical layers must fuse.

Dubai’s prior edition in 2025 carried the theme “Dubai Autonomous Transport Zone,” pushing contestants to integrate multiple autonomous mobility modes in defined neighbourhoods. That foundation now gives way to a broader remit, with RTA officials stressing that smart infrastructure is the backbone for reliability and public acceptance of self-driving systems.

The agreements struck with developers and past challenge winners will see pilots in zones like Festival City and Creek Harbour, where road layouts, sensor grids and vehicle operations will be tested side by side. RTA counts on these field deployments to validate technical performance, operational cost and citizen experience before full-scale adoption.

Critics caution that the complexity of integrating diverse systems—communications, edge computing, failsafe control layers—could raise cost, regulatory and interoperability risks. Some stakeholders argue the success of the 2027 challenge will depend on whether entrants can navigate not only technical but institutional challenges across urban agencies and telecommunications providers.

For technology firms and research groups, the new emphasis offers both opportunity and challenge. It rewards proposals able to harmonise hardware, software, data and governance. Observers expect to see consortia spanning telecom operators, municipal agencies, AI firms, and road infrastructure specialists.

Abu Dhabi is marketing a three-year and a 10-year US dollar Reg S/144A bond offering, aiming to capitalise on robust investor demand and reinforce its global funding outlook. The three-year tranche is pitched at approximately 40 basis points over US Treasuries, while the longer 10-year issue is offered at around 55 bps.

By mid-morning in Dubai, books had swelled past $10 billion, excluding joint lead manager interest, with slight tilt toward the 10-year line. The bonds will be senior, unsecured and rated AA/AA by S&P and Fitch, matching the issuer’s prevailing Aa2/AA/AA credit standing. Listings are planned in both London and Abu Dhabi.

Investors see this transaction as a test of global appetite for Gulf sovereign credits amid a cautious backdrop of moderate US interest rates and evolving geopolitical risk. Despite volatility in energy prices and external debt markets, Abu Dhabi’s strong fiscal and balance sheet metrics underpin confidence in its sovereign name. The credit ratings assigned reflect the emirate’s resilient fiscal policy, substantial hydrocarbon reserves, and large sovereign wealth fund buffers.

Structurally, the Reg S/144A setup allows the issuer to access both non-US and US institutional investor pools. Regulation S permits offers outside the United States, while Rule 144A enables sales to qualified institutional buyers within the US, offering dual reach while maintaining issuance flexibility. The base offering circular explicitly restricts transfers and resales to be compliant with those regimes.

Observers note that the pricing levels—40 bps for three years and 55 bps for 10 years over Treasuries—are ambitious but not unprecedented within Gulf sovereign borrowing. Prior precedent includes a multi-tranche Abu Dhabi sovereign bond of $5 billion in April 2024, which achieved strong oversubscriptions and favourable pricing benchmarks. That deal underlined investor appetite for Gulf issuers with strong credit credentials.

Market participants closely monitor skew and order distribution between tenors. That the books are marginally skewed toward the 10-year suggests appetite for duration, perhaps reflecting yield scarcity in core markets. Should the order book widen further, the issuer may flex uncertainty concessions or tighten spreads modestly before final pricing. Co-ordinating banks are likely adjusting intermediate guidance as allocations firm.

Analysts flag that appetite for Gulf sovereign issuance is tempered by global headwinds: tighter US credit spreads, sticky inflation, and competition from other supranational and sovereign issuers. Some international investors may demand additional premium for regional or geopolitical exposures. Yet Abu Dhabi’s entry with a dual-tranche issuance signals intent to extend its credit curve, deepen investor relationships, and enhance liquidity in its sovereign bonds.

The listings in London and Abu Dhabi are intended to enhance secondary market trading, improve visibility to European and global investors, and cement Abu Dhabi’s status in global bond markets. The London listing, especially, provides access to a deep pool of international fixed income investors and a regulatory framework well understood by global asset managers.

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA