News related to
growth

Spanish café operator Vanadi Coffee has approved a plan to allocate up to €1 billion of its treasury into Bitcoin, marking a striking pivot from its core hospitality business into crypto‑asset accumulation. The decision, ratified by shareholders on 29 June, seeks to position the firm—currently loss‑making and operating just six outlets—as one of Spain’s largest Bitcoin holders.

Vanadi already owns 54 BTC, acquired at an average price of around €93,444 per coin, valued today at approximately €5.8 million. Its share price surged over 25 per cent following the announcement, a staggering boost for a business that reported €3.3 million in losses during 2024. Market observers note the stock has rallied more than 400 per cent year‑to‑date on hopes that crypto‑oriented balance sheets can act as alternative stores of value.

The strategic shift draws inspiration from established Bitcoin treasury pioneers such as MicroStrategy, which holds nearly 500,000 BTC and has leveraged convertible equity vehicles to fund its crypto purchases. Likewise, Japanese firm Metaplanet is acquiring Bitcoin aggressively as part of its acquisition-backed model. Vanadi’s leadership believes this approach can appeal to institutional investors seeking inflation hedges without disrupting conventional asset portfolios.

Analysts warn the company faces elevated risk. Vanadi operates at a negative equity of around €600,000, and auditors have flagged uncertainty over its going‑concern status. Critics argue a small café chain with slender margins and negligible exposure to financial markets may lack the sophistication to withstand Bitcoin’s volatility and regulatory scrutiny.

Financing the Bitcoin ramp‑up will involve issuing convertible bonds and equity, leveraging commitments from niche funders including Patblasc Software Consulting and Alpha Blue Ocean’s Global Tech Opportunities 10. Some question both the provenance and capacity of these investors, given their prior backing of distressed asset plays such as Intercity and Substrate AI.

Vanadi acknowledges the gamble may redefine its identity: “We aim to become the largest listed Bitcoin‑holding company in Spain,” it said, equating its structural transformation to precedent‑setting players in the sector. Nonetheless, it has had to scale back expansion ambitions, cutting its growth pipeline amid constrained resources and shifting priorities.

Vanadi’s strategy forms part of a broader wave of crypto treasury activity. A growing number of under‑the‑radar firms in Europe—from chipmakers to fintech startups—are joining major players in the US and Asia investing heavily in Bitcoin. Collectively, these firms moved over 10,000 BTC onto their books in late June, totalling several billion dollars in accumulated digital assets.

Experts suggest this trend follows Gartner’s classic hype‑cycle pattern: as Bitcoin becomes easier to acquire and gain public approval, doubt gives way to widespread optimism—driving speculative surges across new sectors. Vanadi’s move, while surprising due to its modest scale, fits squarely within this wave of enthusiasm.

London‑listed Strategy recently launched a $21 billion preferred stock offering to fund more Bitcoin purchases, underscoring how corporate balance sheets are being reconfigured around digital assets. Vanadi hopes to replicate this formula, albeit with far fewer resources and heightened risk exposure.

Vanadi’s management calls the transition a “long‑term bet on a decentralised financial model,” arguing that crypto reserves provide institutional credibility and operational transparency under existing market regulations. Yet, whether this approach offers sustainable upside or represents a peak‑hype miscalculation remains under intense debate among analysts and investors.
For the winners of the 2025 Golden Bull Award, the answer is clear: vision, agility, and a drive to challenge the norm. KUALA LUMPUR, MALAYSIA – Media OutReach Newswire – 10 July 2025 – These are high-performing companies and trailblazers. This year’s winners are leading the way through innovation, from adopting AI and strengthening cybersecurity to integrating ESG values into their core operations. They show us that […]

MENA region investment banking fees declined 2 per cent year‑on‑year in the first half of 2025, falling to US$773.7 million, the third‑highest H1 tally since 2000, according to London Stock Exchange Group’s Deals Intelligence data. The dip occurred amid an environment of oil‑price volatility, geopolitical fragmentation and escalating global trade tensions. Debt capital markets underwriting emerged as the growth engine, with related fees rising 20 per cent to US$278.9 million. However, […]

Senior officials from Saudi Arabia, the United Arab Emirates and Kuwait have defended the August production boost of 548,000 barrels per day, stating that global markets are absorbing the extra supply without piling up inventories. UAE Energy Minister Suhail al‑Mazrouei told delegates in Vienna that inventories have remained stable despite the accelerated output increases, reflecting genuine consumption growth. Kuwait Petroleum Corp. echoed this view, with its CEO Sheikh Nawaf Al‑Sabah noting strong demand from Asian customers and signalling a tighter market than widely perceived.

Oil markets displayed resilience as Brent crude climbed above $70 a barrel, recovering from an initial dip following the OPEC+ announcement. Analysts cite robust summer travel demand, Middle East geopolitical strains—such as intermittent Houthi attacks in the Red Sea—and tighter fuel product cracks as underpinning near‑term market firmness. The supply surge, although substantial, has not yet triggered signs of oversupply. OECD stock levels remain flat, while US Strategic Petroleum Reserve levels stay well below maximum, pointing to a balanced market setup and sustained product demand.

The OPEC+ decision marks an acceleration of a reversal programme that began in April with a modest 138,000 bpd increase, followed by three successive monthly hikes of 411,000 bpd. The latest announcement represents a strategic shift: rather than merely unwinding voluntary cuts, producers are intent on reclaiming market share and anchoring long-term stability. Saudi Arabia, which had shouldered most of the original production curbs, is now pushing ahead to restore output levels much faster than previously scheduled.

UAE officials emphasise fundamentals over headlines, asserting that additional barrels were essential to maintain equilibrium rather than depress prices. “We haven’t seen a major buildup in inventories, which means the market needed those barrels,” al‑Mazrouei said, stressing the need for steady investment in oil infrastructure. Kuwait’s Sheikh Nawaf further highlighted sustained demand growth—particularly in Asia—estimating additional global need of up to 1.3 million bpd over the year and pointing to record-high shipments from his country in June.

Supporting evidence emerges in price trend analysis. Despite the supply increase, Brent crude closed near $69–$70 per barrel, with West Texas Intermediate at approximately $68. Reuters reported a 1 per cent rise in oil prices shortly after the announcement, driven by stronger-than-expected demand signals and a dip in US production projections. Market commentary suggests that the anticipated supply surplus may not materialise until later in the year, allowing current price support to persist.

However, concern is building among forecasters regarding the risk of supply outpacing demand in the months ahead. Analysts at ING and Bloomberg caution that cumulative increases—including a potential similar rise in September—could tilt the market towards surplus by winter. Goldman Sachs predicts Brent could drop to an average of $59 in the fourth quarter if these trendlines hold. Such projections underscore the delicate balance between stabilising markets today and sowing the seeds of tomorrow’s oversupply.

Geopolitical factors continue to sway market sentiment. Renewed attacks by Houthi forces on shipping lanes in the Red Sea have boosted risk premiums and contributed to diverging regional price dynamics. In conjunction with potential US tariffs on trade partners, these developments inject layers of complexity into demand forecasts and shipping routes. Meanwhile, softer oil output projections from US shale producers, prompted by lower prices this year, have lent additional upward momentum to benchmarks.

Central to OPEC+ strategy is ensuring investment resilience in producing countries. UAE highlighted underinvestment concerns, warning that deferred spending could undermine long-term supply stability. The August lift, they argue, responds to both short-term demand and the need to signal commitment to investors. Kuwait pointed to customer outreach as evidence of healthy demand and stressed its competitive edge in terms of low-cost, lower-carbon intensity oil—a differentiator in markets such as China, Japan and South Korea.

Market analysts remain split on the outlook. Enverus Intelligence Research recently contended that prevailing data does not support a bearish narrative, noting flat stock levels in OECD countries, strong seasonal consumption, and resilient cracks. By contrast, energy consultancy FGE flagged the limitations of ramping up production, citing member compliance and infrastructure constraints that may prevent full implementation of quotas—particularly in Iraq and Kazakhstan.

Suhail bin Mohammed Al Mazrouei, Minister of Energy and Infrastructure, reaffirmed the UAE’s full backing for OPEC+ mechanisms, underlining the nation’s commitment to sustaining equilibrium in global oil markets through capacity expansion and coordinated policy.

At the 9th OPEC International Seminar in Vienna on 9 July, Al Mazrouei praised OPEC+ for its collective decision‑making model, which he said ensures production responds to actual market demand rather than price speculation. He noted that the UAE’s strategic investments in expanding production capacity reflect a readiness to release additional oil when consumption trends warrant, providing a stabilising buffer to global supply. The minister highlighted that this expansion aligns with prudent leadership foresight aimed at reinforcing market resilience.

He emphasised that there has been no substantial rise in inventories despite several months of gradual production increases. “Even with the increases…we haven’t seen a major buildup in inventories, which means the market needed those barrels,” he stated. This observation supports broader OPEC+ data showing that successive monthly output increments have been absorbed by demand, a trend that the UAE believes underlines the rationality behind its expanded quota.

Since April, OPEC+ has reversed approximately 2.17 million barrels per day of voluntary output cuts via a phased rollout: 138,000 bpd in April, then 411,000 bpd in each of May, June and July, followed by a proposed 548,000 bpd increase for August – a move reflecting growing market confidence. Notably, the UAE is set to complete a 300,000 bpd quota increase by September, a benchmark reached ahead of the original 2026 timeline as OPEC+ expedited its capacity hike schedule.

Analysts suggest that such robust production gains could recover roughly 2.5 per cent of global demand by September. Al Mazrouei remarked that the UAE’s investments will strengthen its role within OPEC+ and that once additional capacity comes online, it will serve as a crucial stabilising factor during demand shifts.

He further argued that focusing solely on oil price levels is insufficient. Rather, OPEC+ aims to strike a sustainable balance that encourages long‑term investment. “We need the price to be right for investments to happen,” he said, warning of the consequences of underinvestment across producers.

Current market dynamics appear to confirm this approach: data from mid‑June and early July indicate that inventories across OECD nations remained stable despite the production uptick, confirming demand absorption remains robust. That observation, Al Mazrouei suggested, validates the pace of OPEC+ supply restoration and diminishes concern about a looming oversupply.

While output is increasing, policy is cautious. The Group of Eight core OPEC+ members—Saudi Arabia, Russia, UAE, Kuwait, Oman, Iraq, Kazakhstan and Algeria—are proceeding in measured increments. Al Mazrouei underscored that OPEC+ continues to meet monthly via ministerial and committee reviews, carefully calibrating production relative to shifting market fundamentals.

Beyond ensuring balance, the UAE’s production capacity expansion also carries strategic benefits. Having secured a higher individual quota, the country aims to restore and extend its market share. This reinforcement was acknowledged by external observers, including Richard Bronze of Energy Aspects, who noted “the UAE is benefiting from this speeding up of the quota increases” within a context of broader OPEC+ output acceleration.

Despite concerns about slowing economies in key importers, including China, and rising US trade tensions, OPEC+ retains a cautiously optimistic outlook. Prices in July experienced modest one‑per‑cent gains near $69 per barrel following the announcement of the August supply increase—an indicator that demand continues to absorb the additional volumes.

Nevertheless, OPEC+ remains vigilant about macroeconomic risks. Commentators have warned that demand softness later this year, driven by uncertainties in global growth and trade policies, could pressurise prices. Al Mazrouei echoed that view, stressing that short‑term supply increases must be accompanied by stable investment in oil infrastructure to prevent future shortages.

Persistent coordinated production strategy is a central theme from the Vienna seminar. Ministers emphasised OPEC+’s response to shifting fundamentals rather than geopolitical or speculative impulses. With the group moving to complete the unwind of emergency cuts, markets will closely monitor whether global demand continues to match supply advances.

On June 19–20, Baku successfully hosted the Baku ID 2025 Innovation Festival. This year’s theme, The Regional Nexus, brought together leading entrepreneurs and technology leaders from the Caucasus, Central Asia, the Middle East, and North Africa, positioning Azerbaijan as the region’s innovation hub. The festival was organized by SABAH.HUB Innovation Center with the support of the Ministry of Science and Education of Azerbaijan, SOCAR, PASHA Holding, and the Center for Analysis and Coordination of the […]

DoubleDown Interactive has struck an agreement to acquire Hamburg-based WHOW Games GmbH for €55 million, plus up to €10 million in performance-linked earn‑outs, in a move to deepen its foothold in Europe’s expanding social casino market. The transaction, financed from existing cash reserves, is slated to finalise in the third quarter of 2025. The licensing deal, part of a Share Purchase and Transfer Agreement with Azerion Tech Holding B. […]

Advertisements

Shares of Nissan Motor Co. dropped sharply following the firm’s decision to increase its convertible bond issuance to ¥200 billion, up from the initially announced ¥150 billion. The company cited strong investor demand during the book-building process as justification for the upsized deal, though market reaction suggests heightened concerns over shareholder dilution. This convertible debt forms a key part of Nissan’s broader funding strategy, which includes a planned $4 billion […]

Asia‑Pacific digital‑native firms attracted USD 15.4 billion in artificial intelligence investment in 2024, a figure reported by IDC that underscores a shift towards deeper commitments and strategic growth, even as the volume of deals declined.

Capital concentration has intensified as larger funding rounds become the norm. IDC analysts found that while the number of funded AI startups has dropped, the average investment per deal has risen markedly—reflecting investors’ preference for enterprises closer to market maturity rather than early-stage ventures.

China, South Korea, Japan and India remain at the forefront of investment flows. These major markets, with their diverse tech ecosystems and supportive policies, continue to lead, though Southeast Asian nations are gaining traction as both AI adopters and innovators.

Generative AI, a wave propelled by breakthrough models in natural-language processing and image creation, is swiftly ascending as the dominant investment theme across Asia‑Pacific. IDC forecasts that GenAI allocations will more than double by 2028, reaching USD 54.5 billion and forging a new frontier for enterprise transformation.

There is mounting evidence that corporations are pivoting from rhetoric to implementation. Only 29 percent of digital‑native businesses have scaled AI organisation‑wide, yet more than 42 percent now actively pursue co‑innovation partnerships with technology vendors to integrate AI across operations. These collaborative efforts are reshaping collaboration models between AI startups and incumbents.

Costs associated with infrastructure and data security continue to shape investment flows. Enterprise-grade AI demands not only computational muscle but also robust governance frameworks to mitigate risks such as bias, intellectual property leakage and regulatory non‑compliance. Data from the region show that 34 percent of organisations have embedded governance within generative AI software development, an advanced step beyond policy‑level oversight.

Cloud infrastructure providers are doubling down on AI support across Asia‑Pacific. Amazon Web Services announced a USD 13 billion expansion in Australia and over USD 5 billion for a Taiwan region, alongside large‑scale investments in Singapore, Malaysia and Japan. AWS claims the region’s cloud spending will reach USD 250 billion in 2025, largely driven by AI demands.

This inflow of cloud capital is critical in overcoming entry barriers. Local language support, data sovereignty and integration capabilities have become competitive differentiators for these platforms—Microsoft Azure, Google Cloud and Alibaba Cloud are aggressively pursuing similar capacity expansion. Southeast Asia, in particular, is emerging as the fastest–growing regional cloud market globally.

Startups are adapting to investors’ sharper focus on maturity and scalability. Fewer low‑valuation seed rounds are appearing; instead, late‑stage funding for companies with clear product‑market fit, real revenue streams and enterprise traction is dominating. This trend reflects an increasingly risk‑averse capital environment that emphasises depth over breadth.

The build‑up of AI infrastructure is dovetailing with rising regulatory attention. With supervision frameworks being rolled out around sensitive sectors such as finance and healthcare, investors are seeking startups equipped with compliance capabilities. For instance, financial‑services firms are prioritising traceability and governance as mission‑critical components for future‑ready AI deployment.

In geographical terms, growth hotspots vary by stage of AI ecosystem development. China leads in institutional funding and government-backed initiatives. Japan and South Korea benefit from combined strengths in industrial automation, robotics and semiconductor production. India’s vibrant startup landscape is gaining attention, particularly in generative AI and enterprise software. Meanwhile, nations such as Indonesia and Malaysia are attracting more attention as AI adoption becomes a priority for government digitalisation agendas.

Challenges persist. High‑cost infrastructure, skilled‑talent shortages and fragmented regulatory regimes pose constraints. Yet the rise of public‑private coalitions and university‑industry alliances is beginning to address these gaps—skills acceleration programmes are proliferating, and data‑sharing frameworks are gaining traction.

Investors are now looking past headline metrics to evaluate alignment with national AI strategies, such as Japan’s AI strategy and India’s push for indigenous innovation. Locally relevant models—capable of understanding linguistic diversity, cultural contexts, and industry‑specific workflows—are increasingly being favoured over globalised, one‑size‑fits‑all solutions.

This funding environment has spurred momentum in adjacent areas. Edge computing, AI‑enabled cybersecurity, AI‑driven supply‑chain optimisation and health‑tech verticals are emerging as new battlegrounds for both startups and incumbents. These sub‑domains are drawing fresh rounds of investment and pilot partnerships.

Policy trends are also influential. Governments across Asia‑Pacific are advancing data protection frameworks, AI ethics norms and public‑sector adoption plans—all contributing to clearer roadmaps for private‑sector engagement. The interlinking of regulatory reform and capital deployment is strengthening ecosystem resilience.

Investor sentiment remains cautiously optimistic. Surveys suggest that, despite macroeconomic headwinds and geopolitical risk, most executives view cloud and AI as avenues to cost reduction, efficiency gains and differentiation. As AWS’s APAC vice‑president remarked, “AI is the biggest market opportunity since cloud in 2006,” signalling sustained confidence in long‑term upside.

In recent years, Dubai’s real estate market has become one of the most attractive investment destinations globally. With its strategic location, tax-free benefits, and luxury developments, investing in real estate through platforms like Megapolis.ae offers both stability and high potential returns. Why Dubai? Dubai is more than a city — it’s a symbol of modern prosperity, innovation, and luxury living. Thanks to the UAE’s investor-friendly policies, world-class […]

Ruvi AI, a blockchain-based utility token enhanced with artificial intelligence, is garnering considerable attention, with analysts forecasting returns that echo the early days of Ethereum. The presale has raised over $2.2 million, with approximately 180 million tokens sold and more than 2,000 holders already onboard. Priced at $0.015 during Phase 2, the token is expected to rise to $0.07 post-presale, offering investors a near five-fold gain before public trading begins. Market watchers anticipate a $1 valuation after listing—a potential 66× return—or even projections of 104× to 137× in a full bull market.

Security and transparency are strong points. Ruvi AI has undergone a third-party audit from CyberScope, confirming its smart contracts are free from vulnerabilities. A partnership with WEEX Exchange ensures liquidity once the token hits public markets, addressing key investor concerns.

Beyond hype, Ruvi AI distinguishes itself through concrete use cases. In marketing, its AI-driven tools enable precise ad targeting and smarter budget allocation. Within entertainment, blockchain-secured payments and AI audience analytics support content creators. The token also addresses fintech, with applications in fraud detection and secure transactions.

VIP tiers offer additional incentives: Tier 2 at $750 with a 40% bonus, Tier 3 at $2,100 with 60%, and Tier 5 at $9,600 with 100%. These tiers significantly enhance token allocation and potential returns.

Comparisons to established platforms underscore the excitement. Analysts position Ruvi AI as more purpose‑driven than meme coins like Shiba Inu, and liken its structure and transparency to Ethereum’s early roadmap. It is also being cast as a challenger to Ripple and Tron, thanks to its utility-first model and robust security credentials.

Despite enthusiastic projections, sceptics warn that such forecasts often rely on promotional narratives and may underestimate typical crypto volatility. Many articles encouraging investment are sponsored, necessitating cautious interpretation and thorough due diligence.

Market analysts note that Ruvi AI’s clear presale roadmap—starting at $0.015, locked at $0.07, with target of $1—offers an unusually transparent growth trajectory for early investors. Still, experts emphasise that projections of 66× to 137× assume robust market conditions and widespread adoption of AI‑enabled blockchain technology.

Institutional interest is still nascent, yet alignment with AI and blockchain sectors reflects broader tech trends. Continued platform development, ecosystem partnerships, and adoption by key industries will be crucial to validating current projections.

With Bitcoin prices soaring past $100,000 again and investor optimism at a high, the UAE’s strategic push into crypto is paying off. But what does this bull market really mean for the country’s economy, its investors, and its long-term financial future? The UAE has spent the last few years laying the groundwork to become a global crypto capital. While some countries have struggled to regulate or simply […]

XI’s BICKS NO-SHOW: STRATEGIC SHIFT OR SILENT WARNING? CHINESE SYMBOLISM ON CONFIDENCE IN FULL PLAY M A Hossain In the realm of global politics, symbolism matters almost as much as substance. President Xi Jinping of China has decided not to attend this year’s BRICS summit which will be held in Rio de Janeiro. This is the first time President Xi will not be at the summit since […]

By Saifur Rahman Abu Dhabi Chamber of Commerce and Industry (ADCCI), which represents the private sector of the region’s economic powerhouse Abu Dhabi, said, its new three-year strategy announced in 2024 has started to bear fruits as its membership grew 4.9 per cent to 157,207 between September 2024 and June 2025. Since September 2024, ADCCI has hosted 69 business events with government bodies, welcomed 70 trade and […]

SINGAPORE – Media OutReach Newswire – 9 July 2025 – PROPEL with Singlife, the one-stop shared services hub for financial advisory firms, has been named the winner of the highly coveted Insurtech Initiative of the Year – Singapore award at the 10th Insurance Asia Awards, in recognition of its contributions to the insurance industry in Singapore. This accolade – a first for PROPEL since its official launch […]

Kuwait Investment Authority, the sovereign wealth fund managing over US $1 trillion in assets, has divested a US $3.1 billion stake in Bank of America, according to sources familiar with the unregistered block trade. The shares were sold at US $47.95 each—at the bottom of Goldman Sachs’s marketed range—underscoring a strategic move to liquidate a long-held position. The sale marks a notable shift from the fund’s crisis-era backing of Merrill Lynch. In […]

Continues to see strong growth in traditional powerhouse sectors such as automotive, technology and e-commerce Sees new opportunities in Malaysia for growth in life sciences and healthcare as well as new energy DHL is well-positioned to support Malaysia’s trade and logistics ambitions with expanded investments and capabilities KUALA LUMPUR, MALAYSIA – Media OutReach Newswire – 9 July 2025 – DHL, the world’s leading logistics provider, has reaffirmed […]

Dubai’s ultra‑luxury real estate market surged in April to June 2025, with transactions for homes priced above $10 million reaching US $2.6 billion, a 37 % rise from the previous quarter and a 63 % increase year‑on‑year, according to London‑based researcher Knight Frank. The emirate recorded 143 such deals in Q2, up from fewer in Q2 2024, underscoring its dominance in the global super‑prime segment. Palm Jumeirah held its status as the top destination […]

Dubai‑based hospitality firm Tashas Group is entering a rapid new phase of expansion across the Middle East and South Africa, with founder Natasha Sideris spearheading a strategy that balances boutique charm with accelerated growth. Operating 40 venues in five countries—including 18 in South Africa, 17 across the UAE, three in Saudi Arabia, and single locations in Bahrain and the UK—the group plans to open a further 15 […]

European luxury houses are experiencing a marked shift, with faltering Chinese demand prompting a strategic pivot toward alternative markets and refined brand positioning. According to Bain & Co, global personal luxury goods sales are projected to contract by 2–5 per cent in 2025, following a €364 billion market in 2024, suggesting prolonged headwinds in China and weakened consumer confidence across key economies. Concurrently, LVMH reported a 5 per cent decline in fashion and leather goods, while Kering’s Gucci saw a 24 per cent slump in Q3 2024—underscoring the drag from Chinese spending.

Amid this slowdown, brands are accelerating efforts to broaden geographic reach. McKinsey projects that the US luxury market will grow by 4–6 per cent annually through 2027—outpacing China and Europe—and emerging regions such as the Middle East, Latin America and Southeast Asia are gaining traction as bright spots. Evidence of reorientation is visible: LVMH is expanding its US production capacity, and Kering, Hermès and Prada are intensifying investment in North America.

Not all brands are equally affected. Brunello Cucinelli, less exposed to Chinese consumption, disclosed robust sales forecasts—upgrading its annual growth outlook to 11–12 per cent based on strong European demand and continued traction among ultra-high-net-worth clients. Hermès, too, has weathered the storm, maintaining sales growth while peers grapple with revenue declines.

The luxury slowdown in China is rooted in multiple structural challenges. Economic growth has softened below 5 per cent, real estate woes persist, and shifting demographic trends have eroded consumer sentiment. Simon‑Kucher reports that many Chinese consumers are becoming cost-conscious, displaying a polarization between aspirational and high-end luxury buyers, and embracing domestic brands as alternatives. Particularly, cultural shifts—such as “luxury shame”—have fuelled a move toward discretion and frugality in visible consumption.

Although major international houses such as Chanel and Dior continue to engage Chinese consumers through culturally attuned storytelling—launching region‑specific collections and targeted local campaigns—some smaller brands have shuttered stores in mainland China, acknowledging a recalibration of in‑market commitment.

Domestic luxury players are also benefitting from this transition. Laopu Gold, a jewellery brand rooted in traditional Chinese symbolism, has doubled same‑store sales and quadrupled online revenue this year, with a market valuation exceeding HK$170 billion, thereby challenging European incumbents—though its international footprint remains limited.

Global brands recalibrating their China approach are employing a range of strategic pivots: tighter inventory control to avoid discounting and preserve brand equity; stimulant-focused aspirational campaigns; and product diversification into understated luxury or second-hand luxury to resonate with new consumer segments. The second‑hand luxury market in China alone has grown at an annual rate exceeding 30 per cent since 2020.

Europe itself remains central to the luxury ecosystem, as evidenced by European markets holding nearly half of Armani’s revenues in 2024—an increase relative to Asia Pacific’s diminished share—while the group strategically channels investment into flagship stores and digital-commerce. Cost control, brand consistency, and quality-focused messaging have become priorities as demand becomes more selective.

Globally, brand strategies are evolving with renewed emphasis on sustainability, resilience and storytelling. Price hikes once driven by so‑called “greedflation” are now tempered, with average increases forecast at 3.5 per cent in 2025—lower than peak levels—and justified by genuine craftsmanship and material innovation. Product lines are being refined: leather goods, jewellery and beauty segments are poised for stronger performance, while deeper integration of sustainability and consumer‑centric narratives is prioritised.

Brands are also investing in localisation in other markets and exploring omnichannel retail strategies. Digital-owned channels, experiential stores, and culturally sensitive campaigns are being deployed to engage consumers in tier‑2 and tier‑3 urban centres, particularly in Asia outside China.

European luxury houses are at a strategic inflection point: with the decline in Chinese demand now measurable, success hinges on geographic rebalancing, product portfolio refinement, inventory discipline and culturally resonant marketing. The winners will be those able to preserve brand prestige while adapting to economic reality and evolving consumer psychology across diverse global markets.

Iran has achieved its highest energy output in nearly half a century, as crude production and exports continue expanding despite escalating tensions and Western sanctions. In 2024, total oil output—including crude and gas liquids—reached approximately 5.1 million barrels per day, marking levels unseen since before 1978. Indicators from the first half of 2025 signal further growth, reinforcing Tehran’s stance that its energy sector remains resilient even under pressure.

China remains the principal destination for Iranian crude. According to Vortexa and Kpler data, Beijing imported an average of 1.4 million bpd of Iranian crude and condensate during the first half of 2025. In June alone, Chinese imports surged to a record 1.8 million bpd, exploiting floating storage reserves accumulated previously.

Despite U. S. legal restrictions, these volumes endure through intricate shipping methods and discounts. As of June, Iranian crude was being sold to China at discounts of $3.30–$3.50 per barrel below Brent—the widest spread since 2023—partly triggered by weak demand from independent Chinese “teapot” refineries and additional U. S. sanctions on mid-tier processing firms in Shandong province. Refineries such as these have cut utilisation rates to around 51 per cent, down from 64 per cent last year.

Iran’s export capacity has been safeguarded by infrastructural alternatives designed to bypass the Strait of Hormuz. The Goreh‑Jask pipeline and Jask terminal—capable of exporting around 300,000 bpd—offer strategic flexibility, although actual utilisation fell to under 70,000 bpd in late 2024. Elsewhere, Saudi Arabia and the UAE have also enhanced their own bypass routes through the Strait to mitigate risk.

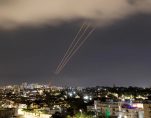
Nonetheless, current events pose fresh challenges. Israeli strikes in June damaged parts of oil infrastructure near Tehran and affected the South Pars gas field—responsible for up to 700,000 bpd of condensate. Exports from key terminals such as Kharg Island briefly dropped below 120,000 bpd from a weekly average of 1.7 million bpd. However, Iran manages significant stockpiles—approximately 27.5 million barrels afloat—that can sustain exports for weeks.

Domestic dynamics complicate this energy story further. Iran’s gasoline consumption has outpaced refining capacity by nearly 15–20 per cent since late 2024, triggering reliance on reserves and imports to fill shortfalls. Peak summer demand reached unprecedented levels, surpassing 143 million litres in a single day. Panic-buying followed some military strikes, exposing strains in planning and supply.

Iran’s global energy standing aligns with broader market projections. The International Energy Agency forecasts that global oil supply will exceed demand in 2025 by around 1.8 million bpd, a backdrop that may soften impacts from Iranian output. At the same time, discussions in Washington about lifting U. S. sanctions have raised concerns in Beijing, particularly for its fragmented independent refining sector. Analysts warn that a sudden lifting of sanctions could flood global markets—with an additional 500,000 bpd of Iranian oil—and undercut smaller Chinese players by crushing their margins.

Iran’s energy strategy shows calculated resilience. While nuclear tensions invite military risks, the oil ministry appears intent on diversifying markets, expanding infrastructure, and leveraging geopolitical leverage. Iran Daily reported that production comprised 4.3 million bpd of crude plus around 0.7 million bpd of other liquids in 2024. Analysts advocate that increased domestic use, ageing facilities, and investment gaps could temper the pace of future gains unless Tehran secures long-term funding and technical partnerships.

Observers note the inherent paradox: Iran continues ramping production even as global energy security faces renewed uncertainty. Control over chokepoints such as the Strait of Hormuz remains central. Although no full closure has occurred—the Iranian parliament proposed closure in late June pending council approval—the symbolic threat alone underlines Tehran’s strategic positioning. Global markets, buoyed by inventories and diversified routes, have so far absorbed the shock. Yet any escalation could rapidly unsettle thresholds.

HONG KONG SAR – Media OutReach Newswire – 8 July 2025 – In a bold move to meet soaring global demand for faster, leaner e-commerce fulfillment, Printbelle today announced major expansions to its production capabilities and product catalog, positioning itself as a leading force in the print-on-demand (POD) revolution. The company’s advanced 10,000㎡ facility in Fujian now delivers over 850 customizable products with 24–72 hour production times—helping […]

Matein Khalid Sri Lanka is one of the most fascinating and drop-dead gorgeous countries I have ever visited, the island once known as Serendip by ancient Umayyad Arab sailors/ruby merchants and Ceylon by the colonial Dutch and British who once ruled the island, an emerald tear drop in the Indian Ocean. I have a special bond with Sri Lanka because my late mother, an artist, used to […]

Sterling’s recent rally has little to do with the UK economy suddenly outperforming expectations. It has everything to do with the dollar falling out of favour. When the pound hit $1.365 this week—its strongest level since early 2022—it was a flashing red signal that international investors are losing faith in the greenback. Let’s not pretend this is about interest rates. The Federal Reserve is still holding firm, […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA