News related to
growth

DP World Trade Finance has crossed the $1 billion threshold in working capital provided to businesses in emerging markets, marking a significant milestone just four years after launching its integrated logistics-finance platform. The achievement reflects growing momentum behind digital trade finance solutions aimed at bridging the $2.5 trillion global trade finance gap, which continues to weigh heavily on small and medium-sized enterprises in developing economies. The platform, […]

HONG KONG SAR – Media OutReach Newswire – 24 July 2025 – Recently, DL Holdings Group (1709.HK) has entered into strategic cooperation agreements with ViaBTC, Asseto, and Rich Dragon Consultants, while actively advancing the tokenization of HK$500 million in assets for the DL Tower. These initiatives have sparked significant market attention, with the stock price surging over 70% in a single day. On July 23, DL Holdings […]

UAE equity capital markets are poised for an uptick in activity, with Citi forecasting three to five initial public offerings by 31 December—assuming timely regulatory clearance and robust pre‑marketing, said Rudy Saadi, Citi’s managing director and head of MENA Equity Capital Markets. This comes amid renewed investor enthusiasm as the nation positions itself as a regional IPO hub.

Saadi noted that although privatisations have slowed, market sentiment remains firmly positive for the remainder of 2025 and into early 2026. The expected pipeline includes a mix of family‑owned concerns and state‑affiliated enterprises alongside follow‑on offerings from listed firms.

Delivering context, UAE exchanges have tapped international and domestic liquidity in recent quarters. Spinneys and Alef Education raised $375 million and $515 million, respectively, in the second quarter, channelling nearly $890 million overall through new IPOs. Dubai and Abu Dhabi exchanges continue to push private‑sector listings, underscoring wider capital‑markets evolution.

Citi’s optimism is reinforced by Bloomberg’s observation of renewed momentum in regional share sales heading into H2 2025. The uptick appears linked to improved regulatory frameworks, deeper secondary‑market liquidity and evolving investor appetite across institutional, family‑office and retail segments.

Market analysts point to several emerging trends. Firstly, regulatory authorities in both Dubai and Abu Dhabi are progressively enhancing governance and foreign‑ownership rules to attract global participants. UAE entities now find listing conditions more competitive compared with established markets in Europe or the US.

Secondly, a shift is apparent from state privatisations to private‑sector flotations. Family‑owned businesses and tech‑focused enterprises are now stepping into the spotlight—supported by increasing liquidity and appetite from international institutional investors.

Thirdly, follow‑on share sales are gaining traction, offering listed firms a refundable route for fresh capital without navigating a full IPO process. Analysts expect more such offerings in sectors including financial services, healthcare and logistics, reflecting healthier balance sheets and growth trajectories among UAE firms.

Beyond sheer numbers, quality is a key consideration. Saadi indicates that approval pace and pre‑marketing success are decisive factors. In prior cases, such as Spinneys and Alef Education, strong institutional subscription signalled robust investor interest—suggesting forthcoming listings may mirror this level of demand.

Banking and asset‑management houses in the region—among them Citi, EFG Hermes and Emirates NBD Capital—are reportedly managing a cohort of potential issuers. EFG Hermes projected a busy second half of 2025 across Saudi Arabia and the UAE, with several consumer‑focused businesses preparing to list.

This momentum positions the UAE to lead IPO activity across the Middle East. In 2024, Gulf IPO volumes reached multi‑billion‑dollar levels; UAE exchanges, buoyed by sizeable debuts like Talabat’s Dh1.6bn listing in November 2024, claimed top status in IPO fundraising for three consecutive years.

Looking ahead, investor appetite appears steady, albeit cognisant of broader economic headwinds, including global interest‑rate trajectories and geopolitical uncertainties. Saadi stressed the significance of sentiment over macroeconomic factors when gauging regional appetite, citing Middle Eastern equity capital market resilience.

Key players set to define the coming wave include family‑owned conglomerates deliberating partial listings, firms in consumer and tech verticals exploring exit paths, and existing public companies seeking growth capital via follow‑on offerings. Leading financial houses continue to harmonise local issuers with global investor pools.

Global oil consumption has shifted, with demand now peaking in the third quarter instead of the traditional fourth, signalling a structural change reshaping markets during the summer months. Analysts point to stronger consumption from Asia—particularly China and India—alongside diminished heating fuel use in advanced economies as key drivers behind this trend, which carries significant implications for trading patterns, strategic reserves and pricing dynamics.

Industry data show that consumption of heating oil and kerosene in wealthy nations has declined steadily. In the US, fewer households rely on refined petroleum for heating—dropping from 17 % in 1990 to just 9 % today—while Europe has seen even steeper falls. Conversely, jet fuel use during Northern Hemisphere summers has grown, especially as holiday travel resumes. This has pushed demand peaks into July–September, reversing a long-standing seasonal rhythm.

Fuel consumption patterns in emerging economies present a stark contrast. Many countries, including those closer to the equator, rely on oil year-round for industrial power, electricity generation, and water desalination. Saudi Arabia, for instance, burned over 800,000 barrels per day of crude in just one summer to power air conditioning—a volume comparable to Belgium’s entire daily petroleum demand.

Climate change compounds the shift. Milder winters reduce heating demand, while hotter summers elevate energy needs for cooling and travel. In 2025 so far, global oil consumption in the third quarter is projected to exceed fourth-quarter levels by approximately 500,000 barrels per day—the fifth recorded year this has happened since 1991.

This transformation carries consequences for market tightness and pricing. Although OPEC+ and rising non‑OPEC output have attempted to balance supply, physical markets appear increasingly tight during summer months. In mid-July, Brent crude hovered in the mid‑US$60s, reflecting supply constraints despite softening from spring lows. Speculative traders, noting robust seasonal demand, have also increased their net long positions in Brent and gasoil contracts.

Asia’s role has been pivotal. China ramped refinery runs to over 80 % of capacity in June—the highest levels in five years—as stockpiling alongside consumption drove strong throughput. Meanwhile, Asia’s crude imports rose by around 510,000 bpd in the first half of 2025, underscoring the region’s impact. Despite cautious forecasts from the IEA and OPEC—projecting crude demand growth of 700,000 bpd and 1.29 million bpd respectively—actual refinery intake and imports suggest potential underestimation.

India’s fuel consumption trends provide further insights. June data from the Petroleum Planning and Analysis Cell show fuel demand was 20.31 million tonnes—down 4.7 % from May but up 1.9 % year-on-year—reflecting monsoon-related dips typical through August and September. Diesel usage, especially linked to industry and logistics, is a key part of India’s expanding consumption profile.

OPEC+ has responded to these dynamics. In August, the alliance approved production increases of roughly 548,000 bpd aiming to satisfy peak Q3 demand. Simultaneously, US shale output remains robust; American producers reported nearly 13.5 million bpd in April, although well completion rates have slowed, reflecting the dependency on prices.

Nevertheless, the market outlook grows more uncertain as it heads into fourth quarter. The EIA forecasts OECD inventories will build to 62 days’ worth of supply in the second half of 2025—rising further to 66 days by end-2026—signalling a potential surplus as summer demand wanes. EIA projections for 2026 also expect US production to decline, with WTI prices retreating toward US$53 per barrel.

Pricing reflects this shift. Oil markets have shown summer tightness in 2025, but expectations for a Q4 surplus weigh on medium-term prices. The IEA forecasts refinery throughput will drop from a projected August peak of 85.4 million bpd to about 81.7 million bpd by October, implying weaker demand later in the year.

The shift in seasonality thus becomes a critical market pivot. Traders, refiners and producers must recalibrate strategies around production schedules, storage cycles and investment decisions. Q3 now demands heightened vigilance—from physical balancing to hedging strategies—while Q4 may require reassessment of storage utilisation and pricing risk.

Emerging Markets Become the “Blue Ocean” for Enterprises Going Global SHANGHAI, CHINA – Media OutReach Newswire – 23 July 2025 – XTransfer, the World’s Leading & China’s No.1 B2B Cross-Border Trade Payment Platform, announces that its global enterprise customer base has exceeded 700,000. This significant milestone highlights the platform’s remarkable achievements in supporting small and medium-sized enterprises (SMEs) to expand globally. As a global leader in the […]

Highlights 39% underlying earnings growth Increased contributions from associates, Health & Beauty and Food Health & Beauty delivered strong like-for-like (LFL) sales growth of 4% Portfolio simplification continues with the announced divestment of Singapore Food business and sale of minority stake in Robinsons Retail Proceeds from Yonghui and Robinsons Retail divestments strengthen balance sheet to a net cash position of US$442 million Raised full-year underlying profit guidance […]

New Research Reveals US$130 Billion Economic Opportunity and Outlines Policy Framework to Accelerate Regional Digital Leadership by 2030 SINGAPORE – Media OutReach Newswire – 22 July 2025 – The Lee Kuan Yew School of Public Policy (LKYSPP) today released a comprehensive research report outlining how ASEAN can harness 5G and artificial intelligence convergence for transformative economic growth. The study, “Leveraging 5G to Accelerate AI-Driven Transformation in ASEAN: […]

Advertisements

Global crude consumption is now cresting in the third quarter rather than the fourth, as China and India’s surging summer demand upends decades of winter-driven market patterns. The reversal of the traditional seasonality, first observed around 2015, is being amplified in 2025, with implications for supply strategies, prices and refinery operations worldwide. OPEC’s July report highlights strong refinery throughput in June, with intake rising by 2.1 million bpd—clear evidence […]

Islamic-aligned transactions in the UAE soared to US $1.53 billion between 2023 and 2024, securing its position as the second-most active market after Indonesia in the global Sharia-compliant investment landscape. These figures, shaped by 50 deals covering mergers and acquisitions, private equity, and venture capital, are drawn from the 11th State of the Global Islamic Economy report by DinarStandard. Indonesia led this period with 40 deals amounting to US $1.60 billion, […]

Fintech firm Qlub has raised $30 million in a funding round aimed at accelerating its global expansion and deepening its technological capabilities. The Dubai-based startup, known for digitising the dining experience, has drawn strong investor interest as it scales operations across Asia, the Middle East, and other international markets. The funding round was co-led by UAE-headquartered Shorooq Partners and Berlin-based Cherry Ventures, marking a cross-border vote of […]

Titan Company has struck a deal to acquire a 67% stake in Dubai-headquartered luxury jeweller Damas from Qatar-based Mannai Corporation in a transaction valued at 1.04 billion dirhams, or approximately $283.2 million. The move is poised to significantly strengthen Titan’s footprint in the Gulf region, positioning the Tata Group company among the largest subcontinent-origin jewellery players operating in the Middle East.

The acquisition agreement, announced on Monday, marks a pivotal expansion for Titan beyond its current presence in the UAE, where it has operated under the Tanishq brand since October 2020. The transaction is expected to close by 31 January 2026, subject to regulatory approvals and customary closing conditions. Titan will also retain an option to purchase the remaining 33% equity in Damas after 31 December 2029, effectively laying the groundwork for full ownership over time.

The deal will give Titan direct access to Damas’ well-established network of 146 outlets across the six Gulf Cooperation Council nations — United Arab Emirates, Saudi Arabia, Qatar, Oman, Kuwait, and Bahrain. With only seven Titan-operated Tanishq stores currently open in the region, the acquisition presents a strategic leap in scale, market share, and regional brand visibility for the Bengaluru-based jeweller.

Damas, founded in 1907, is one of the most recognisable names in the Middle East’s luxury jewellery market. It has developed a reputation for catering to the region’s taste for high-end gold and diamond jewellery, and is known for its broad in-house product range and partnerships with international luxury brands. Mannai Corporation, which has owned Damas since 2012, has been looking to streamline its portfolio, prompting the divestment.

For Titan, the acquisition offers both a fast-track into the premium Gulf retail market and an opportunity to accelerate synergies across procurement, branding, and customer experience. The company is expected to retain Damas’ brand identity and existing management structure, allowing the Dubai-based business to continue leveraging its established reputation while benefitting from Titan’s supply chain and operational expertise.

The Middle East has been a target market for Titan’s international ambitions, driven by the strong presence of the South Asian diaspora and a deep-rooted cultural affinity for gold. The GCC region’s jewellery market is estimated to be worth over $10 billion, with gold accounting for a large share of consumer demand. Analysts view Titan’s acquisition of Damas as a strategically sound move in an environment where cross-border consolidation is becoming increasingly common in luxury retail.

Titan has grown to become one of the most dominant jewellery retailers in South Asia through its flagship brand Tanishq, which is positioned as an accessible luxury label offering a blend of traditional and contemporary designs. The company also operates sub-brands such as Mia and Zoya, each catering to specific consumer segments. Over the past decade, Titan has expanded into new domestic categories and entered select global markets, but the Damas deal marks its most ambitious international push yet.

The acquisition is being viewed by market observers as a significant play within the broader Tata Group strategy of boosting global brand equity across consumer-facing businesses. Following the group’s international expansions in hospitality, automotive, and technology, Titan’s move consolidates Tata’s multi-sectoral presence in the Gulf and taps into a region with rising demand for premium lifestyle offerings.

Financial analysts have underscored the deal’s strategic value, citing Damas’ established customer base and premium positioning, which could drive faster break-even timelines than greenfield expansion. Furthermore, the GCC’s favourable demographic trends and consistent gold demand have added to investor optimism around the deal’s long-term prospects.

Despite geopolitical uncertainty and fluctuations in gold prices, jewellery retail in the Gulf continues to enjoy high volumes due to cultural norms and steady tourist inflows, especially in the UAE. Titan’s increased footprint through Damas will place it in a better position to cater not just to residents but also international shoppers across the region’s major commercial and tourist hubs.

Titan has confirmed that the acquisition will be funded through internal accruals and debt, with no equity dilution expected in the near term. The company’s board has approved the investment, and the transaction is aligned with its long-term capital allocation strategy.

Executives at Titan have expressed confidence in Damas’ future growth trajectory and have indicated that the company will invest further in marketing, store refurbishment, and digital initiatives to modernise the customer journey. Damas’ product portfolio, which includes bridal sets, heritage pieces, and limited-edition designs, will remain intact as Titan aims to preserve the local flavour while infusing global best practices.


By nurturing talent and cultivating a high-impact culture, ONYX redefines hospitality excellence. BANGKOK, THAILAND – Media OutReach Newswire – 22 July 2025 – ONYX Hospitality Group, a leading hospitality management company in Southeast Asia, specialising in luxury hotels, resorts, serviced apartments, and residences, underscores its commitment to human resource development, reaffirming its belief that “people” are at the core of the hospitality and service industry. The company […]

By Pinarayi Vijayan The life of Comrade VS Achuthanandan who passed away at the age of 101 on Monday is a remarkable chapter in the history of Kerala in general and the revolutionary movement here in particular. Comrade VS Achuthanandan was a symbol of a brilliant tradition of struggle, extraordinary determination and uncompromising fighting stance. […]
A consortium led by Air Arabia and partners Nesma Group and KUN Holding has secured approval from Saudi Arabia’s General Authority of Civil Aviation to establish and operate a low‑cost carrier based at King Fahd International Airport in Dammam. The airline is expected to begin operations in 2026, with a fleet of 45 aircraft serving 24 domestic and 57 international destinations by 2030. GACA projects the carrier will transport […]

We’re at an all-time high for the S&P 500 right at the beginning of earnings season. If we can get through this earnings season with not too many major failures, this upward current momentum that we have in the market, is likely to continue. It’s tempting to call this a pause for breath—but make no mistake, what follows could determine whether bulls stay in control. With 59 S&P 500 […]

HONG KONG SAR – Media OutReach Newswire – 21 July 2025 – Chengdu Kanghua Biological Products Co., Ltd. (Stock Code: 300841.SZ) announced that Shanghai Healthcare M&A Fund (“the M&A Fund”) intends to acquire the Company through a strategic agreement. Leveraging its substantial resource and financial strength, the M&A Fund plans to support Kanghua Biological’s established product portfolio, accelerate sales of its mature products, and develop industry synergies […]

Dubai’s real estate market achieved a landmark surge during the first half of 2025, with transactions climbing 26 per cent to 125,538 and total value reaching AED 431 billion—an increase of 25 per cent year‑on‑year. The performance underscores the emirate’s growing appeal to both local and international investors.

Investor activity gathered notable momentum, with approximately 94,700 individuals completing transactions worth AED 326 billion—39 per cent more than a year earlier. Of this group, 59,075 were first‑time investors, injecting AED 157 billion and marking both a growth in investor numbers and value. UAE residents constituted 45 per cent of this cohort, signalling effective measures to convert renters into homeowners.

Women also bolstered the market’s resilience, executing nearly 35,000 transactions worth AED 73.2 billion. Meanwhile, foreign investors led contributions at AED 228 billion, with Arab and GCC nationals contributing AED 28.4 billion and AED 22.6 billion respectively.

Residential and luxury segments showed marked performance. Al Barsha South Fourth recorded the highest transaction volume, followed by Al Yalayis 1 and Wadi Al Safa 5. In terms of value, Dubai Marina topped the list with AED 25.1 billion, followed by Business Bay, Burj Khalifa zone, and Palm Jumeirah.

ValuStrat’s H1 property index reported that unbuilt villas now command values 66 per cent above their 2014 peaks and 175 per cent above post‑pandemic levels. Apartment prices rose 1.1 per cent month‑on‑month, translating to annual growth of 20 per cent, notably in The Greens, Dubai Silicon Oasis, Dubailand Residence Complex, Palm Jumeirah, and Town Square—all exhibiting capital gains of over 22 per cent.

Parallel to sales growth, rental price inflation decelerated mid‑year: by May, annual residential rent increase eased to 8.5 per cent from 14.3 per cent in January. Cavendish Maxwell attributed this moderation to the delivery of approximately 9,300 new units in Q1 and the introduction of the “New Smart Rental Index,” which is influencing both landlord expectations and market dynamics.

Mortgage activity reflected evolving buyer preferences. Data from DXB Interact indicates a 38 per cent rise in loan volume, although total mortgage value dipped by 8 per cent—signalling a shift towards cash purchases or smaller financing commitments. Off‑plan sales stood strong at 64,907 transactions, with a total value of AED 209.1 billion. Resale transactions numbered 34,150, valued at AED 119.7 billion.

Amid this buoyancy, caution flags exist. Fitch Ratings warns of potential double‑digit price corrections—up to 15 per cent—in late 2025 and 2026, due to an expected supply surge of around 210,000 units. The agency nevertheless noted that banks and developers have reduced exposure and are poised to manage potential adjustments.

Planning authorities have responded proactively. Dubai intends to add 73,000 homes in 2025, targeting a total of 300,000 new units by 2028—efforts aimed at aligning supply with investor momentum and population growth. Meanwhile, ongoing state‑led consolidation of developers, regulatory improvements under the Economic Agenda D33, and the Dubai Real Estate Strategy 2033 continue to underpin structural confidence.

As forecasted by ValuStrat, property price growth may moderate but remain positive—potentially adding another 10 per cent by the end of 2025 as market dynamics evolve. The challenge now lies in balancing supply expansion, evolving mortgage behaviour, and price stability to sustain long‑term viability for investors and residents alike.

Foreign institutional investor activity has slowed, but India’s equity market is gaining a new level of sophistication thanks to the rapid emergence of long‑short strategies among domestic analysts. With regulatory approval of the Specialised Investment Fund route and increasing recognition of sell‑side research, analysts in India are setting new standards, outperforming peers in major global markets.

At the centre of this shift are flagship long‑short funds, enabled by an April amendment that allowed mutual funds to engage in both long and short equity positions via the SIF framework. Industry leaders such as ICICI Prudential, SBI, Quant and ITI Mutual Funds are among the first to roll out these products. This structural innovation, viewed by asset managers as a game‑changer, allows strategic hedging and enhanced alpha generation in volatile conditions.

Jatinder Pal Singh, CEO of ITI Mutual Fund, identifies the move as a watershed moment: “We see a lot of potential in this category similar to what we have seen in alternative investment funds…”. Quantitative and hedge fund entrants—AlphaGrep, Abakkus and Carnelian—are also applying for SIF licences, signalling a rising tide of systematic strategies.

The surge in long-short offerings emerges against a backdrop of changing investor sentiment and derivative market structures. While proprietary traders and retail continue to dominate derivatives trading—accounting for 52.3% and 33.6% respectively—domestic institutional participation remains minimal at just 0.2%. The launch of these funds is expected to usher in broader institutional adoption, reducing reliance on speculative flows.

Simultaneously, foreign players are reassessing their exposure. Citigroup downgraded Indian equities to “neutral” citing stretched valuations and slower earnings growth. Bank of America has flagged valuation concerns as part of seven headwinds to near‑term market performance, though it remains bullish on India’s long‑run structural strengths. Morgan Stanley echoes this optimism, describing the market as undervalued and promising for patient investors.

At the nexus of these developments, sell‑side analysts play a pivotal role. Their long‑short models provide more nuanced insights, enabling differentiated strategies compared to conventional long‑only approaches. This evolution mirrors practices in advanced markets, where close analyst coverage is integral to informed decision‑making.

International observers are taking note. Carson Block, known for his critical research into Chinese markets, is considering launching a long‑short or long‑only fund in India, citing opportunities in corporate transparency and leveraging tax-friendly jurisdictions like GIFT City. His interest signals growing confidence in the depth and potential of India’s equity ecosystem.

The broader equities landscape reflects these shifts. Foreign institutional investors are ramping up bearish positions in derivatives, signalling caution amid valuation concerns and global uncertainties. Concurrently, new equity supply is expanding, with a surge in IPOs and share sales reflecting a 14% rise in benchmark indices over the preceding six months. Analysts warn that without strong institutional demand, this wave may trigger volatility.

Experts argue the timing could not be better for long‑short funds. As valuations plateau and geopolitical uncertainty remains — including Middle East tensions affecting crude prices — the ability to manage risk through hedging becomes decisive. Fund managers are betting that structured strategies will better manage these headwinds.

At the same time, India’s growing affluent class—from double‑digit income growth to rising equity allocation—adds tailwinds. Wealth managers like 360 One are expanding advisory services amid rising assets under management, reflecting the country’s broader push toward financial sophistication. The development of long‑short funds aligns with these trends, offering differentiated solutions to high‑net‑worth investors seeking yield in uncertain markets.

Yet challenges remain. Institutional engagement in derivatives must scale meaningfully to support product viability. Regulators and market infrastructure will need to adapt, ensuring transparency and risk‑management frameworks keep pace. Moreover, investor education is critical; long‑short strategies are complex and require a clear understanding of leverage, margin risk and counterparty exposures.

Nonetheless, the direction is clear: Indian equity markets are transitioning from conventional long‑only investing to embrace multi‑directional strategies, leveraging deep local research and structural innovation. With the SIF framework opening doors for long‑short funds, analysts are stepping into roles once reserved for global peers. As Citi tones down enthusiasm and global investors tread cautiously, India’s analysts are sharpening tools that could redefine the domestic landscape—and perhaps export this model abroad.

Al‑Futtaim Retail has agreed to acquire a 49.95 per cent stake in Cenomi Retail from major shareholders for about SAR 2.52 billion, signalling a major strategic shift in Saudi Arabia’s retail sector. The agreement, unveiled through a statement on Tadawul today, July 20, 2025, also includes a conditional shareholder loan to boost Cenomi’s balance sheet.

Under the share purchase agreement signed on July 18, Al‑Futtaim would purchase approximately 57.33 million shares from the Alhokair family, Saudi FAS Holding and FAS Real Estate at SAR 44 per share. Completion hinges on regulatory clearance and execution of a parallel SAR 1.3 billion loan agreement aimed at shoring up working capital.

Al‑Futtaim, a UAE conglomerate with a broad portfolio spanning franchising, automotive, real estate and financial services, brings deep retail expertise and a strong track record with global brands. Its investment is expected to stabilise Cenomi’s liquidity, support operational continuity and bolster its capacity for expansion.

Cenomi Retail, part of Fawaz Abdulaziz Alhokair Co., has navigated a challenging turnaround. It holds the largest brand portfolio in Saudi Arabia, operating over 800 stores across eight countries and managing more than 85 international brands, including Zara under a long-term agreement with Inditex. The firm successfully launched a landmark Zara concept store in Riyadh in December 2024, integrating digital and physical retail channels.

Despite these strengths, Cenomi has suffered persistent financial strain. It reported a SAR 1.1 billion net loss in 2023 amid deteriorating margins, asset write-downs and weakening equity. Total assets collapsed by 36 per cent to SAR 4.6 billion by end‑2024, while shareholder equity turned negative – warning signs that triggered restructuring efforts in 2024.

In response, Cenomi embarked on an aggressive restructuring: disposing of non-core brands and outlets, offloading 16 franchises in early 2024, divesting five further brands with 121 stores to Abdullah Al Othaim Fashion Co. in October, and appointing Salim Fakhouri as CEO. The divestments, totalling SAR 2 billion, aimed to streamline operations around “champion” brands like Zara. By mid‑2024, losses had mounted to SAR 1.5 billion.

Earlier this month, Cenomi confirmed it was in talks to bring in a strategic investor for nearly half its capital, accompanied by a shareholder loan. Today’s announcement reveals that investor as Al‑Futtaim, although final terms on the loan are still under discussion.

The deal aligns with broader growth trends in Saudi Arabia’s retail sector, which is projected to expand at roughly 7.1 per cent CAGR through 2029. Economic diversification under Vision 2030, expanding consumer spending and rising tourism are driving omnichannel retail innovation. Cenomi’s launch of cenomi. com and its O2O model position it to capitalise on these trends, though profitability remains a concern.

Analysts have flagged Cenomi as a high-risk, high-reward prospect. With a forward P/E of around 14.3x and a weak operating margin, its distressed balance sheet raises concerns over equity dilution. However, sustained operational cash generation—SAR 1.3–1.4 billion annually—suggests underlying business viability.

Al‑Futtaim’s entry provides a critical capital injection that could stabilise Cenomi’s finances and underpin its digital expansion. Industry observers note that Majid Al Futtaim and Emaar have successfully executed omni-channel models in the region; Al‑Futtaim’s deep supply chain know-how and brand partnerships could replicate that success in Saudi markets.

Following deal closure, which remains subject to approvals, Al‑Futtaim will command nearly half of Cenomi’s share capital and will have extended a substantial shareholder loan. The injecting of both capital and expertise is expected to bolster Cenomi’s capability to restore profitability and reclaim market leadership.

Arada Developments, the Sharjah-based property developer, is preparing to raise up to $500 million via an Islamic bond as it joins a wave of Gulf real estate firms turning to debt markets to fund expansion. The group plans to launch the issuance next week to finance new land purchases and capitalise on a construction surge across the United Arab Emirates. The proposed sukuk issue represents a strategic […]

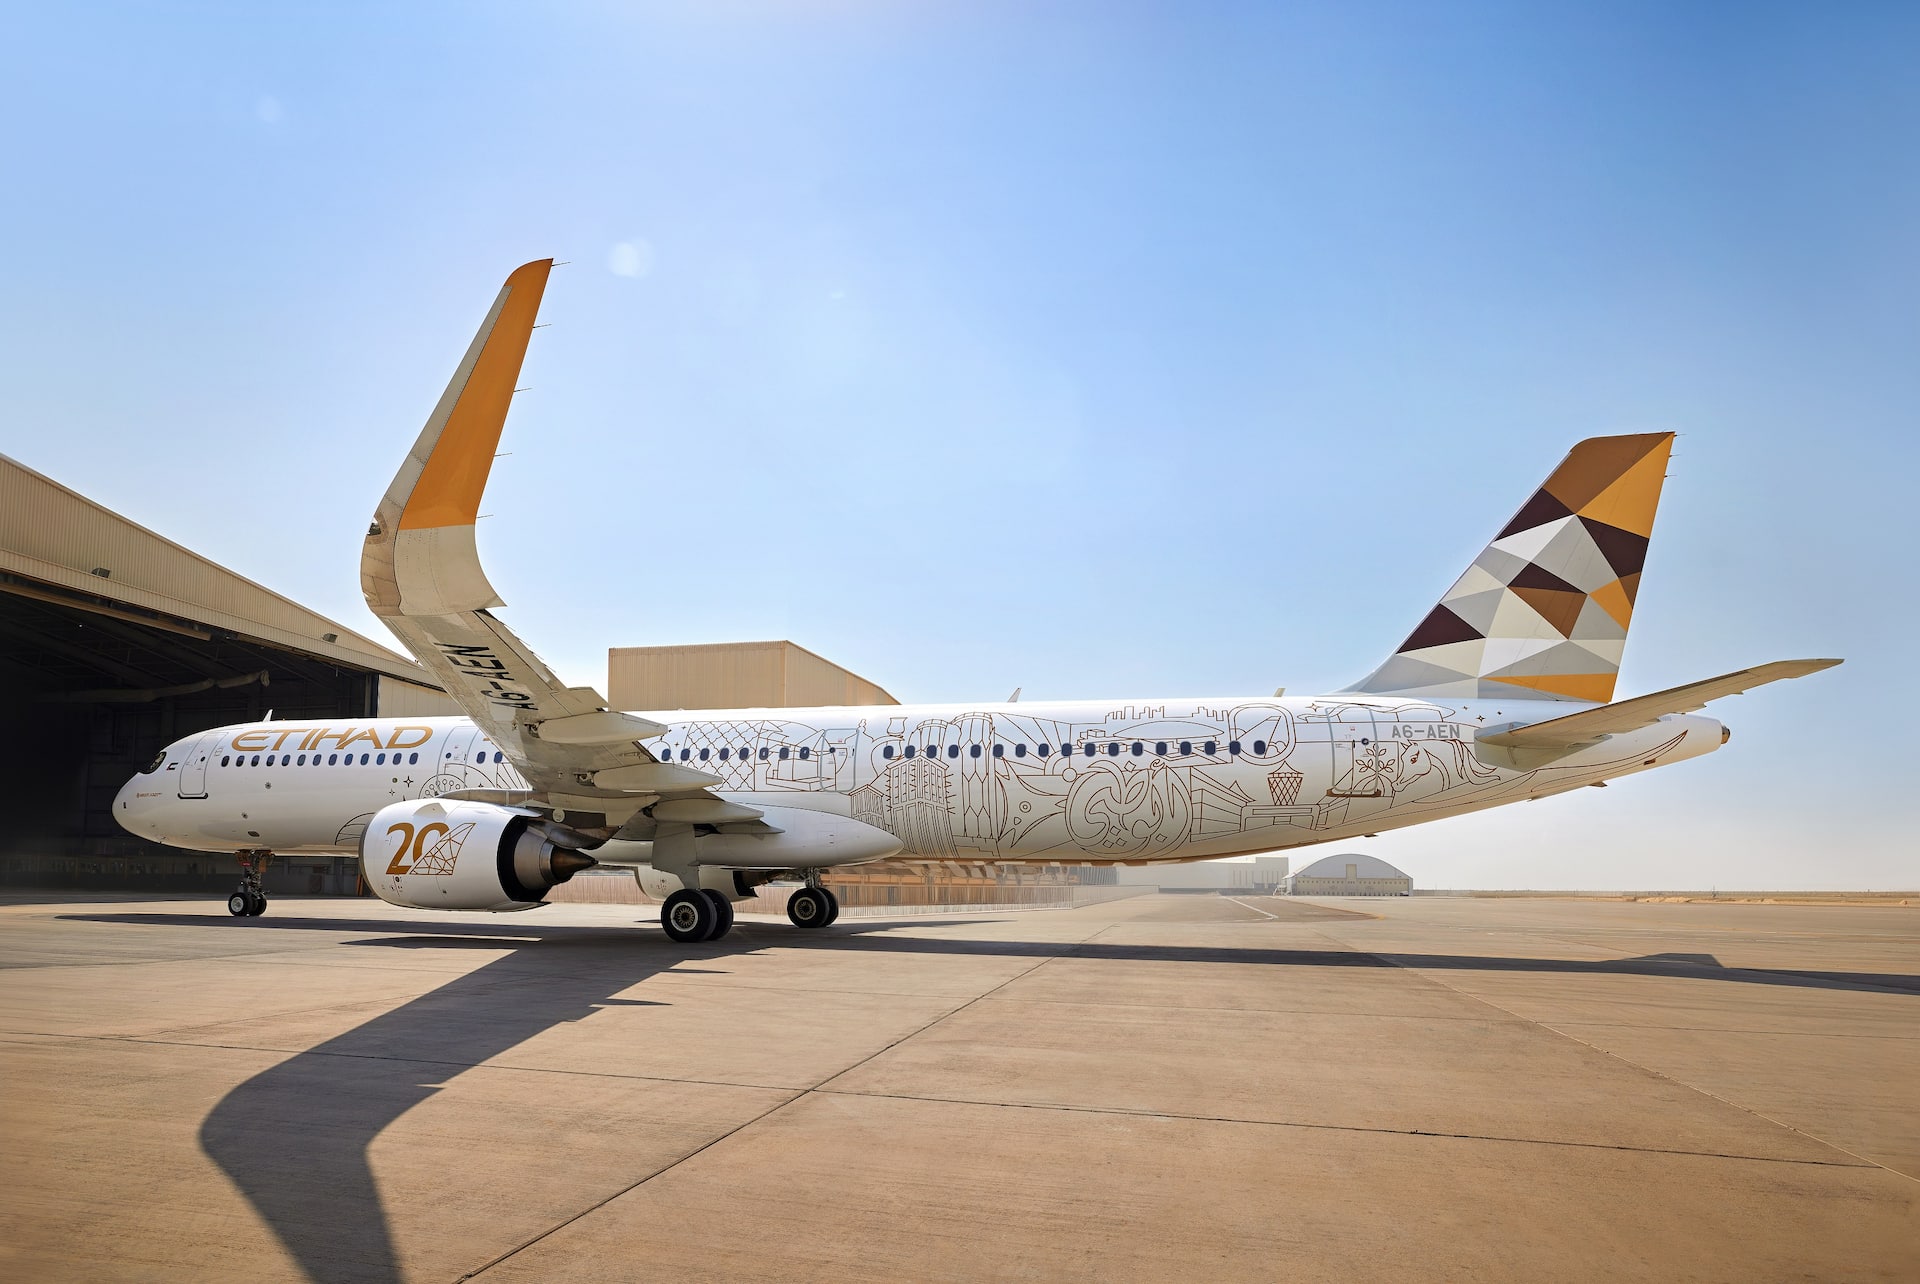
Etihad Airways has surpassed the 20 million annual passenger mark for the first time, boosted by strong first-quarter profit and rising customer satisfaction. The airline’s operating fleet now exceeds 100 aircraft as it intensifies its global expansion and pursues ambitious 2030 targets.

Etihad posted a Q1 profit after tax of AED 685 million, a 30 per cent increase compared to the same period last year. Total revenue rose 15 per cent, supported by growth in both passenger and cargo operations. Passenger revenue alone increased by 16 per cent to AED 5.5 billion, reflecting stronger demand and enhanced flight frequency. The carrier flew 5 million passengers in the quarter, a 16 per cent jump year‑on‑year, with a solid load factor of 87 per cent.

Over the past 12 months, Etihad has carried more than 20 million guests—doubling its annual passenger figures in just 30 months—and is now regarded as the fastest-growing airline in the region. Chief Executive Antonoaldo Neves described this milestone as evidence of “sustained growth driven by expanding demand, a dynamic global network, and a clear strategic focus”.

Customer satisfaction surged to record highs, with Q1 scores up 20 per cent versus a year ago. The airline attributed this to refreshed lounge and inflight menus, improved digital services, high-speed Wi‑Fi, and a revamped website and mobile app.

Etihad’s fleet currently comprises over 100 aircraft, including the return of its seventh Airbus A380 and the delivery of a Boeing 787‑9 with an Emirati crew, alongside its first of three Airbus A350‑1000s. A further 18 aircraft are expected in 2025, highlighted by the introduction of the A321LR narrow‑body fleet on 1 August, which will feature private First Suites, lie‑flat Business seats, 4K entertainment screens, and high‑speed Wi‑Fi across all cabins.

The airline has added 27 new routes so far in 2025 and plans to operate nearly 90 destinations by year‑end. These network additions form part of Etihad’s longer-term strategy to expand its global footprint to over 125 destinations and grow its fleet to more than 170 aircraft, with the aim of carrying 38 million passengers annually by 2030.

Operational efficiency gains also strengthened Etihad’s balance sheet. EBITDA rose 32 per cent to AED 1.4 billion, yielding a 21 per cent margin, while net leverage improved to 1.1×, down from 1.9× in March 2024. Cash flow from operations reached AED 1.8 billion, an 11 per cent improvement.

These developments follow a broader resurgence at Etihad. The carrier turned around from consecutive annual losses of recent years to report a record USD 476 million profit in 2024, flying 18.5 million passengers that year—a 32 per cent increase—and generating revenue of nearly USD 6.9 billion. The Q1 results affirm progress in cost optimisation, network rationalisation and fleet modernisation initiated under CEO Neves since taking the helm in 2022 under Abu Dhabi sovereign fund ADQ.

Looking ahead, Etihad plans to sustain delivery of 20-plus new aircraft annually, including further Boeing 787s and Airbus A350s, to meet projected demand. It is also preparing infrastructure and service upgrades connected to Abu Dhabi’s Zayed International Airport, whose terminal expansion tripled annual capacity to 45 million passengers, reinforcing the city’s role as a global hub.

On the route front, 16 further destinations have been announced for 2025, complementing an already swift rollout of 27 new routes. The A321LR rollout from August will unlock First Class on single‑aisle sectors, with an upgraded passenger experience including concierge transfers, chauffeur services and luggage‑free travel in Abu Dhabi.

Etihad’s turnaround, driven by disciplined execution of its “Journey 2030” strategy, has paid off. With record profits, growing customer satisfaction and a fleet age structure among the youngest globally, the airline is moving ahead of Gulf competitors as a stronger, customer‑centric global carrier.

A significant majority of sovereign wealth funds from the Middle East are poised to increase their investments in Chinese assets over the coming five years, according to the latest findings from Invesco’s Global Sovereign Asset Management Study. This shift places China at the forefront of strategic allocation decisions, reflecting growing confidence in its innovation-led sectors.

The study, conducted between January and March and covering funds and central banks managing a combined US$27 trillion, reveals that around 60% of Middle Eastern sovereign wealth funds are planning to boost exposure to China. This places the region only behind Asia‑Pacific and Africa, where 88% and 80% of funds respectively intend to raise allocations. North American counterparts also show strong interest, with approximately 73% signalling intent to increase investment in China.

Funds across regions cited strong returns—identified by 71% of respondents—as a key motivator, alongside diversification goals cited by 63% and improved market access for foreigners mentioned by 45%. Chinese innovation sectors, including digital technology, software, advanced manufacturing, automation, and clean energy, are particularly attractive, with 89% indicating interest in digital tech and software, and 70% each for manufacturing and green energy.

Participants in the study included 141 senior investment professionals—chief investment officers, asset-class heads and portfolio strategists—drawn from 83 sovereign wealth funds and 58 central banks globally. The high participation rate lends weight to the findings: China is now ranked as a high or moderate priority for 59% of funds, a notable jump from the previous year.

Despite geopolitical tensions between Washington and Beijing, sovereign funds appear more focused on structural opportunities. North American allocations towards China are framed as strategic, long-term bets in innovation rather than reactive moves to policy friction. As one Invesco executive described, investors appear driven by fear of missing out on China’s strides in semiconductors, AI, EVs and renewable energy—“a strategic urgency they once directed toward Silicon Valley”.

A regional lens reveals the Middle Eastern shift as part of a larger recalibration. Sovereign funds in the Gulf and from oil-rich neighbours are increasingly turning to China not just for commodity trades but for diversified returns and access to high-growth sectors. One Middle Eastern fund commented that the credit spectrum in fixed income markets currently offers more attractive risk-adjusted returns than public equities, underlining a broader repositioning.

Globally, sovereign investors are embracing active management, allocating more to fixed income and private credit as markets normalise post ultra-low interest rate era. Thirty‑nine per cent of funds plan to increase fixed income exposure, underscoring a pivot towards liquidity management and resilience. Private credit usage has expanded sharply, from 30% to 44% in direct or co-investments, reflecting growing appetite for yield and portfolio diversification.

Central banks are also reshaping strategy, with 64% planning to grow reserve holdings and 53% aiming to diversify further within two years. Gold remains a popular hedge: almost half intend to expand allocations over the next three years. The dominance of the US dollar persists, with 78% expecting no credible alternative supply within the next two decades.

A modest entrant in the digital asset space, sovereign wealth funds are gradually increasing exposure to digital currencies. Direct allocations rose to 11% from 7% in 2022, most pronounced in the Middle East, Asia‑Pacific and North America. Stablecoins, viewed as more accessible than traditional crypto, are gaining attention among emerging market funds.

China remains a focal point for global sovereign investors seeking exposure to growth-critical sectors and structural diversification. The convergence of strong returns, market access improvements, and sectoral opportunities is driving Middle Eastern and other funds to recalibrate their portfolios. China has transitioned from an optional allocation into a central pillar of future-focused asset strategies, marking a calculated investment pivot amid an evolving global landscape.

HO CHI MINH, VIETNAM – Media OutReach Newswire – 19 July 2025 – The China Factory Products Export Fair 2025 was held in Ho Chi Minh City, Vietnam from July 12 to 14. Hundreds of original manufacturers from places like Shandong province’s Linyi city displayed thousands of products ranging from daily necessities, office supplies, chemical products, and outdoor equipment to hardware tools. This fair adopted a collaborative […]

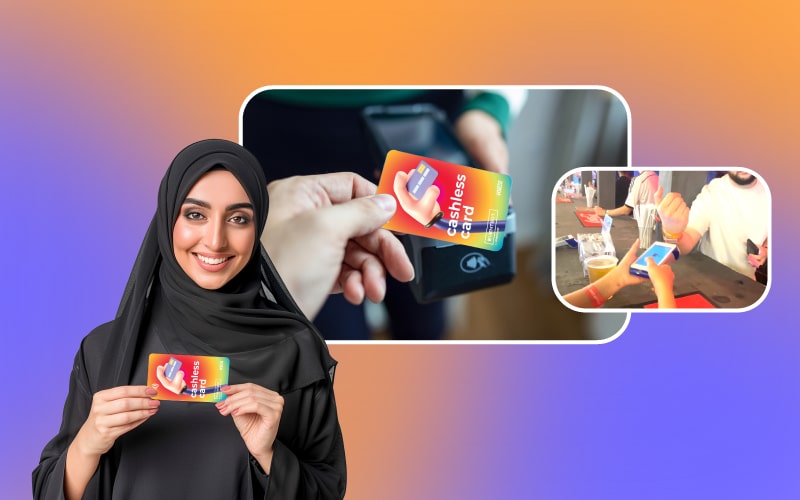
Dubai Chamber of Digital Economy and Dubai Finance have entered into a strategic partnership to bolster the emirate’s ambitions of becoming a fully cashless economy. A Memorandum of Understanding signed between the two bodies outlines a coordinated framework that targets improved governance, fintech innovation, and wider digital payment adoption, in line with the objectives of the Dubai Cashless Strategy.

The agreement was formalised during a ceremony attended by H. E. Abdulrahman Saleh Al Saleh, Director General of Dubai Finance, and H. E. Mohammad Ali Rashed Lootah, President and CEO of Dubai Chambers. Representing the respective institutions, Saeed Al Gergawi, Vice President of Dubai Chamber of Digital Economy, and Ahmad Ali Meftah, Executive Director of the Central Accounts Sector at Dubai Finance, signed the document on behalf of their organisations.

This collaboration underscores Dubai’s growing emphasis on integrating digital solutions across public and private sector transactions, as the emirate positions itself as a global fintech and smart governance hub. The new agreement aims to accelerate digital payments across government services while enhancing efficiency, security, and accessibility.

Under the framework of the MoU, both entities will establish joint task forces, undertake regular progress evaluations, and implement technology-driven initiatives to modernise financial infrastructure. The emphasis will be on enabling end-to-end digital transactions for individuals and businesses interacting with government entities.

Officials involved in the signing highlighted the strategic relevance of the initiative, citing the pivotal role of digital transformation in achieving Dubai’s broader economic diversification goals. Saeed Al Gergawi remarked that this step would unlock new economic potential and reinforce Dubai’s reputation as a leader in digital innovation. He noted that the Chamber aims to promote the use of cashless technologies across all levels of society, particularly among small businesses and startups.

Ahmad Ali Meftah echoed similar sentiments, noting that the DOF views this partnership as an opportunity to develop governance models that leverage real-time payment data and analytics to improve decision-making and transparency. He added that it marks a milestone in the effort to optimise public sector financial management through advanced digital tools.

The Dubai Cashless Strategy, announced previously by the Dubai Government, focuses on transforming the way residents and businesses conduct financial transactions. Its three-pillar approach—governance, innovation, and the shift towards a cashless society—provides the structural foundation for this latest collaboration. The strategy also aligns with the UAE Digital Government Strategy 2025, which aims to foster a holistic digital ecosystem nationwide.

Dubai has already made significant strides towards cashless integration. Key government services, including health, transport, and municipal utilities, have seen widespread uptake of digital payments. A growing number of private sector entities—particularly in retail, hospitality, and real estate—have also moved to offer fully contactless payment options.

Data from payment solutions providers and financial regulators suggest that consumer behaviour in Dubai is increasingly shifting towards digital modes. Contactless transactions, QR-code payments, and mobile wallet usage are seeing double-digit growth, reflecting both convenience and trust in digital platforms. E-commerce platforms and delivery services in the city have reported a significant drop in cash-on-delivery usage, replaced by integrated payment gateways.

Despite the surge in adoption, challenges remain. Concerns over cybersecurity, digital exclusion among certain demographics, and interoperability between platforms continue to demand coordinated attention. Experts believe that public-private partnerships, like the one signed this week, are vital to addressing these gaps. The joint initiative between Dubai Finance and Dubai Chamber of Digital Economy aims to prioritise inclusive design and data security in all future systems.

Digital finance specialists have observed that the commitment from high-level institutions such as DOF and Dubai Chambers is an indication of long-term policy backing. The formalisation of this cooperation may lead to more unified regulatory frameworks, making it easier for startups and global fintech players to operate in Dubai’s ecosystem.

The agreement is also expected to boost investor confidence, particularly among digital-first businesses exploring Middle East expansion. Analysts note that initiatives aimed at institutionalising digital payments often serve as catalysts for broader technology adoption, including AI-driven financial services and decentralised finance platforms.

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA
Just in: