News related to
Chinese

A significant majority of sovereign wealth funds from the Middle East are poised to increase their investments in Chinese assets over the coming five years, according to the latest findings from Invesco’s Global Sovereign Asset Management Study. This shift places China at the forefront of strategic allocation decisions, reflecting growing confidence in its innovation-led sectors.

The study, conducted between January and March and covering funds and central banks managing a combined US$27 trillion, reveals that around 60% of Middle Eastern sovereign wealth funds are planning to boost exposure to China. This places the region only behind Asia‑Pacific and Africa, where 88% and 80% of funds respectively intend to raise allocations. North American counterparts also show strong interest, with approximately 73% signalling intent to increase investment in China.

Funds across regions cited strong returns—identified by 71% of respondents—as a key motivator, alongside diversification goals cited by 63% and improved market access for foreigners mentioned by 45%. Chinese innovation sectors, including digital technology, software, advanced manufacturing, automation, and clean energy, are particularly attractive, with 89% indicating interest in digital tech and software, and 70% each for manufacturing and green energy.

Participants in the study included 141 senior investment professionals—chief investment officers, asset-class heads and portfolio strategists—drawn from 83 sovereign wealth funds and 58 central banks globally. The high participation rate lends weight to the findings: China is now ranked as a high or moderate priority for 59% of funds, a notable jump from the previous year.

Despite geopolitical tensions between Washington and Beijing, sovereign funds appear more focused on structural opportunities. North American allocations towards China are framed as strategic, long-term bets in innovation rather than reactive moves to policy friction. As one Invesco executive described, investors appear driven by fear of missing out on China’s strides in semiconductors, AI, EVs and renewable energy—“a strategic urgency they once directed toward Silicon Valley”.

A regional lens reveals the Middle Eastern shift as part of a larger recalibration. Sovereign funds in the Gulf and from oil-rich neighbours are increasingly turning to China not just for commodity trades but for diversified returns and access to high-growth sectors. One Middle Eastern fund commented that the credit spectrum in fixed income markets currently offers more attractive risk-adjusted returns than public equities, underlining a broader repositioning.

Globally, sovereign investors are embracing active management, allocating more to fixed income and private credit as markets normalise post ultra-low interest rate era. Thirty‑nine per cent of funds plan to increase fixed income exposure, underscoring a pivot towards liquidity management and resilience. Private credit usage has expanded sharply, from 30% to 44% in direct or co-investments, reflecting growing appetite for yield and portfolio diversification.

Central banks are also reshaping strategy, with 64% planning to grow reserve holdings and 53% aiming to diversify further within two years. Gold remains a popular hedge: almost half intend to expand allocations over the next three years. The dominance of the US dollar persists, with 78% expecting no credible alternative supply within the next two decades.

A modest entrant in the digital asset space, sovereign wealth funds are gradually increasing exposure to digital currencies. Direct allocations rose to 11% from 7% in 2022, most pronounced in the Middle East, Asia‑Pacific and North America. Stablecoins, viewed as more accessible than traditional crypto, are gaining attention among emerging market funds.

China remains a focal point for global sovereign investors seeking exposure to growth-critical sectors and structural diversification. The convergence of strong returns, market access improvements, and sectoral opportunities is driving Middle Eastern and other funds to recalibrate their portfolios. China has transitioned from an optional allocation into a central pillar of future-focused asset strategies, marking a calculated investment pivot amid an evolving global landscape.
HO CHI MINH, VIETNAM – Media OutReach Newswire – 19 July 2025 – The China Factory Products Export Fair 2025 was held in Ho Chi Minh City, Vietnam from July 12 to 14. Hundreds of original manufacturers from places like Shandong province’s Linyi city displayed thousands of products ranging from daily necessities, office supplies, chemical products, and outdoor equipment to hardware tools. This fair adopted a collaborative […]

Chinese mainland REIT market joined the top three largest REIT markets in Asia for the first time with an 85% increase in market value in 2024 India’s office REIT market attracted considerable leasing demand from global capability centres Data centre and hospitality REITs gained strong investor interest in Japan and Singapore HONG KONG SAR – Media OutReach Newswire – 17 July 2025 – China and India’s Real […]

HONG KONG SAR – Media OutReach Newswire – 17 July 2025 – The brand-new TV show “AI for Humans” will premiere on 19 July (Saturday) at 8:30 PM on HOY TV Channel 78. This 17-episode series focuses on Artificial Intelligence (AI), inviting viewers to explore how AI is shaping the future and driving Hong Kong to become a global innovation and technology hub. Supported by Cyberport and […]

Swatch Group’s first‑half figures underscore a deepening crisis in its key Asian markets after the Swiss watch‑maker disclosed a 7.1 per cent drop in sales, generating CHF 3.059 billion, falling short of market forecasts of CHF 3.2 billion. Operating profit plunged 67 per cent year‑on‑year to CHF 68 million, signalling an urgent warning to investors and management alike.

China, alongside Hong Kong and Macau, remains the primary weak spot, contributing 27 per cent of total revenues. Falling demand across these regions continues to undermine core sales and profit performance. Despite encouraging double‑digit growth in North America and market share gains in countries such as Japan, India and the Middle East, these gains have yet to compensate for the shortfall from Greater China.

Net profit attributable to owners collapsed to CHF 3 million, compared with CHF 136 million during the same six‑month period last year. This dramatic decline illustrates the scale of the downturn, making it Swatch’s worst half‑year performance in recent memory.

Analyst commentary has been scathing: Vontobel described this period as “an ugly half year for Swatch Group in all respects”. The fallout from slowed Chinese consumer activity has been compounded by negative currency effects—Swiss franc appreciation cut CHF 113 million from turnover relative to constant‑currency comparisons.

Adding fresh complexity, new U. S. tariffs threaten to raise costs on Swiss watch imports by up to 31 per cent. Industry stakeholders now warn that these levies could further weigh on margins, with retailers like Watches of Switzerland projecting a margin squeeze in the year ahead.

Beyond external pressures, a growing number of investors are scrutinising Swatch’s internal governance. Shareholder activism has surfaced, with calls for more oversight of the centrally controlled Hayek family, whose dual‑class voting structure remains a source of contention. Net profits collapsed by 75 per cent to CHF 219 million in 2024, but critics assert that this malaise runs deeper. GreenWood Investors, led by Steven Wood, has launched a push to join the board, advocating for brand revitalisation, governance reforms and a strategy pivot toward luxury exclusivity akin to Hermès and Ferrari.

Management, though addressing short‑term volatility, emphasises Swatch’s entrenched strengths. Its vertically integrated manufacturing, with over 150 production sites, and the success of the affordable MoonSwatch line demonstrate resilience. The company has pledged that cost‑cutting measures and a pipeline of new product launches—particularly in the U. S. and Japan—should drive a rebound in the second half of the year.

The first‑half slump follows broader downturns last year, when revenue declined 12.2 per cent to CHF 6.74 billion in 2024, and operating profit fell 75 per cent to CHF 304 million. That drop reinforced trading floor rumours of governance fatigue and brand dilution at high‑end labels like Omega and Breguet.

Economically, China’s consumer landscape remains unsettled. A combination of property market stress, slower GDP growth and official campaigns discouraging conspicuous consumption have dampened luxury spending. Swiss watch exports to China and Hong Kong plunged by double digits in early 2024, while only the lower‑priced Swatch line bucked the trend in the region, gaining 10 per cent in sales volume.

Swatch Group’s corporate ambition to maintain full production capacity and avoid layoffs during weak demand, while strategically commendable, has weighed on margins—especially in the production segment. Management asserts this decision safeguards long‑term capabilities and is now beginning to bear fruit, with production margins improving since June.

Mixed signs beyond China offer guarded optimism. North America posted record sales, Japan recorded robust growth, and emerging markets like India and the Middle East offered upside. These regions now form the central axis of Swatch’s recovery strategy.

HONG KONG SAR – Media OutReach Newswire – 17 July 2025 – The brand-new TV show “AI for Humans” will premiere on 19 July (Saturday) at 8:30 PM on HOY TV Channel 78. This 17-episode series focuses on Artificial Intelligence (AI), inviting viewers to explore how AI is shaping the future and driving Hong Kong to become a global innovation and technology hub. Supported by Cyberport and […]

SINGAPORE – Media OutReach Newswire – 17 July 2025 – With the global lubricants industry still adjusting to the lasting impact of U.S. trade policy enacted during the first presidential term of U.S. President Donald Trump, supply chains are undergoing dramatic shifts—and Asia is solidifying its role as the sector’s global hub. While the U.S. tariffs primarily targeted a broad range of Chinese industrial chemicals under Section […]

Advertisements
By Nitya Chakraborty India-China bilateral relations have started showing cautious improvement with the signals from both the leaderships of the two biggest countries of Asia that they are keen to restore normal political and economic ties. Indian external affairs minister Dr. S Jaishankar’s meeting with the Chinese President Xi Jinping on Monday in Beijing was […]

HONG KONG SAR – Media OutReach Newswire – 16 July 2025 – This summer, LEGO® Group teams up with popular minifigure Lok Jai to invite everyone in Hong Kong—young and old—to “Take a Brick” and enjoy a slower, more joyful summer! From July 12 to August 31, 2025, LEGO® Hong Kong presents the “Let’s Take a Brick” campaign, where Lok Jai will pop up at eight “Fun […]

Uber Technologies and Baidu Inc. have confirmed a multi‑year strategic alliance to bring Baidu’s Apollo Go autonomous robotaxis to markets beyond the U. S. and mainland China, initiating the programme later this year in select cities across Asia and the Middle East. The new service, integrated into the Uber app, will offer riders the option to choose fully driver‑free vehicles powered by Apollo Go’s advanced AI systems.

Apollo Go currently operates the world’s largest driverless ride‑hailing network, with more than 1,000 fully autonomous vehicles deployed across 15 cities—including Dubai and Abu Dhabi—and over 11 million rides completed as of May 2025. The expansion, announced on 15 July 2025, marks a significant move by Uber as it intensifies its foray into autonomous vehicles, supplementing existing partnerships with other AV developers such as Waymo, Pony AI, WeRide, May Mobility, Volkswagen and Avride.

Uber CEO Dara Khosrowshahi described the venture as a decisive milestone: “This partnership brings together two of the world’s most iconic technology companies to help shape the future of mobility. As the world’s largest platform of its kind, spanning mobility, delivery, and freight, Uber is uniquely positioned to help AV leaders like Baidu bring their autonomous technology to the world.” Baidu’s co‑founder and CEO Robin Li added that integrating Baidu’s autonomous driving technology with Uber’s network represents “a major milestone in deploying our technology on a global scale,” aimed at delivering safe, efficient and cost‑effective transport to a wider audience.

Market response to the announcement has been positive: Uber’s shares rose more than 1 % in pre‑market trading in the U. S., while Baidu’s U. S.‑listed stocks surged almost 5 %, reflecting investor confidence in the deal’s potential to accelerate autonomous mobility adoption worldwide.

The initial deployment targets key cities in Asia—potentially including Singapore and Malaysia where Baidu plans to launch Apollo Go this year—and in the Gulf region, where regulatory environments are favourable and infrastructure is supportive. Recent reports highlight that Gulf countries such as the UAE and Saudi Arabia aim to have at least 25 % of transport in major cities autonomous by 2030‑2040, presenting a promising opportunity for robotaxi services.

Analysts view the Uber‑Baidu partnership as a pivotal step in global AV expansion. By entering markets outside its core regions, Baidu leverages an “asset‑light” international strategy driven by collaboration instead of proprietary platforms. Uber gains immediate access to a proven self‑driving fleet without the development time and costs associated with in‑house technology, bolstering its competitiveness in the robotaxi space, particularly against rivals like Lyft and Waymo.

Safety and regulatory scrutiny remain top concerns. Apollo Go’s record of over 11 million rides with a robust safety profile strengthens public and regulatory confidence. Still, each market’s regulatory readiness varies, requiring phased live testing and strong oversight to meet local licensing standards.

Financially, the deal promises dividend benefits. By significantly increasing supply of robotaxis through Uber’s platform, Baidu stands to accelerate revenue from its autonomous segment, potentially addressing investor concerns over its core advertising business. Uber, which has seen its stock climb 56 % this year, reinforces its diversification into autonomous and freight services ahead of its Q2 earnings report scheduled for 6 August.

Competition is heating up. The Gulf region already hosts partnerships between Uber and Chinese AV firms such as Pony AI and WeRide, both of which are conducting trials or planning roll‑outs in Dubai and Abu Dhabi. Baidu’s entry into this competitive space joins a growing group of Chinese robotaxi operators—such as Pony AI, AutoX, DiDi and WeRide—vying for global market share.

While the United States and mainland China remain outside the deal’s scope—due to complex regulatory frameworks and entrenched competition—Uber and Baidu have hinted at future expansions into Europe and Oceania, suggesting a long‑term global vision. Baidu’s ongoing engagement with European regulators, including Switzerland and Turkey, supports predictions for expanded rollout later this year.

China Development Bank has successfully listed two bonds on Nasdaq Dubai, raising a total of more than US $1 billion in a strategic bid to broaden its foreign‑currency funding channels and attract global investors. The issuance includes a US $500 million three‑year floating‑rate tranche tied to SOFR + 30 bps, and a €500 million three‑year fixed‑rate tranche offering a 2.25 percent coupon. Both tranches carry an A1 rating from Moody’s. Investor appetite proved robust across both offerings. […]

China has introduced the world’s first oil tanker equipped with adjustable sails, marking a notable step in maritime decarbonisation. The 250‑metre vessel features automated sails that harness wind power, cutting diesel use by up to 14.5 tonnes per day—equivalent to around 5,000 tonnes of CO₂ emissions annually.

The ship was launched at a major Chinese port on 13 July 2025. Naval engineers report that the sails adjust in real time to wind conditions, seamlessly integrating with traditional propulsion systems. Under favourable conditions, the sails alone can provide up to 10% of the vessel’s forward thrust, reducing reliance on fossil fuels and trimming operational costs.

Industry experts describe this as a breakthrough. Dr Li Wei, a maritime technology specialist at a prominent Chinese university, observed that “this marks the first large‑scale application of intelligent sail technology in an oil tanker” and said that the design “could serve as a blueprint for future green tankers”. While alternative zero‑carbon fuels remain the focus of long‑term strategies, sail augmentation presents a practical interim solution.

The initiative aligns with global regulatory pressures. The International Maritime Organization has committed to halving greenhouse‑gas emissions from shipping by 2050. Flettner‑style rotor sails—used on vessels like the Viking Grace ferry—have shown up to 20% fuel savings on optimal routes. China’s innovation refines that concept by adding adjustable sail arrays tailored for large oil carriers, suggesting broader applicability.

Major energy and shipping firms are reportedly evaluating roll‑outs. A senior executive at a state‑affiliated shipping group noted plans to retrofit a fleet of oil and chemical tankers with adjustable sails by 2027, contingent on performance data. Initial trials aim to quantify actual fuel savings, spreadsheeting data on fuel burn, wind usage hours, and analytics from the ship’s sail‑control system.

Yet questions remain. Retrofit costs, structural modifications, and maintenance demand rigorous cost‑benefit analysis. Port infrastructure adaptation—such as clearance for sails and crew training—must also be addressed. Critics argue that, while useful, sail technology cannot fully eliminate emissions without complementary measures like low‑carbon fuels and electrification.

Nevertheless, China’s venture may shift the conversation. Shipbuilders in Europe, Japan and South Korea are racing to develop hydrogen‑ or ammonia‑powered vessels. China’s move showcases an alternative decarbonisation route by optimising existing diesel‑powered fleets. Multi‑source interviews show growing interest from global charterers, some of whom are signalling willingness to pay premium freight rates for lower‑emission vessels.

Maritime insurers are recalibrating risk models, acknowledging that adjustable sails could affect stability and route safety. The new tanker reportedly features advanced ballast‑control systems to compensate for wind forces and automated cut‑out mechanisms during storms.

Trade analysts say China’s state‑backed strategy gives it leverage in global standards talks. Should pilot data validate the 14.5‑tonne daily fuel savings estimate, Chinese shipyards could license or export the design. Such a trend could trigger wider international adoption, pressuring other nations to follow suit.

Shipowners are watching. A European tanker operator, examining images and footage, expressed interest but noted the need for “transparent data on lifecycle emission reductions and economic viability over 20‑year vessel lifetimes.”

Current trials will last six months to a year, tracking metrics like fuel consumption, sail uptime, and maintenance costs. A detailed performance report is expected by mid‑2026, after which retrofit plans may accelerate.

SHENZHEN, CHINA – Media OutReach Newswire – 14 July 2025 – The inaugural promotion event for the 2025 Global Artificial Intelligence Machines and Electronics Expo (AIE) was held in Shenzhen, a thriving innovation hub in South China, on Thursday. Shenzhen hosts first promotion event for 2025 Global AI Machines and Electronics Expo Over 100 representatives from government, industry, and international trade associations attended the event. The event […]

Overview – Asia Pacific’s Wealth Boom Accelerates HONG KONG SAR – Media OutReach Newswire – 14 July 2025 – The sixth edition of the Julius Baer Global Wealth and Lifestyle Report confirms the ongoing shift from material consumption towards experiences. Jen-Ai Chua, Research Analyst, Asia, Julius Baer, commented: “Asia Pacific remains one of the fastest-growing regions globally. Real GDP grew 4.5 per cent year on year in […]

Oil traded in a narrow range as tariffs and sanctions threats unsettled global markets, weighing heavily on the outlook for energy demand. Brent hovered just above $70 a barrel, while West Texas Intermediate stayed above $68. Futures markets weakened as U. S. equity-index futures dropped following fresh trade tensions between Washington and key global partners.

U. S. President Donald Trump escalated tariff threats, targeting both the European Union and Mexico with 30 per cent duties and flagging potential levies against Brazil, the Philippines, Japan, South Korea and others. Markets interpreted this as a risk to economic momentum, especially in energy‑sensitive regions of Asia, denting crude demand expectations. At the same time, Asian buyers adopted a cautious stance, amplifying downward pressure on oil.

Against this backdrop, investors are eyeing a scheduled “major statement” from President Trump concerning Russia. Anticipation of new sanctions against the country, a major oil producer, lent modest support to prices that might otherwise have fallen further. Still, this support was checked by rising output from OPEC+ and a pause in geopolitical flare-ups in the Middle East.

Data from the International Energy Agency signals that global oil markets remain relatively tight. Summer driving seasons and increased refinery activity have buoyed demand, although analysts note that elevated output from Saudi Arabia—above its OPEC+ quota—puts a dent in any sustained rally. The kingdom disputes claims of non‑compliance, stating marketed crude remains within agreed limits.

Market watchers also flag OPEC+ plans to hike production by approximately 548,000 barrels per day in August, potentially followed by another boost in September. ING warns these moves could put the market into surplus in the final quarter of 2025. Additionally, the group revised its global demand forecasts downward for 2026–29, citing weakening growth in China.

Further clouding the outlook, heightened tariff uncertainty is exerting macroeconomic drag. The IEA forecasts a meaningful drop in global oil consumption growth for 2025, down a third from earlier projections, due in part to Trump’s tariff measures. Analysts stress that inflationary pressures and slower global trade would dampen energy demand.

From a logistical standpoint, renewed Houthi tensions in the Red Sea have introduced another variable, interrupting shipping and supporting prices marginally. Still, Middle East volatility has largely receded compared with levels seen earlier this year.

Looking ahead, market players are set to digest a blend of geopolitical and macroeconomic signals. Key Chinese trade figures due soon may reveal shifts in demand. OPEC+ decisions on output will be scrutinised closely, as will the next moves in Washington’s trade and sanctions policy. Meanwhile, U. S. gasoline consumption remains robust, with the Energy Information Administration reporting a 6 per cent increase to 9.2 million barrels per day—signalling that underlying demand has not yet faltered.

Oil markets are caught between supportive fundamentals—such as strong summer demand, supply constraints from Russia and geopolitical flare‑ups—and sobering headwinds from proposed tariffs, elevated output and macroeconomic uncertainty. Traders remain cautious, awaiting concrete policy developments from Washington, data releases from China, and steps by OPEC+ to navigate a market landscape that is anything but stable.

Oil prices have shifted sharply this week, with demand forecasts now under pressure from escalating trade tensions fuelled by fresh tariffs. Brent crude is trading in the high‑60s per barrel, while benchmark WTI hovers around mid‑60s, reflecting growing investor caution. Analysts point to revised supply and demand projections as indicators of a changing market landscape.

An International Energy Agency monthly report has cut its global oil‑demand growth forecast for 2025 to 700,000 bpd, the slowest pace since 2009 outside the pandemic, down from 720,000 bpd last month. The downgrade reflects weaker consumption in emerging markets and a cooling US‑China trade outlook. Supply continues to outpace demand as OPEC+ ramps up production; global output in June rose by about 950,000 bpd to reach 105.6 mbpd.

The IEA notes the oil market remains technically in surplus, with inventories building globally—even as regional stock draws persist. Oil runs at refineries have slowed, particularly in the US and China, enabling downward revisions in demand projections. Enverus Intelligence Research offers a counter‑view, pointing to balanced OECD inventories and sustained summer demand north of 1 mbpd, which may support higher prices.

The US Energy Information Administration expects US crude oil production to plateau at roughly 13.4 mbpd in 2025, dropping modestly later this year as lower prices curb drilling activity. Despite this, producers remain vulnerable to profit erosion unless prices stabilise in the $65–70 range.

President Trump’s trade moves have reignited fears of another global trade war, with new tariff letters dispatched to Brazil, South Korea, Japan, the Philippines and others this week. Threats of 50% duties on exports such as copper, semiconductor components and auto parts are weighing heavily on commodity‑linked equity markets and raising recession risk concerns. Oil prices dropped more than 2% on Thursday as benchmark futures responded to the potential hit to economic growth.

While some market participants remain in “wait‑and‑see” mode, given Trump’s unpredictability and history of policy reversals, the overarching effect is to dampen demand forecasts. Onyx Capital’s head of research, Harry Tchilinguirian, cautions against overreaction but acknowledges that tariffs are adding to inflationary pressures and may reinforce Federal Reserve caution.

Geopolitical flashpoints in the Middle East continue to influence sentiment. Oil surged in June as Iran threatened to close the Strait of Hormuz, which handles almost 20% of world oil shipments, but prices eased once the waterway remained open. Meanwhile, Saudi Arabia raised official prices to consumers, citing strong demand in China’s post‑pandemic recovery, though refiners are reporting margin squeezes.

Financial institutions have started to reflect this shifting environment in their projections. A Reuters‑polled group of 40 analysts revised Brent average forecasts for 2025 to $67.86 per barrel—up marginally from May—while predicting demand growth of only around 730,000 bpd. JP Morgan cut its annual Brent estimate to $66, citing rising OPEC+ output and sluggish consumption. TD Economics trimmed its forecast further, expecting 2025 WTI to average near $62, warning of sustained downward pressure from trade risk and oversupply.

Two factors loom large over the coming months. First, the path of trade tensions: further tariff escalations or retaliatory actions could erode industrial activity and fuel sales. Second, OPEC+ strategy: with the bloc unconstrained in raising output, additional production could overwhelm tepid demand, pushing prices below current levels. The IEA projects supply growth for 2025 at 2.1 mbpd, while demand is seen rising just 700 kbpd.

On the financial front, hedge fund positioning has turned cautious, registering the sharpest drop in bullish sentiment since February. Traders are forecasting narrower price ranges ahead, with elevated volatility as tariff developments hit market headlines.

Forward‑looking forecasts remain mixed. EIA projects Brent to average $68.89 in 2025 and $58.48 in 2026, marking a seasonal decline. Enverus suggests the upside remains intact if demand holds steady, especially with summer driving season underway. Market watchers also note that rising gas‑to‑oil switching costs, refinery restarts and diminished spare capacity could temper price declines.

China’s consumption is also under scrutiny. While Beijing seeks to stimulate growth through fiscal and monetary tools, investor sentiment remains fragile. Saudi’s decision to push prices higher was based on perceived strengthening in Chinese demand, but many analysts caution that any slow‑down could rapidly tip the balance.

Emerging long‑term trends offer some balance. IEA’s long‑term outlook suggests oil demand will continue rising through the late 2020s, driven by non‑OECD economies and slower clean‑energy adoption, delaying peak demand beyond 2030. Nonetheless, short‑term price direction seems firmly tied to macroeconomic risks and geopolitical dynamics.

U. S. consumers now contend with an effective tariff rate exceeding 20%, marking the steepest level observed since the early 1900s, according to estimates by the International Chamber of Commerce following the latest round of import levies introduced under President Trump’s administration. This escalation stems from a newly implemented baseline tariff of 10%, supplemented by selective duties—up to 50% on copper and 200% on pharmaceuticals—pushing the overall […]

HEFEI, CHINA – Media OutReach Newswire – 11 July 2025 – On July 10, Anhui officially released the teaser for the upcoming 2025 World Manufacturing Convention, setting the stage for this premier gathering of the global manufacturing community. Under the theme “Intelligent Manufacturing, Better Future,” the teaser opens with a creative invitation addressed to an AI robot, symbolizing Anhui’s ambitions to build itself into a leading manufacturing […]

China Development Bank has launched a groundbreaking dual‑currency bond on Nasdaq Dubai, bearing an A1 rating from Moody’s, with a pair of three‑year notes: a $500 million floating‑rate tranche at SOFR +30 basis points and a €500 million fixed‑rate tranche bearing a 2.25 percent coupon. Investor demand flooded in, especially from Europe, the Middle East and Asia, marking a significant milestone in cross‑border financing. The euro tranche, with its enticing […]

FUZHOU, CHINA – Media OutReach Newswire – 11 July 2025 – Recently, Fujian launched the “Marine Culture in Fujian” campaign, inviting experts to share their perspectives on the province’s thriving marine culture. In this video, Dong Yuhui, a top Chinese livestreamer with nearly 30 million followers across China’s major social media platforms, explores the unique charm of Fujian’s oceanic heritage. “30% of your life is destined by […]

Russian Deputy Foreign Minister Sergei Ryabkov stated on Thursday that BRICS is not an “anti‑American” bloc and will reject any “language of threats and manipulation.” This assertion followed U. S. President Donald Trump’s announcement that countries adopting what he termed “anti‑American policies” aligned with BRICS would face an extra 10 per cent tariff. Ryabkov emphasised BRICS’ focus on dialogue and constructive engagement, not confrontation. He underscored that the group […]

BEIJING, CHINA – Media OutReach Newswire – 10 July 2025 – As the 11th Nishan Forum on World Civilizations takes place in east China’s Qufu City, CGTN published an article highlighting the importance of dialogue and mutual learning among civilizations to promote harmonious coexistence, shared prosperity, and the safeguarding of traditional values in the face of modern challenges. “Is it not a joy to have friends come […]

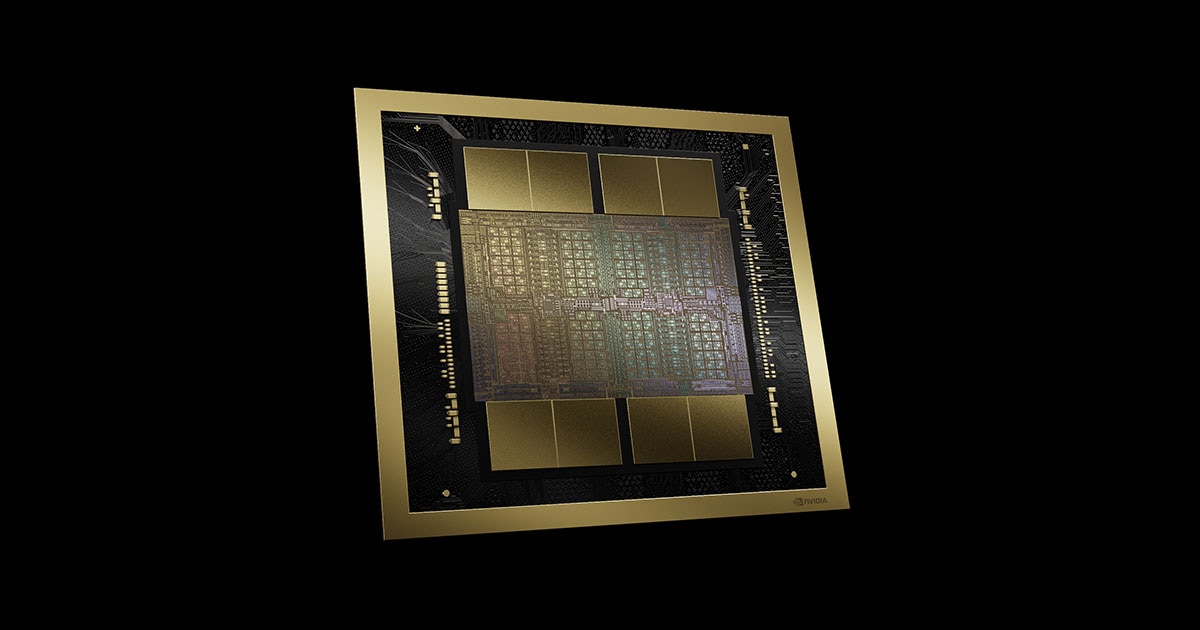
Nvidia is set to begin production of a new, lower‑spec Blackwell‑architecture AI chip for the Chinese market as early as June, aimed at complying with US export controls while maintaining its presence in the nation’s booming data centre sector. Priced between $6,500 and $8,000—significantly cheaper than the $10,000–$12,000 H20—the chip trades performance for accessibility under current regulatory constraints.

The streamlined variant is based on the RTX Pro 6000D, utilising conventional GDDR7 memory instead of high‑bandwidth memory and eschewing TSMC’s advanced CoWoS packaging to stay within US‑mandated memory bandwidth limits of 1.7–1.8 TB/s. Industry analysts note this is markedly below the 4 TB/s capability of the H20.

Yet Nvidia is not stopping there. As part of a dual‑chip strategy, it is reportedly developing a second Blackwell model scheduled to enter production by September. The specifications remain undisclosed but are expected to similarly align with US export regulations.

China accounts for around 13 per cent of Nvidia’s revenue, a slice that has shrunk sharply from a pre‑2022 peak due to export restrictions, which caused market share to decline from roughly 95 per cent to near 50 per cent today. A ban on the H20 in April prompted the company to write off about $5.5 billion in inventory and forgo an estimated $15 billion in sales.

CEO Jensen Huang has acknowledged the company’s “limited” options, stating that until a compliant design is approved by US authorities, Nvidia remains locked out of China’s $50 billion data centre market. Without it, his comments suggest many customers may migrate to domestic alternatives like Huawei’s Ascend 910B.

Domestic competition in China has intensified. Huawei’s Ascend 910B and others have gained momentum, closing the gap to Nvidia’s downgraded models within one to two years, according to semiconductor analysts. Nvidia counters this with its CUDA programming ecosystem — a key competitive advantage. With CUDA deeply integrated into AI development workflows globally, it may anchor developer loyalty even as hardware capabilities shift.

Further complicating the picture are whispers of a third chip internally known as “B30” or “B40”, which appears designed to operate in clusters and align with new export rules by focusing restrictions on individual chip rather than entire systems. Reports indicate interest from China’s leading tech companies—ByteDance, Alibaba and Tencent—with ambitions to produce more than 1 million units this year. Nvidia has not directly confirmed the chip, and one Chinese supplier, ZJK Industrial, briefly announced production ramp‑up for the B40 before retracting the statement, triggering increased market speculation.

US officials have shown concern that widespread availability of such chips—even within controlled clusters—could bolster China’s capabilities in foundational model training and inference tasks. Commerce Department Under‑Secretary Jeffrey Kessler recently told lawmakers that AI chip smuggling “is happening”, echoing longstanding export fears. Nvidia’s Huang maintains there is “no evidence” of diversion, but a consistent black‑market narrative continues to shadow the sector.

Chinese firms have outlined plans to deploy thousands of H100 and H200 chips in new data centres, particularly in western provinces such as Xinjiang and Qinghai, where abundant renewable power and cool climates offer logistical advantages. Target installations indicate upwards of 115,000 such processors in aggregated plans—most of which remain aspirational due to export prohibitions and logistical challenges.

Analysts suggest that while Nvidia’s tiered Blackwell chips may temporarily appease China’s AI infrastructure demands, the deeper impact will depend on regulatory outcomes and the strength of the CUDA ecosystem. If export restrictions ease, Nvidia stands to regain momentum; if they tighten, domestic chipmakers like Huawei will likely secure a larger foothold.

This unfolding scenario underscores a shift in semiconductor geopolitics: global tech leaders are adapting designs to fragmented access zones while local players race to fill the vacuum. The episode illustrates how export policy, market demand and strategic software assets intersect in shaping tomorrow’s AI hardware landscape.

XI’s BICKS NO-SHOW: STRATEGIC SHIFT OR SILENT WARNING? CHINESE SYMBOLISM ON CONFIDENCE IN FULL PLAY M A Hossain In the realm of global politics, symbolism matters almost as much as substance. President Xi Jinping of China has decided not to attend this year’s BRICS summit which will be held in Rio de Janeiro. This is the first time President Xi will not be at the summit since […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA