News related to
First Half

A surge in travellers tracing the on‑screen footsteps of K‑dramas is reshaping tourism across unexpected global landscapes. From lakeside Swiss villages to tranquil Japanese islets and coastal Korean towns, the ‘K‑Wave’ is turning fictional settings into real‑world destinations.

Fans of Crash Landing On You have placed the Swiss lakeside village of Iseltwald on the map. A modest community of 406 residents now sees approximately 1,000 visitors daily at the dock featured in the series. Access fees have yielded nearly 245,000 Swiss francs in 2024, with public toilet revenues adding a further 58,000 francs. Local authorities emphasise that funds are channelled into essential services, including waste management, restroom upkeep and additional staffing, rather than generating profit. Authorities also responded to the influx by installing signage and creating an informational website to encourage respectful tourist behaviour.

In Asia, Korea’s own locales continue to benefit from film‑induced tourism. Following the broadcast of Winter Sonata, visits to Nami Island soared, rising from 250,000 to over 650,000 — the iconic kissing‑spot statue now a pilgrimage for fans. Similarly, Hometown Cha‑Cha‑Cha elevated Pohang’s tourism profile, revitalising its commercial district, while Yangju’s Chang Ucchin Museum of Art attracted enquiries after featuring in episode twelve, prompting VR‑based fan tours leveraging immersive content.

This pattern extends beyond Korea. Swiss sites exemplify how global K‑drama audiences are contributing to local economies, especially in destinations outside traditional tourism circuits. The case of Iseltwald illustrates both the economic boost and the logistical strains of sudden fame. On the other hand, domestic examples underline how coordinated efforts—with content, tourism boards and local authorities collaborating—can shape sustained visitor interest.

Tourism experts note a broader shift: entertainment has become a powerful impetus for travel, transcending conventional marketing. The emotional investment viewers feel with characters and storylines often precedes a desire to experience the settings firsthand. In South Korea, advertisers and tourism agencies have capitalised on this trend. Data from 2025 shows searches for Seoul increased by 30 per cent in the first half of the year, while Busan’s surged by 50 per cent, fuelled by exposure in K‑dramas and social media travel content. Over 32 per cent of young global travellers cited K‑pop or K‑dramas as their primary reason for visiting, with 60 per cent motivated by food and cultural experiences.

Meanwhile, the broader economic ripple effect is apparent. A recent report highlights that the Korean Wave is driving increases in tourist spending across multiple regions and sectors—far beyond traditional attractions. Cultural soft power, rooted in entertainment, fashion, cuisine and beauty, is proving a more enduring and profitable tourism strategy.

This phenomenon underscores the dual nature of film-induced tourism. On one hand, it delivers tangible economic dividends—reviving rural towns, funding infrastructure, generating income for small businesses. On the other hand, communities face challenges: overburdened infrastructure, privacy concerns, and maintaining authenticity amid influxes of enthusiastic visitors.

The contrast between organic growth in Korean towns and the spontaneous boom in European villages like Iseltwald highlights critical factors. Locally coordinated strategies, preparedness and managed growth tend to yield more sustainable outcomes. Yet even unplanned surges can be harnessed—if responded to with planning, investment and community engagement.

Infosys will acquire a 75 percent stake in Versent Group, the cloud‑focused digital transformation specialist wholly owned by Telstra, for A$233.3 million, in a joint venture aimed at accelerating artificial intelligence‑enabled cloud and digital services across Australia. The deal, positioning Infosys as majority operator with Telstra retaining a 25 percent interest, is expected to complete in the second half of fiscal year 2026, contingent on approval from Australia’s Foreign Investment Review Board and Competition and Consumer Commission.

Versent brings to the table its team of 650 engineers, advisors and strategists and deep expertise in serving large‑scale sectors such as finance, utilities, energy, education and government. Infosys plans to infuse this local engineering capability with its global strengths—particularly its AI suite including Infosys Topaz, cloud platform Infosys Cobalt, and cybersecurity services from The Missing Link—to deliver comprehensive digital transformation solutions across Australian enterprise and government clients.

The transaction sparked a positive market reaction. Infosys’s US‑listed shares climbed 1.6 percent to US$16.33, while shares traded in India leapt 2 percent to ₹1,449.90.

This JV marks a significant stride in Infosys’ global AI‑cloud strategy and broadens its footprint in Australia. For Telstra, the move aligns with its broader transformation ambitions, where leadership under CEO Vicki Brady is steering the business toward becoming more software‑centric and AI‑first. As part of this shift, Telstra has embraced extensive AI deployment—covering operations such as fault detection, customer support enhancement and efficiency gains—and introduced 21,000 Microsoft Copilot licences along with a dedicated data and AI academy for staff upskilling.

While Telstra has enacted workforce reductions—550 roles eliminated in its enterprise division—company executives emphasise these changes result from structural realignment, not AI, and promise support for affected employees.

Kaspersky reports a dramatic escalation in cyber‑attacks across Sub‑Saharan Africa during the first half of 2025 as the company prepares to lead discussions in Lagos on strengthening regional defences. Data shows that web‑based threats soared to 42.4 million incidents, while on‑device attacks—including malware delivered via USB drives and hidden installers—reached 95.6 million, both representing sharp increases from a year earlier. Spyware attacks more than doubled, password‑stealer incidents rose by […]

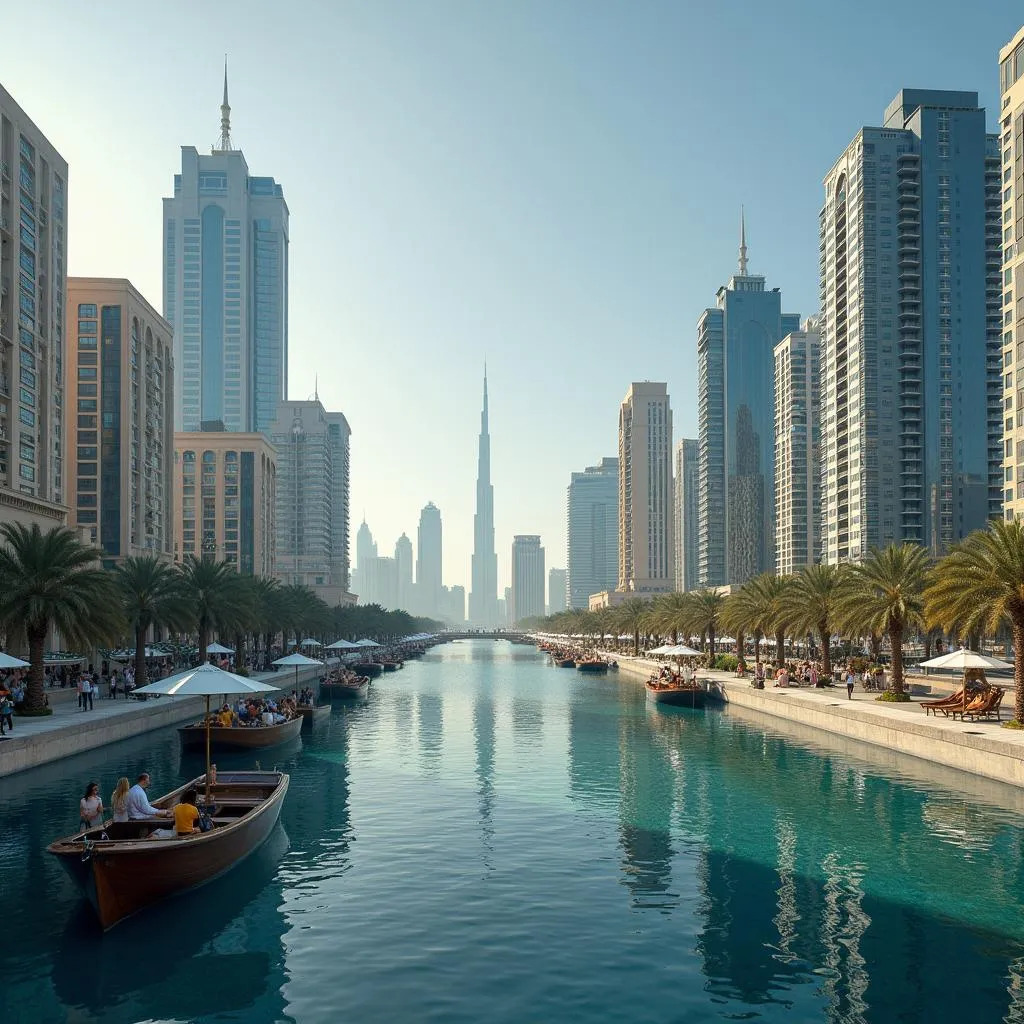
Dubai’s top-tier residential sector continues to outperform the global market, with capital values climbing over 5 per cent in the first half of 2025 and rental returns holding firm.

Dubai’s prime residential property market emerged as one of the strongest worldwide, ranking third behind Tokyo and Berlin in capital value growth during the first six months of 2025. Prime capital values rose by over 5 per cent, substantially ahead of the 0.7 per cent average recorded across 30 global cities. This momentum reflects robust investor confidence, sustained immigration and constrained luxury supply. Savills projects further gains of between 4 and 5.9 per cent in the second half of the year, underscoring the city’s enduring appeal for global investors.

Rental markets in the emirate also remain buoyant. Prime rental rates rose by 2.9 per cent over the past six months and have surged by 13.3 per cent year-on-year to June 2025. High renewal rates and continued demand from high-net-worth individuals and long-term residents have contributed to sustained rental resilience.

Across Savills’ global index of prime markets, Tokyo led with an 8.8 per cent increase in capital values, driven by acute scarcity of stock and strong demand from both domestic and international buyers. Dubai, Berlin and Seoul each recorded gains exceeding 5 per cent, with supply constraints emerging as a key driver across these markets.

Savills’ analysis highlights a shift in global dynamics: prime rental growth across these cities reached 2 per cent on average, outpacing capital appreciation. Just over half of the markets monitored logged positive capital growth in the period, and declines in others were largely modest.

In Dubai, the combination of sustained immigration flows, investor-friendly policies and limited high-end housing supply continues to buttress market strength. A mature mortgage environment—with 15–30-year loan options and competitive deposit requirements, including 15 per cent for citizens and 20 per cent for expatriates—offers further support to both local and foreign investors, with financing often used strategically to manage capital and liquidity.

The emirate’s global connectivity, ever-expanding infrastructure developments and relatively low transaction costs further reinforce its position as a global real estate powerhouse.

Although the pace of rental inflation across general residential segments has slowed—with broader market indices showing deceleration from 14.3 per cent in January to 8.5 per cent in May—prime residential rentals remain robust and significantly outpace broader averages.

While anecdotal evidence and other data point to a record-breaking bull run in Dubai’s real estate sector—with average property prices rising by some 75 per cent since early 2021 and transactions approaching pre-2008 levels—these trends can come with cautionary signals regarding sustainability over the medium term.

Kenya Airways has reported a pretax loss of 12.17 billion Kenyan shillings in the first half of 2025, marking a sharp reversal from the 634 million shilling profit earned in the same period last year. The slump is largely attributed to grounded aircraft—three Boeing 787-8 Dreamliners were sidelined for maintenance, constraining capacity and dragging down revenue to 74.5 billion shillings from 91.5 billion shillings previously. In response […]

SHENZHEN, CHINA – Media OutReach Neswire – 26 August 2025 – On August 26, 2025, Linklogis Inc. (09959.HK, “Linklogis”) released its interim results. In the first half of 2025, the total transaction volume processed by its technology solutions reached RMB 203.6 billion. The total revenue and income amounted to RMB 374.5 million. The number of anchor enterprise and financial institution customers for its supply chain finance technology […]

By Nitya Chakraborty Prime Minister Narendra Modi will be facing his major test in diplomacy at the coming summit of the Shanghai Cooperation Organisation (SCO) to be held in Tianjin in China on August 31 and September 1 this year. The SCO meet will be hosted by Chinese President Xi Jinping and will be attended […]
Advertisements

MACAU SAR – Media OutReach Newswire – 25 August 2025 – Galaxy Macau™’s world-class Galaxy Arena is proud to announce the renewal of its three-year strategic partnership with TMElive, extending its existing three-year run of its successful partnership. Under the newly extended agreement, both parties will continue supporting Macau’s quality development in culture and tourism and presenting multifaceted musical spectacles to music lovers, by leveraging shared resources […]

The GCC debt capital market is gearing up for a surge of new issuances following an active start to the year, despite a quiet period during the early days of August. With the market showing strong resilience, experts predict that the second half of the year could bring new opportunities for issuers, albeit under certain market conditions.

The first half of 2025 witnessed robust activity in the debt market, with significant bond and sukuk issuances across the Gulf Cooperation Council region. Several large corporations, sovereigns, and financial institutions took advantage of favourable conditions, including low interest rates, to raise funds and meet liquidity needs. This rush of issuances demonstrates the ongoing demand for GCC debt despite global economic uncertainties.

Victor Mourad, Co-Head of CEEMEA Debt Financing at Citi, highlighted the market’s performance, noting that the first half was particularly strong. “We had a phenomenal first half,” Mourad said. “The pipeline in the second half could be smaller, unless a drop in rates sparks a pre-funding strategy toward year-end, pulling transactions planned for early 2026 into November.” He pointed out that the timing of issuances would depend on a combination of factors, particularly the interest rate environment.

The market cooled off in the first three weeks of August, a period traditionally marked by lower activity, as many market players take a break before gearing up for the final months of the year. However, Mourad remains optimistic, suggesting that a rate reduction in the coming months could lead to a wave of issuances in the final quarter, as companies and governments look to lock in favourable terms before rates climb again.

Issuers are likely to adopt a strategic approach in the second half, with many considering early funding to avoid higher borrowing costs in 2026. A drop in rates could accelerate this strategy, as issuers push forward deals planned for the following year. It remains to be seen whether this shift in strategy will materialise, but the potential for an uptick in transactions towards the year-end remains high.

Investors will also play a key role in shaping the market dynamics. With yields on GCC bonds still appealing compared to those in other regions, demand for debt from the Gulf is expected to remain strong. The relatively stable economic backdrop, coupled with favourable oil prices, offers an attractive investment proposition for global investors looking for higher returns in a low-interest-rate environment.

Another crucial factor influencing the market will be the sovereign debt landscape across the GCC countries. Governments have continued to implement fiscal reforms and drive diversification efforts, which have bolstered the creditworthiness of the region’s sovereign issuers. As a result, GCC sovereign bonds have become a key asset class for international investors, offering a blend of safety and yield in uncertain times.

Corporate issuers in the region have also adapted to the shifting dynamics. Many have been tapping into the capital markets to fund expansion plans and refinance maturing debt, while also benefitting from government-backed stimulus packages. These initiatives have helped to stabilise the regional economy and offer liquidity to businesses during challenging periods.

However, challenges remain for certain sectors, particularly those heavily reliant on global supply chains or exposed to geopolitical risks. Tensions in the wider Middle East region could create volatility, which might impact investor sentiment. As the global economy continues to grapple with inflationary pressures and tightening monetary policies, GCC issuers will need to balance their strategies carefully to ensure they remain attractive to both local and international investors.

Wall Street surged on Friday as Federal Reserve Chair Jerome Powell’s address at the Jackson Hole symposium signposted a shift in policy direction, lifting the Dow to its highest closing level of 2025. The Dow climbed by around 1.9 per cent, the S&P 500 rose 1.5 per cent, and the Nasdaq jumped by roughly 1.9 per cent. This rally reversed a recent downturn and came amid rising […]

Leveraging B2C and B2B Synergies to Capitalize on the Global K-Beauty Boom Results Highlights Revenue rose by 49.3% to US$243.93 million. Operating profit increased by 31.9% to US$18.68 million. Net profit grew by 26.7% to US$14.08 million. Business-to-Customer (B2C) YesStyle Platforms recorded revenue of US$164.86 million, up 31.7%, contributing 67.6% of the Group’s total revenue. Revenue of Business-to-Business (B2B) platform AsianBeautyWholesale surged by 110.9% to US$77.94 million, […]

The first half of 2025 marked a significant surge in greenfield foreign direct investment into Saudi Arabia, with the United States leading the charge. American investors drove 61 projects, injecting $2.7 billion into the Kingdom’s economy, accounting for nearly a third of both the project count and total investment. This surge highlights the growing confidence of international investors in Saudi Arabia’s Vision 2030 economic reforms and its appeal as a business hub in the region.

According to a report by Emirates NBD, greenfield investments in Saudi Arabia showed a notable increase, both in terms of project volume and capital inflow. In total, 203 greenfield projects were launched in Saudi Arabia during the first half of 2025, marking a 30.1% year-on-year rise. These projects, spanning across various sectors, reflect the country’s strong development trajectory and its efforts to diversify away from oil reliance.

Egypt emerged as the second largest contributor to Saudi Arabia’s greenfield FDI, securing $1.81 billion through 11 projects. Many of these ventures were centered around real estate developments, capitalising on the Kingdom’s expanding urbanisation and demand for residential and commercial properties. Egypt’s growing involvement reflects deeper ties between the two nations, particularly in sectors related to infrastructure and housing.

China, a global FDI powerhouse, played a significant role as well, investing $858.3 million through 11 projects in Saudi Arabia. China’s investments in the Kingdom primarily focused on manufacturing, technology, and energy, complementing the Saudi government’s drive to expand its industrial base and modernise key sectors. Chinese companies are also playing a pivotal role in the development of high-tech infrastructure, which aligns with Saudi Arabia’s push towards a more diversified, knowledge-based economy.

France also made its presence felt, contributing $771.7 million through six greenfield projects. The French investments were primarily focused on technology, retail, and luxury goods, with several high-end brands expanding their operations within the Kingdom. France’s engagement is part of a broader European interest in tapping into Saudi Arabia’s expanding consumer market, particularly in areas linked to fashion, entertainment, and sustainable energy.

The UAE’s regional influence continued to grow, with 25 projects worth $205.3 million being launched in Saudi Arabia. These ventures spanned various industries, with a focus on hospitality, logistics, and real estate. The UAE’s investments underscore the close business ties between the two countries, with the Kingdom remaining a key destination for Emirati capital looking to expand its footprint in the region.

Riyadh, Saudi Arabia’s capital, was the top destination for greenfield FDI, attracting 100 projects valued at $2.3 billion. As the political, economic, and cultural centre of the country, Riyadh continues to benefit from the majority of investments, particularly in the areas of technology, infrastructure, and urban development. Dammam, home to one of the Kingdom’s key industrial hubs, secured 21 projects worth $1.28 billion, while Jeddah followed closely with 13 projects totalling $1.22 billion. These cities represent strategic focal points in Saudi Arabia’s ambitious plans for diversification, driven by growth in manufacturing, logistics, and energy.

Saudi Arabia’s overall greenfield FDI rose by 1.7% to $9.34 billion during the first half of 2025, reflecting the Kingdom’s position as an attractive investment destination. The growth is seen as a direct result of efforts to enhance the ease of doing business in the country and to create a more transparent regulatory environment. Initiatives like the National Industrial Development and Logistics Program and the Saudi Green Initiative have been instrumental in drawing foreign investments into the Kingdom.

Implementing the Core Strategy of “Single Brand, Multi-Categories, Diversified Channels” | Excelling Through Professionalism, Strengthening Strategic Foundations FINANCIAL HIGHLIGHTS In the first half of the year, the Group recorded the following operating results: – Revenue rose by 3.3% to RMB14,817 million; gross profit margin declined by 0.4 percentage points to 50% – Net operating cash inflow was RMB2,411 million – Net profit attributable to equity holders was […]

HANOI, VIETNAM – Media OutReach Newswire – 21 August 2025 – Vingroup (Ticker: VIC) has been recognized as the largest private contributor to Vietnam’s state budget, with total payments exceeding VND 56.2 trillion. This figure accounts for nearly 40% of the total contributions from the Top 10 enterprises on the list. The National Exhibition Fair Center, inaugurated on August 19, stands as a testament to Vingroup’s credibility […]

Hedge funds are experiencing an unprecedented influx of capital as investors increasingly turn to them for potential high returns in an unpredictable market landscape. The surge, described as the largest in over a decade, comes amid heightened volatility in global markets, with investors seeking refuge in strategies that can navigate turbulent times.

The influx is reflective of broader economic uncertainties that have marked the past few years. Inflation, interest rate fluctuations, and geopolitical tensions have prompted a shift in how investors are approaching their portfolios. For many, hedge funds, which are designed to capitalise on market inefficiencies and often utilise a mix of complex investment strategies, have become a more attractive option for diversifying risk.

Industry analysts attribute the renewed interest to hedge funds’ ability to hedge against downside risks while still positioning themselves for upside potential. These funds, which include strategies such as long/short equity, event-driven, and macroeconomic investing, are seen as flexible enough to take advantage of both market downturns and rallies.

The timing of this shift is significant, with hedge fund inflows peaking in the first half of this year. According to reports, the volume of new money invested in hedge funds has surpassed previous records, with institutional investors making up the majority of the capital. Pension funds, endowments, and family offices have notably increased their allocations, recognising the potential benefits of diversifying into hedge funds’ more sophisticated strategies.

This trend is also linked to the performance of hedge funds in recent years. After a period of underperformance following the global financial crisis and the subsequent slow recovery, hedge funds have returned to form, outpacing traditional equity indices in certain periods. While not all hedge funds have delivered stellar returns, the overall industry has shown resilience and adaptability, particularly in the face of market turbulence.

One of the critical drivers behind this renewed interest is the diversification factor. Hedge funds often employ strategies that are less correlated with traditional markets, allowing them to profit from opportunities that might not be available to standard equity investors. For example, in a period of high volatility or economic downturn, many hedge funds profit from short-selling overvalued stocks, participating in distressed asset sales, or capitalising on arbitrage opportunities.

However, the strategy comes with inherent risks. While hedge funds aim to mitigate risk through their sophisticated techniques, they are not immune to market downturns. Moreover, the fees associated with hedge funds—usually a performance fee based on profits earned—can be a deterrent for some investors. These fees often include a “two and twenty” structure, meaning the fund takes a 2% management fee and 20% of any profits generated, which can substantially erode returns for the investor.

Despite the risks, the demand for hedge funds remains strong. Their perceived ability to manage volatility and generate alpha—the excess return relative to the market—has attracted a growing number of high-net-worth individuals looking for alternatives to the traditional stock and bond markets. The shift in investment patterns suggests a broader reevaluation of risk, with more investors open to the idea of using hedge funds as part of their long-term asset allocation strategy.

Another contributing factor to the surge in hedge fund investments is the growing acceptance of environmental, social, and governance factors within the industry. Many hedge funds have incorporated ESG strategies into their models, appealing to institutional investors who are placing greater emphasis on sustainability and ethical governance. Hedge funds with a track record of navigating ESG challenges have become particularly attractive to a new generation of investors who are focused not just on financial returns but on social and environmental impact as well.

The global economic environment is expected to remain volatile, with central banks’ monetary policies, inflationary pressures, and geopolitical instability all factors that will influence market dynamics. Hedge funds, with their adaptive strategies, are likely to continue drawing significant attention as investors seek to position themselves to take advantage of potential market dislocations.

The United States has emerged as the dominant force in greenfield foreign direct investment in Saudi Arabia for the first half of 2025. Accounting for 61 projects with a combined value of $2.7 billion, American investments represented nearly a third of the total project count and capital investment during the period, according to a report by Emirates NBD. Saudi Arabia continues to be an attractive destination for […]

Greenlogue/AP The United States has solidified its position as the leading source of greenfield foreign direct investment in Saudi Arabia during the first half of 2025, with American companies backing 61 projects worth a total of $2.7 billion. This surge in American investments marks a significant shift in global investment trends, as US-based firms continue to bolster the Kingdom’s economic diversification efforts under its Vision 2030 initiative. […]

The third edition of the AlUla Desert Blaze concluded on Saturday night, with more than 500 runners from Saudi Arabia and across the globe competing in one of the most gruelling desert races in the region. Held at the UNESCO World Heritage site of Hegra, the event offered a choice of four race categories: 5 km, 10 km, 21.1 km, and 42.2 km. Starting early at 8:00 […]

By Nitya Chakraborty The prospects of arriving at a peace agreement between Ukraine and Russia to end the nearly three and half year old war have brightened after the Monday meeting of President Donald Trump with the Ukraine President Volodymyr Zelensky at the White House in the presence of the major European government heads. As […]

The United Arab Emirates registered some US$25.4 billion in mergers and acquisitions through the first six months of 2025, making up approximately 43 per cent of all M&A transactions across the Middle East and North Africa—which totalled US$58.7 billion during the period, according to data from EY’s latest MENA M&A Insights report.

MENA deal-making demonstrated robust momentum in the first half of 2025, with 425 transactions reflecting a 31 per cent increase in volume and a 19 per cent rise in overall value compared with the same period in 2024, as EY’s analysis shows.

Cross-border activity surged, accounting for 55 per cent of all deals by number and 78 per cent by value—marking the highest cross-border level in the past five years. Key sectors driving these overseas transactions included chemicals and technology, which together represented two-thirds of cross-border deal value. Among the most significant was the US$16.5 billion deal in which Borealis AG and OMV AG acquired a 64 per cent stake in Borouge plc.

Domestic deal-making remained energetic too. Homegrown transactions constituted 45 per cent of all deals by volume and 22 per cent of the total value, amounting to 192 deals worth US$12.8 billion—an impressive 94 per cent year-on-year rise in value. The technology and diversified industrial products sectors were prominent in this category. A standout deal was AI and cloud services firm Group 42’s acquisition of a 40 per cent stake in Khazna Data Centres for US$2.2 billion.

EY’s MENA EY-Parthenon Leader, Brad Watson, emphasised that the mid-year results underline how resilient and dynamic the region’s M&A market is. He pointed to sustained appeal for investors, underpinned by stable oil prices, infrastructure expansion and a strategic emphasis on growth industries such as technology, chemicals, and industry. I n particular, he noted that the UAE continues to attract significant global capital, thanks to its strong regulatory environment and push for economic diversification, alongside growing collaborative ties with Europe, Asia, and North America.

When compared with mid-2024 performance, the jump is clear. In the first half of last year, the MENA region recorded 321 deals valued at US$49.2 billion. That represented only a modest 1 per cent increase in volume and 12 per cent growth in value over the prior year. Deal values in the UAE and the Kingdom of Saudi Arabia accounted for US$9.8 billion out of that total.

Looking at the broader picture, 2024 closed with 701 MENA M&A deals worth US$92.3 billion, reflecting a 3 per cent rise in deal volume and 7 per cent gain in value compared with 2023. Cross-border transactions were the primary engine, making up 52 per cent of deal volume and 74 per cent of value.

The UAE’s growing prominence in M&A stems from both deliberate policy reforms and strategic positioning. Domestic investors, notably sovereign wealth funds and government-related entities such as ADIA and Mubadala, have been highly active across both home-market and international transactions. At the same time, global investors have responded favourably to the region’s economic diversification efforts, regulatory clarity, and infrastructural thrust.

China’s reliance on fossil fuels has been steadily declining despite increasing energy demand, marking a significant shift in the nation’s energy landscape. Coal and gas consumption saw a dip in 2025, even during a scorching July, as the government continues to prioritise clean energy sources. This is a clear sign that China’s aggressive push towards renewable energy and energy efficiency is beginning to take effect, even as the country faces unprecedented challenges in meeting its growing power needs.

Data from the National Energy Administration revealed that, in the first half of 2025, coal usage in the energy mix fell by 5% compared to the same period last year, while natural gas consumption also showed signs of contraction. The most striking development came in the power sector, where a surge in renewable energy production, particularly from solar and wind sources, helped to reduce dependency on fossil fuels.

China’s power demand soared during the summer, driven by an intense heatwave that gripped much of the country. However, the country was able to meet this surge without resorting to its usual fossil fuel-heavy energy production methods. This is partly due to the rapid expansion of its renewable energy capacity, which reached new records in both wind and solar power generation in 2025. The NEA reported that China’s total renewable energy capacity crossed 1,200 gigawatts for the first time, a crucial milestone that reflects the country’s commitment to a cleaner and more sustainable energy future.

One key driver of this change is China’s substantial investment in renewable infrastructure. The government allocated over $60 billion to clean energy projects in 2025, focusing heavily on expanding solar farms and offshore wind installations along the coast. At the same time, China has been making significant strides in energy storage technologies, which are crucial for maintaining grid stability as renewable sources, particularly solar, are intermittent.

While China remains the world’s largest coal producer and consumer, the shift towards clean energy is undeniable. The country’s coal-fired power plants, once the backbone of its energy sector, are now being gradually phased out or repurposed for lower-carbon technologies. The transition has been especially evident in regions like Inner Mongolia, where coal consumption has sharply decreased as wind and solar energy projects have taken root.

Industry experts point to a combination of factors driving this shift. First, there is the national government’s ambitious target of reaching carbon neutrality by 2060. Second, the economic pressures on coal mining companies, many of which are facing increasing scrutiny over environmental and public health concerns, are playing a role in reducing coal’s dominance. Moreover, local governments have introduced incentives for businesses to adopt cleaner energy solutions, further encouraging the transition away from fossil fuels.

The reduction in coal and gas use has also been bolstered by the rise of electric vehicles, which now account for a significant portion of the energy demand in urban centres. China’s push to become a global leader in EV manufacturing has contributed to the decrease in fossil fuel consumption in the transportation sector, where electricity now plays an increasingly prominent role.

However, while the momentum towards renewable energy is clear, challenges remain. One pressing issue is the reliability of the grid, especially in remote areas where renewable generation can be less consistent. The government is addressing this concern with the expansion of transmission infrastructure designed to transport power from renewable-heavy regions like the north and west to energy-hungry areas like the east and south.

While the clean energy push is a notable success, fossil fuels still account for a large portion of China’s energy mix. This means that the country remains vulnerable to price fluctuations in global energy markets, as seen in 2024 when rising global gas prices temporarily hindered efforts to reduce fossil fuel reliance.

BEIJING, CHINA – Media OutReach Newswire – 18 August 2025 – The 42nd “Baidui Cup” Football Tournament kicked off in the rain on the August 8th. It brought a refreshing coolness of summer to the young players and once again ignited a football fever in Beijing, the “Dual Olympic City”. A player goes for goal during a Baidui Cup match, August 2025. As 51-year-old Chinese football legend […]

DP World has reported a significant rise in revenue for the first half of 2025, with figures climbing 20.4 per cent to reach $11.24 billion. This growth was primarily driven by strong performance in its Ports & Terminals division, as well as the positive impact of acquisitions completed in recent months. The company’s adjusted EBITDA also saw an impressive increase, up by 21.4 per cent to $3.03 […]

Dubai’s office real estate market has experienced a remarkable upswing, with sales transactions reaching AED5.4 billion in the first half of the year, an 84% year-on-year increase. This surge comes on the back of a dynamic and growing demand for commercial spaces, particularly in the prime office and logistics segments, as noted in Cavendish Maxwell’s latest Dubai Office Market Report. According to the report, the number of […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA