Saudi Arabia has moved to reassure global energy markets that it will remain a dependable supplier as geopolitical shocks, shipping risks and divergent demand forecasts intensify pressure on producers and consumers. Minister of Energy Prince Abdulaziz bin Salman told the 29th St. Petersburg International Economic Forum that stability in the energy sector had become an urgent global requirement. “We are a resilient energy supplier; we have been […]
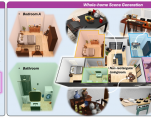
Kairos-HomeWorld is purpose built for embodied intelligence and represents the first unified framework capable of generating a complete, fully interactive home environment from a single text prompt. Extending indoor scene generation beyond individual rooms, it enables whole-home simulation in which every object is fully manipulable within an integrated simulation engine.
Kairos-HomeWorld employs a four-stage hierarchical architecture encompassing floorplan generation, 2D-to-3D lifting, recursive refinement, and manipulable object placement. This approach enables the production of globally coherent, physically accurate, and simulation-ready scenes. Each environment contains more than 15 manipulable objects and achieves a Footprint Object Density of 4.16, the highest among compared methods.
The accompanying open-source dataset is purpose-built for Chinese households, pairing 300,000 real residential floor plans with 5,000 fully furnished, simulation-ready homes and 50,000 physics-enabled interactive object assets. Already deployed in ACE ROBOTICS’ daily robot training, it significantly accelerates the simulation-to-reality transfer cycle.
SHANGHAI, CHINA – Media OutReach Newswire – 5 June 2026 – ACE ROBOTICS, in collaboration with the Multimedia Laboratory at The Chinese University of Hong Kong (CUHK) and Shenzhen Loop Area Institute, today announced the open-source release of Kairos-HomeWorld, the industry’s first unified World Model framework capable of generating full home-scale, object-level interactive 3D environments from a single text prompt. The solution addresses longstanding limitations in indoor scene generation, which has typically been restricted to single-room outputs with weak global consistency and limited interactivity. Kairos-HomeWorld overcomes these constraints by delivering structurally coherent, physically plausible, and functionally complete residential environments. These high-fidelity, large-scale simulations provide a robust foundation for advancing embodied intelligence applications and accelerating real-world robot training.
The long-term vision for embodied intelligence is the home environment. However, residential settings are inherently diverse and highly personalized, requiring robots to be trained across a broad range of realistic and differentiated scenarios before they can reliably operate in even a single household. High-fidelity simulation offers the most practical pathway to achieving this at scale, yet existing approaches typically involve a trade-off: synthetic environments lack realism, while scanned real-world scenes offer limited interactivity. Kairos-HomeWorld, together with its accompanying dataset, is designed to bridge this gap, delivering both realistic and interactive environments within a unified framework.
A four-stage architecture for whole-home, object-level generation Conventional approaches to indoor scene generation remain constrained to single-room outputs, often exhibiting weak global consistency, frequent physical inaccuracies, and limited or no interactivity. Kairos-HomeWorld takes a fundamentally different approach. It decomposes whole-home generation into a structured, four-stage process, redefining the underlying architectural paradigm from the ground up.
Stage 1 — Floor Plan Generation. A K-D tree-based approach translates real-world floor plans into a hierarchical text representation that can be efficiently processed by large language models (LLMs). This method mitigates common issues in conventional layout generation, including room overlaps and fragmented topologies, resulting in more coherent and structurally consistent spatial configurations.
Stage 2 — 2D-to-3D Lifting & Furniture Layout Generation. A “top-down global initialization combined with a first-person detail walkthrough” approach anchors the process to the 3D building shell generated in Stage 1. This methodology mitigates the geometric drift commonly associated with conventional 2D-to-3D lifting techniques, enabling more stable and spatially consistent scene generation.
Stage 3 — Recursive Refinement. A fine-tuned vision-language model performs iterative validation and correction, automatically identifying and resolving physical inconsistencies, such as obstructed doorways or object collisions. This recursive process materially reduces spatial errors, achieving among the lowest reported furniture-collision rates in the industry.
Stage 4 — Manipulable Object Placement. A surface-centric placement algorithm assigns each object detailed physical properties, including material composition, density, friction, and structural support relationships. Each generated scene incorporates an average of more than 15 manipulable objects and achieves a Footprint Object Density (FOD) of 4.16, a metric reflecting the concentration of items across furniture surfaces. All objects are natively compatible with simulation engines, enabling direct interaction for tasks such as grasping, movement, and stacking.
The resulting environments move beyond “viewable but not actionable” outputs. Their coherent spatial structure enables seamless, continuous navigation across multiple rooms, while objects embedded with realistic physical properties allow robots to simulate complex household tasks end-to-end. Taken together, this approach addresses key limitations in existing data pipelines, resolving the scarcity of high-quality 3D simulation data, the lack of realism in synthetic environments, and the limited interactivity of scanned scenes within a single unified framework.
The dataset: 300,000 real floor plans, 5,000 fully interactive homes, built for Chinese households ACE ROBOTICS and CUHK are open-sourcing a dataset of 300,000 structurally annotated residential floor plans, sourced from real-world listings and processed through a multi-stage automated pipeline. The pipeline vectorizes and labels key spatial elements, including door and window positions, room geometry, functional zoning, and connectivity. By comparison, widely used benchmarks such as RPLAN and ResPlan contain approximately 80,000 and 17,000 floor plans, respectively, underscoring the scale and comprehensiveness of the Kairos-HomeWorld dataset.
Building on this foundation, the dataset also includes 5,000 fully furnished residential environments, each featuring a complete furniture layout and an average of more than 15 physics-enabled, manipulable objects, powered by the PhysX-Omni model. All assets are sim-ready and can be directly imported into a simulation engine, enabling immediate use in interactive training scenarios.
Most existing open indoor-scene datasets are centered on North American and European residential formats, typically featuring open-plan kitchens, the absence of service balconies, and layouts and design elements that capture only a narrow segment of global housing. As a result, robots trained on these datasets often exhibit limited transferability when deployed in environments outside their scope. Kairos-HomeWorld ‘s dataset is purpose-built for Chinese households, with deliberate coverage of historically under-represented housing typologies. It spans a wide range of unit sizes, from approximately 30 m² (around 320 sq ft) studio apartments to residences exceeding 200 m² (approximately 2,150 sq ft). The dataset accurately reflects key architectural features common in these settings, including north-south cross-ventilated layouts, enclosed kitchens, dedicated service balconies, wet-and-dry-separated bathrooms, and entryway storage, as well as the irregular room configurations often found in older housing stock.
The dataset is being openly released to both academic and industry communities. Going forward, the team plans to expand its scope to include additional regions, interior styles, and interaction scenarios, further lowering barriers to real-world-ready training for embodied intelligence.
See it in action: one prompt to a fully interactive home Kairos-HomeWorld runs the full end-to-end pipeline, from initial text input to a fully interactive home environment, delivering global spatial consistency, physical realism, and seamless interactivity from a single prompt.
The system begins with a single-line prompt: “Generate a 90 m² (approximately 970 sq ft) two-bedroom apartment in neo-Chinese style.” Leveraging real floor plan data and its K-D tree representation, Kairos-HomeWorld first constructs an empty spatial layout aligned with real-world living patterns, incorporating cross-ventilation and well-defined functional zoning. Building on this foundation, a hierarchical “global layout plus first-person detail” approach furnishes the environment with stylistic coherence, while a PhysX-Omni rendering pass assigns full physical properties to all surfaces and objects, including articulated behavior, ensuring the scene is fully interactive and sim-ready.
A single natural-language instruction, “tidy the whole home”, is decomposed by the robot into a variety of discrete sub-tasks, executed sequentially along a complete navigation path spanning the living room, bedrooms, kitchen, bathroom, and dining area. The robot recognizes objects, plans efficient routes, and performs precise manipulation tasks, including articulated-object interactions for opening refrigerator and cabinet doors, fluid interactions for pouring laundry detergent, soft-body interactions for drawing curtains, irregular-object interactions for grasping apples, and gravity-based physical interactions for placing snacks.
Conventional simulation environments typically support navigation-focused training in isolation. By contrast, Kairos-HomeWorld integrates globally consistent spatial structures with objects that embody realistic physical properties. This enables robots to interact naturally with more than 15 object types, accurately modeling real-world dynamics such as collision, gravity, and friction, and to rehearse the full lifecycle of complex household tasks entirely within a virtual environment.
Across the industry, the same structural bottleneck, the scarcity of home-scale training data, is being addressed through multiple approaches. For example, Figure AI’s collaboration with Brookfield focuses on collecting human activity data across more than 100,000 residential units. Kairos-HomeWorld addresses this challenge through on-demand synthetic generation, delivering scalable training environments enhanced with object-level physical realism, capabilities that real-world data capture alone cannot fully provide.
In contrast, Kairos-HomeWorld delivers significantly lower costs and higher efficiency for household robot training. Powered by its world model, it can programmatically generate diverse Chinese home simulation scenes and physics-enabled interactive objects at scale.
Robots can complete a full range of household tasks training entirely within the virtual environment. New scene generation incurs near-zero marginal cost, eliminating substantial real-world testing expenses such as site operation and maintenance and furniture damage. Meanwhile, unconstrained by the limited stock of physical residential properties, it outperforms real-world data collection approaches in both training efficiency and scalable expansion.
Kairos-HomeWorld is already deployed in ACE ROBOTICS’ embodied intelligence training workflows, enabling full-pipeline simulation of long-horizon household tasks, including cross-room navigation and multi-room tidying. By allowing robots to rehearse complete task sequences in a virtual environment, the platform significantly shortens the simulation-to-reality transfer cycle. This approach lowers barriers to developing embodied intelligence systems and supports the accelerated, large-scale deployment of home robotics, particularly within the Chinese market. Kairos-HomeWorld is now available on GitHub.Hashtag: #ACEROBOTICS
The issuer is solely responsible for the content of this announcement.
About ACE ROBOTICS
Equipping robots with intelligent “brains” and engaging “souls”.
ACE ROBOTICS is a pioneering robotics company dedicated to advancing the field of embodied intelligence. Through breakthrough technological innovations and deep insights into embodied intelligence scenarios, we aim to empower robots with the ability to autonomously understand and explore the physical world, thereby accelerating their commercial implementation.
The company pioneered the ACE R&D paradigm and built a vision-based “environmental data engine, real-world cognition, embodied interaction generalization” technology chain. Using full spatiotemporal and multi-perspective environmental capture as its engine, along with Kairos 3.0 – China’s first open-source and commercially applicable world model – plus the Embodied Foundation Model as its technical backbone, ACE ROBOTICS addresses core industry challenges such as data scarcity, common sense gaps, poor generalization, and limited versatility. Simultaneously, the company unveiled its flagship A1 Embodied Super Brain Module, accelerating the large-scale commercial deployment of embodied intelligence across diverse scenarios.
ACE ROBOTICS is both a technology pioneer and an ecosystem builder. Through strategic cooperation with top hardware manufacturers, cloud service providers, and vertical scenario partners, we have broken through the “model-hardware-scenario” industrial deadlock, providing standardized and customized solutions that are driving the development of China’s embodied intelligence industry.
SHANGHAI, CHINA – Media OutReach Newswire – 5 June 2026 – SKYWORTH Solar has reinforced its commitment to Thailand’s growing clean energy sector following the opening of its Bangkok office and the signing of a 100MW commercial and industrial (C&I) solar project memorandum of understanding with local partner CapSolar.
The announcement forms part of SKYWORTH Solar’s newly unveiled global growth strategy, revealed at the 2026 SNEC Exhibition and Global Customer Summit in Shanghai, where the company introduced its new positioning as a “Global Smart Energy Ecosystem Leader” and outlined plans to accelerate expansion across key international markets.
Thailand has emerged as one of SKYWORTH Solar’s strategic markets in Southeast Asia, driven by rising energy demand, increasing electricity costs for businesses, and growing momentum behind renewable energy adoption.
The opening of the company’s Thailand office at Empire Tower in Bangkok strengthens SKYWORTH Solar’s local presence. It enables the company to provide customers and partners with enhanced support across consultation, project execution, after-sales service, supply chain coordination and project delivery.
“Thailand represents a significant growth opportunity for SKYWORTH Solar as businesses increasingly seek reliable and cost-effective clean energy solutions,” said Wanfei Qu, Chief Investment Officer of SKYWORTH Group, CEO and Director of SKYWORTH Solar. “Our strategy is built on the principle of ‘Global Vision, Local Execution’, combining global expertise with strong local partnerships to support Thailand’s energy transition and long-term sustainability goals.”
As part of its expansion plans, SKYWORTH Solar signed a 100MW C&I solar project MOU with CapSolar, supporting the growing demand for rooftop solar solutions among commercial and industrial businesses.
The company is also strengthening its local ecosystem through investments in project development, financing partnerships and service capabilities. This includes a strategic banking collaboration with ICBC Thai and access to a US$500 million investment fund to support solar project development and deployment in Thailand and other international markets.
One example of SKYWORTH Solar’s growing footprint in Thailand is its 3MW rooftop solar project at UMC Steel Plant in Chonburi Province. The project is expected to generate approximately 4.4 million kWh of clean electricity in its first year, helping reduce energy costs while supporting the facility’s sustainability objectives.
The developments in Thailand were highlighted as part of SKYWORTH Solar’s broader global strategy unveiled at SNEC 2026. The company announced plans to expand its solar, energy storage, and integrated smart energy solutions across Europe, Southeast Asia, the Middle East, and Africa, in response to increasing global demand for renewable energy technologies.
As governments and businesses accelerate their decarbonisation efforts, SKYWORTH Solar aims to support customers through a combination of advanced technology, flexible business models and localised service capabilities.
For more information about SKYWORTH Solar and its clean energy solutions, please visit https://www.skyworth-pv.com. Hashtag: #SKYWORTH
The issuer is solely responsible for the content of this announcement.
About SKYWORTH
SKYWORTH Solar, the cutting-edge PV brand under SKYWORTH Group, is a global leader in providing comprehensive one-stop solar solutions. Comprehensive end-to-end services are provided, encompassing consulting, design, and product O&M, all supported by a portfolio of self-developed solutions.
As a leading global renewable energy developer, service provider and energy solutions provider, SKYWORTH is actively shaping the future of energy. With a strong presence in EPC services and one-stop product solutions, SKYWORTH delivers high-quality, reliable, and innovative energy solutions. SKYWORTH ‘s commitment to originality and excellence has earned widespread recognition in international markets such as Germany, Italy, the UK, Brazil, and Senegal.
Thailand’s richest man Sarath Ratanavadi is preparing a 140 billion baht expansion through Gulf Development Pcl over five years, placing data centres, digital infrastructure and power supply at the centre of one of Southeast Asia’s most ambitious corporate bets on artificial intelligence demand.
The plan, worth about $4.3 billion, reflects a sharp turn by Gulf from its traditional base as a power producer into a broader infrastructure group linking electricity generation, telecommunications, cloud services and industrial logistics. The investment push comes as Thailand seeks to position itself as a regional data hub, helped by rising demand for cloud computing, artificial intelligence workloads and data-localisation capacity across Southeast Asia.
Gulf’s strategy is built around a simple commercial premise: AI facilities need vast, reliable and increasingly low-carbon electricity. Data centres are among the most power-intensive assets in the digital economy, and operators are under pressure to secure stable energy supply while meeting sustainability commitments from global technology clients. Gulf’s existing position in gas-fired power, renewable energy and utilities gives it an advantage that pure technology infrastructure firms may struggle to match.
Sarath, Gulf’s chief executive and controlling figure, has spent years reshaping the group from a conventional energy developer into a conglomerate with exposure to telecoms, satellites, digital platforms and cloud infrastructure. The merger of Gulf Energy Development and Intouch Holdings created a larger listed platform linked to Advanced Info Service, Thailand’s biggest mobile operator, and Thaicom, the satellite company. That structure gives Gulf access to telecom traffic, enterprise clients and digital distribution channels that can support its data-centre ambitions.
The investment programme is expected to support new data-centre capacity, related infrastructure and power projects needed to serve hyperscale and enterprise customers. Gulf has already moved into the sector through partnerships involving global technology names and regional operators, while its digital arm has explored cloud and AI services designed for corporate and government clients. The company’s first major data-centre project has become a reference point for its expansion into facilities that can host high-density computing workloads.
Thailand’s broader investment environment has also shifted in Gulf’s favour. Authorities have approved large-scale data infrastructure projects from global technology players, including server and data-processing investments across Bangkok, Samut Prakan and Chachoengsao. Google, Amazon Web Services, Microsoft and ByteDance-linked operations have all announced or pursued major commitments in the country, intensifying competition but also validating Thailand’s role in the regional digital economy.
For Gulf, the opportunity lies not only in renting data-centre capacity but also in selling bundled infrastructure: power, connectivity, cloud access and long-term operational reliability. That model could create recurring income and reduce dependence on regulated returns from power generation. It may also help Gulf deepen its relationship with large technology clients seeking local partners that understand land, energy approvals, grid constraints and domestic regulatory requirements.
The group’s financial position gives it room to move, though the scale of the programme will be closely watched by investors. Gulf reported strong first-quarter earnings for 2026, helped by its energy operations and profit contribution from Advanced Info Service. Revenue growth and core profit gains have strengthened confidence in its ability to finance new projects, but data centres require heavy upfront spending and returns can depend on utilisation rates, long-term contracts and energy costs.
The timing is also sensitive. Across Asia, governments are competing for data-centre investment while confronting pressure on power grids, water use and land availability. Singapore’s cautious approach to new data-centre capacity has encouraged developers to look at Malaysia, Thailand, Indonesia and Vietnam, but each market faces its own constraints. Thailand has industrial land, policy incentives and improving connectivity, yet grid readiness and clean-energy availability remain decisive issues for hyperscale clients.
Gulf’s renewable energy targets are likely to form part of its sales pitch. The company has set out plans to raise the share of renewables in its generation portfolio and reduce carbon intensity, while continuing to rely on gas as a stable baseload fuel. Its long-term LNG supply arrangements also point to a strategy that balances energy security with transition commitments, even as customers demand cleaner electricity for digital operations.
Sarath’s expansion plan underscores how AI is redrawing corporate strategy beyond Silicon Valley. Energy groups, telecom operators and infrastructure funds are increasingly competing for the physical assets behind the digital boom. Gulf’s bet is that Thailand’s AI economy will be shaped as much by power plants, fibre networks and industrial sites as by software models and cloud applications.
Greenlogue/AP Dubai Electricity and Water Authority has raised clean energy’s share of its total production capacity to 21.5%, strengthening the emirate’s shift towards a lower-carbon electricity system as demand for power continues to rise across residential, commercial and industrial sectors. Saeed Mohammed Al Tayer, Managing Director and Chief Executive Officer of DEWA, said the increase reflects Dubai’s long-term strategy to align infrastructure growth with environmental sustainability, […]
Arabian Post Staff -Dubai Abu Dhabi Exports Office has begun direct site visits to UAE-based manufacturers under its AED1 billion financing partnership with Emirates Development Bank, stepping up efforts to link industrial companies with export funding, working capital support and market-expansion tools. The visits covered MEDECO, Star Paper Mill and Dana Steel, three manufacturers operating in sectors closely tied to the country’s localisation and export-growth agenda. ADEX […]
By Dr. Gyan Pathak The preliminary version of the OECD Outlook released on June 3, 2026 has projected the real GDP of India to grow by 6.3% during the FY 2026-27, which is a sharp decline from the robust growth rate of 7.8 per cent year-on-year in the quarter ending in December 2025 (Q3 FY2025–26), […]
Gas engine manufacturer Innio has raised $2.43 billion in a US initial public offering, pricing an upsized share sale at the top of its marketed range as investors continue to chase companies tied to the electricity demands of artificial intelligence. The Munich-based distributed energy group priced 90 million shares at $27 each, above the 75 million shares originally planned and at the upper end of the $24 […]
Arabian Post Staff -Dubai Abu Dhabi has temporarily halted rent increases across residential, commercial and industrial properties, cutting the permitted annual rise from 5 per cent to 0 per cent until further notice. The measure applies to tenancy contract renewals across the emirate and means rents must remain unchanged for the duration of the freeze. New tenancy contracts for previously rented units must also be registered at […]
Bull and Hon Hai Technology Group, better known as Foxconn, will manufacture artificial intelligence and cloud infrastructure in Europe under a strategic partnership designed to strengthen the region’s computing supply chain and reduce dependence on external technology providers. The project will use Foxconn’s manufacturing base in Pardubice in the Czech Republic and Bull’s factory in Angers, France, to produce AI systems and related components for European AI […]
Cyber espionage operators are using a newly documented Windows backdoor called HazyBeacon to target government networks in Southeast Asia, turning legitimate Amazon Web Services infrastructure into a covert command-and-control channel that can blend into ordinary cloud traffic. The activity, tracked as CL-STA-1020, has been linked to intelligence-gathering operations focused on sensitive state information, including material tied to tariffs, trade disputes and government policy discussions. Security researchers have […]
Abu Dhabi Gaming has signed a strategic partnership with ASPIRE to accelerate AI-led game development, linking the emirate’s interactive entertainment ambitions with advanced research capabilities from one of its key technology institutions. The agreement was formalised during the A2RL Summit at ADNEC Centre Abu Dhabi, where global technology, mobility, autonomy and gaming specialists gathered to examine how artificial intelligence is reshaping industries built around real-time decision-making and […]
Oman India Fertiliser Company is preparing to sell 25 per cent of its share capital through an initial public offering, setting up a July debut on the Muscat Stock Exchange as Oman pushes ahead with a broader programme to widen public ownership of strategic assets.
The offering will comprise existing ordinary shares held by the company’s current shareholders, meaning proceeds from the sale will go to the selling shareholders rather than to OMIFCO. The subscription period is expected to open this month, subject to final regulatory approvals from the Financial Services Authority, with trading targeted for July if market conditions remain supportive.
OMIFCO is 50 per cent owned by Oman state energy group OQ, while Indian Farmers Fertiliser Cooperative Limited and Krishak Bharati Cooperative Limited each hold 25 per cent. The float is expected to give investors access to one of Oman’s largest industrial exporters and a fertiliser producer with strong exposure to global urea and ammonia demand.
The company operates from Sur Industrial City, where its complex includes two ammonia trains and two urea trains. Annual nameplate capacity stands at about 1.15 million tonnes of ammonia and 1.65 million tonnes of urea, making the producer one of the largest fertiliser operators in the Gulf. The business is supported by long-term gas supply arrangements, established marketing relationships and export infrastructure, including a dedicated deep-water berth that connects the plant to overseas markets.
The IPO comes at a sensitive moment for fertiliser supply chains, with Middle East producers drawing stronger investor attention as global prices respond to disruptions in energy and shipping routes. Urea remains OMIFCO’s dominant revenue source, accounting for the bulk of sales, while ammonia provides an additional export stream and supports integrated production at the Sur complex.
OMIFCO generated revenue of $802.3 million in 2025, with an EBITDA margin of 50.6 per cent and a net profit margin of 40 per cent. Revenue for the first quarter of 2026 reached $207.4 million, while EBITDA margin stood at 50.5 per cent and profit margin at 40.4 per cent. The company has said it has maintained a net cash position for several years and has no interest-bearing debt, a profile likely to feature prominently in investor marketing.
The company expects to distribute dividends of about RO71.2 million, equivalent to roughly $185 million, for the 2026 financial year. The payout is planned in two equal instalments, scheduled for September 2026 and April 2027. For the following two financial years, dividend guidance is expected to be linked to either 90 per cent of net profit or a minimum annual compounded increase from the 2026 dividend base, whichever is higher.
The planned sale follows a series of listings and privatisation moves aimed at expanding the depth of Oman’s capital market. OQ Exploration and Production’s 2024 listing was one of the largest offerings in the region that year, while Asyad Shipping also formed part of the state-linked pipeline of public market transactions. OMIFCO’s proposed listing would extend that momentum into industrial manufacturing and food-security-linked exports.
Bank Muscat and Société Générale have been appointed joint global coordinators for the offering, with Bank Muscat also acting as issue manager. Arqaam Capital and United Securities are serving as joint bookrunners. The final structure, allocations and investor eligibility terms will be detailed in the prospectus after approval by the Financial Services Authority.
The offering is expected to include tranches for institutional and retail investors, with participation governed by Oman’s regulations for public joint stock companies. Shares will also be offered to selected qualified investors outside the United States under applicable securities rules, broadening the potential investor base while keeping the formal listing on the Muscat Stock Exchange.
OMIFCO’s position is closely linked to demand from agriculture markets, particularly urea used in crop nutrition. India has remained a major destination for its exports, supported by long-term commercial ties with its cooperative shareholders. From 2023 to 2025, the country accounted for most exported urea volumes and a substantial share of ammonia shipments, reinforcing the company’s role in cross-border fertiliser supply.
Kioxia Holdings has moved within striking distance of Toyota Motor’s market value, underscoring how the artificial intelligence boom is reshaping Japan’s corporate hierarchy and lifting a memory-chip maker that listed in Tokyo less than two years ago into the country’s market elite.
The Tokyo-based maker of NAND flash memory and solid-state drives has become one of the most closely watched stocks on the Tokyo Stock Exchange after a sharp rally tied to demand for data-centre storage, AI servers and high-performance memory systems. Its market capitalisation has climbed into the tens of trillions of yen, placing it near Toyota and behind SoftBank Group in a reshuffled ranking that would have seemed unlikely when Kioxia priced its initial public offering at 1,455 yen a share in December 2024.
The shift marks a wider challenge to the long-standing dominance of Japan’s manufacturing champions. Toyota, the global carmaker that symbolised the strength of Japan Inc. for decades, has been displaced from the top position by SoftBank during the latest AI-led surge, while Kioxia has risen rapidly from a former Toshiba memory unit backed by Bain Capital into a central player in the market’s technology rotation.
Kioxia’s climb reflects investor expectations that memory will remain a bottleneck in AI infrastructure. Generative AI systems require vast amounts of storage and high-speed data movement, pushing demand beyond the older cycle driven mainly by smartphones and personal computers. Data-centre operators, cloud companies and chip designers are competing for components needed to train and run large AI models, giving memory producers stronger pricing power after years of volatility.
The company’s earnings have strengthened sharply. Kioxia has projected operating profit of about 1.3 trillion yen for the April-June quarter, a figure that puts it among the most profitable listed companies in Japan. Its latest annual results showed strong momentum in revenue, margins and cash generation, helping ease earlier concerns about debt and cyclicality. Rating upgrades to investment grade have added to the perception that the balance sheet is improving at a time when investors are rewarding semiconductor exposure.
Kioxia’s origins give its rise broader industrial significance. The company traces its roots to Toshiba’s memory business, which was sold to a Bain-led consortium in 2018 after Toshiba’s financial crisis. The group was renamed Kioxia in 2019, drawing on the Japanese word for memory and the Greek word for value. Its public listing in 2024 valued it below 800 billion yen, after earlier IPO attempts were delayed by weak valuation conditions and pressure in the memory market.
That cautious debut contrasts sharply with its current status. Shares have multiplied as investors reassessed the role of NAND flash in AI systems, especially as large-scale data centres require higher storage density, faster access and more energy-efficient hardware. Kioxia has also been developing advanced BiCS FLASH technology and promoting next-generation SSDs for AI storage infrastructure.
The rally has also lifted questions over valuation risk. Memory chips remain one of the semiconductor industry’s most cyclical segments, with prices exposed to shifts in capital spending, inventory levels and customer demand. A sharp rise in market value leaves Kioxia vulnerable if hyperscaler investment slows, if competitors add capacity faster than expected, or if customers push back against higher pricing.
Competition is intense. Samsung Electronics, SK Hynix, Micron Technology and SanDisk remain key players across memory markets, with SK Hynix holding a dominant position in high-bandwidth memory used in AI accelerators. Kioxia’s strength is more closely tied to NAND flash and SSDs, where demand from AI infrastructure has broadened the market but does not eliminate the risk of oversupply once new capacity comes on stream.
Toyota’s relative decline in the rankings does not point to operational weakness alone. The carmaker remains one of the world’s largest manufacturers by sales and a major profit generator, but investors have been rotating away from traditional industrial leaders towards companies with direct AI exposure. Concerns over electric-vehicle competition, currency movements and the cost of future technologies have weighed on auto valuations, even as Toyota continues to command global scale in hybrid vehicles and supply-chain management.
SoftBank’s ascent has further highlighted the changing market narrative. Its exposure to Arm and AI-related investments has drawn investors seeking Japan-based access to global AI infrastructure. Together, SoftBank and Kioxia now represent a market story centred on chips, data centres, software platforms and computing capacity rather than the export-led industrial model that long defined Japan’s equity market.
Foreign investor flows have amplified the shift. Japan’s equity market has benefited from corporate-governance reforms, stronger capital returns and renewed interest in companies linked to the AI supply chain. The Nikkei 225 has reached record territory, though the rally has been uneven, with gains concentrated in a limited group of technology-linked names while broader market performance has been more mixed.
Kioxia’s next test will be whether it can convert favourable pricing and sold-out capacity into durable earnings. Investors will look for clearer shareholder-return plans, disciplined capital expenditure and evidence that AI storage demand can remain strong beyond the current investment wave. The company’s contemplated US share listing would widen access to global technology investors and could further raise its profile if market conditions remain supportive.
India’s oil demand growth is heading for its weakest annual pace since the pandemic as the Middle East conflict pushes up crude and fuel costs, squeezes refiners and curbs consumption across transport, aviation and industrial sectors.
Consumption growth in the world’s third-largest crude importer is now forecast at about 78,000 barrels a day for 2026, nearly 40 per cent below pre-war expectations. Excluding the Covid-hit year of 2020, that would mark the slowest expansion in a decade for an economy that has otherwise been one of the main pillars of global oil-demand growth.
The downgrade reflects the widening economic impact of the war involving Iran, which began at the end of February and disrupted flows through the Strait of Hormuz, one of the world’s most important oil transit routes. International crude prices have risen sharply from pre-conflict levels, while refined product markets have tightened as Gulf exports of fuels and feedstocks remain constrained.
India’s reliance on imported crude and petroleum products has amplified the pressure. Higher energy prices are feeding into transport costs, refinery margins, aviation fuel expenses and household fuel supply management. A weaker rupee has added to the burden by increasing the local-currency cost of dollar-denominated imports.
State-run refiners have raised some fuel prices modestly, but domestic retail prices remain well below market-reflective levels. Oil ministry estimates indicate that processors have been losing about ₹6 billion a day on sales of diesel, petrol and liquefied petroleum gas. The strain has revived concerns over under-recoveries at state-controlled retailers, even as authorities seek to shield households and small businesses from a sharper fuel-price shock.
Diesel, the largest component of petroleum product consumption, is showing the clearest signs of stress. It powers trucks, tractors, construction equipment and a large portion of industrial activity. Forecasts for diesel-demand growth have been cut heavily, with some estimates suggesting growth may slow to only 4,000 to 5,000 barrels a day, compared with earlier expectations of 50,000 to 60,000 barrels a day.
Transport operators say higher running costs are already hurting freight movement. Rajendra Kapoor, president of the All India Motor and Goods Transport Association, said customers were resisting higher freight charges even as fuel expenses had risen. He estimated that fleet movement had fallen by 15 per cent to 20 per cent, affecting the movement of farm goods, industrial raw materials and retail products.
Petrol demand remains more resilient because passenger mobility has held up better than heavy freight. Even so, growth projections for petrol have been cut by about 40 per cent to around 38,000 barrels a day. Urban commuting, private vehicle use and two-wheeler demand continue to support consumption, but high prices and government appeals for fuel conservation are tempering growth.
Prime Minister Narendra Modi has urged people to save fuel by working from home where possible, using public transport and avoiding non-essential overseas travel. Such measures indicate how the energy shock has moved beyond refinery balance sheets into wider economic management.
Aviation turbine fuel is another area under pressure. Jet fuel costs account for a major share of airline operating expenses, and the loss of Middle East product exports has tightened supplies. Forecasts for jet fuel growth have been halved by some market consultants, while airlines face the twin challenge of higher fuel bills and weaker discretionary travel demand in price-sensitive segments.
Liquefied petroleum gas has also been hit by supply disruptions. April consumption fell to about 2.2 million metric tonnes, down more than 16 per cent from a year earlier, as import flows were affected. Authorities have asked state fuel retailers to build LPG storage capacity equivalent to 30 days of demand, a move aimed at strengthening energy security against further disruptions.
Official petroleum data showed total product consumption at 19.30 million metric tonnes in April, down 4.6 per cent from a year earlier. The contraction followed a record high of 21.75 million tonnes in December 2025, underlining the speed with which the war-related price shock has altered demand conditions.
Global oil-market agencies also disagree over the depth of the slowdown. Some forecasts still expect worldwide demand to rise this year, while others now see a contraction because of weaker refinery runs, reduced petrochemical feedstock availability and lower aviation activity. The sharpest downgrades have been concentrated in Asia, where import-dependent economies are most exposed to disruption in Gulf supply chains.
Typhoon Jangmi lashed the Tokyo metropolitan area on Wednesday, bringing heavy rain, swollen rivers, power cuts and widespread disruption to air and rail services after striking central Japan and moving towards the country’s most densely populated region. The storm, classified as a severe tropical storm as it crossed parts of Japan, pushed flood risks higher across central and eastern prefectures, with authorities warning residents in vulnerable areas […]
Mainland Chinese investors have turned net sellers of Hong Kong-listed equities through Stock Connect, marking a rare reversal in cross-border flows as enthusiasm for onshore artificial intelligence shares draws capital back towards Shanghai and Shenzhen.
The shift reflects a sharp change in investor preference after months of underperformance by Hong Kong equities against mainland peers. Mainland investors sold about HK$3.6 billion of Hong Kong shares through the trading links last month, the first monthly net outflow since June 2023 and one of only a small number of monthly selling episodes since the southbound channel became a key route for mainland money into the city’s market.
The move is striking because southbound buying has been one of the strongest supports for Hong Kong stocks over the past year. Mainland funds poured into high-dividend banks, telecoms groups, energy companies and internet platforms during earlier phases of the rally, helping offset caution among global investors. That support is now weakening as domestic funds chase companies tied to AI infrastructure, chips, optical modules, software and computing power.
Onshore AI shares have delivered a stronger performance than Hong Kong’s technology benchmarks this year. The CSI Artificial Intelligence Index has risen sharply, while the Hang Seng Tech Index has lagged, weighed down by concerns over platform margins, heavy spending on AI models and pressure from subsidy battles in e-commerce and online services. The divergence has encouraged active money managers and retail traders to reassess whether Hong Kong-listed internet giants still offer the most attractive exposure to China’s technology story.
The change in flows also comes as Beijing’s industrial policy continues to favour advanced manufacturing, domestic semiconductors, large language models and high-end computing. Companies linked to AI servers, data centres, optical communications, robotics and chip design have become favoured market proxies for China’s effort to reduce dependence on foreign technology. That policy backdrop has helped support valuations even as questions persist over earnings visibility, capital expenditure demands and competition.
Cambricon Technologies, Zhongji Innolight, Kingsoft Office, iFlytek and other mainland-listed technology names have been among the companies watched closely by investors seeking domestic AI exposure. Hong Kong still hosts major technology groups such as Tencent, Alibaba, Baidu, Meituan and Xiaomi, but the market’s heavyweight structure makes it more exposed to mature platform businesses than to the faster-growing AI hardware and infrastructure supply chain favoured by onshore traders.
Hong Kong’s role as a fundraising centre remains intact despite the outflow. The city has continued to attract listings from technology, healthcare, robotics and semiconductor-related companies, while mainland firms still view it as the most practical offshore venue for raising international capital. Several AI and chip-linked companies are preparing or considering Hong Kong share sales, suggesting the city remains central to China’s capital market architecture even as secondary-market money rotates elsewhere.
The weakness in southbound appetite also reflects broader caution over Hong Kong valuations after a strong earlier advance. Investors who bought the market for dividends and policy support are locking in gains while seeking higher-beta opportunities at home. The shift does not necessarily point to a structural rejection of Hong Kong stocks, but it does show that mainland money is becoming more selective after helping drive earlier momentum.
Regulatory pressure on offshore investment channels may also be influencing behaviour. Authorities have tightened scrutiny of unauthorised cross-border trading accounts and offshore brokerage activity, reinforcing the appeal of regulated domestic routes. While Stock Connect remains an approved mechanism, wider efforts to keep capital within supervised channels have added another layer of sensitivity around outbound allocations.
Market analysts say the key question is whether the AI-led onshore rally can broaden beyond a narrow group of highly valued companies. China’s AI supply chain is benefiting from state support, falling model costs and growing enterprise adoption, but investors face risks from crowded positioning, uneven profitability and rapid technological shifts. Several AI-linked companies still trade more on expectations than on proven earnings, leaving the sector vulnerable to volatility if sentiment turns.
Beijing’s new trade secret rules have taken effect, bringing data, algorithms, computer programs and source code explicitly within the country’s administrative protection system as China moves to curb technology leaks during a sharper contest with the United States over artificial intelligence, advanced computing and strategic know-how.
The Provisions on the Protection of Trade Secrets, issued by the State Administration for Market Regulation under Order No. 126, came into force on 1 June 2026 and replace rules first introduced in 1995. The overhaul gives regulators clearer authority to handle disputes involving digital assets that now sit at the centre of corporate value, from AI model architecture and training datasets to platform recommendation systems, software code and commercially valuable operational data.
The change marks a significant shift in China’s treatment of intangible technology assets. Earlier rules were drafted before cloud computing, AI systems and large-scale data operations became central to business competition. The new framework defines trade secrets as technical or business information that is not publicly known, has commercial value and has been subject to confidentiality measures by the rights holder. Technical information now expressly covers data, algorithms, computer programs and code, while business information can include management, sales, finance, planning, customer and operational data.
The timing gives the regulation wider strategic weight. China and the United States are locked in a prolonged technology rivalry involving semiconductor controls, restrictions on advanced computing hardware, limits on investment in sensitive sectors and scrutiny of cross-border technology transfers. Washington has tightened export controls on high-end chips and chipmaking equipment, while Beijing has expanded its own legal toolkit to protect critical technology, secure data flows and prevent overseas transfer of capabilities it regards as strategically important.
The new rules do not create a separate trade secret law, but provide more detailed administrative guidance under China’s Anti-Unfair Competition Law. They clarify how regulators should assess whether information is secret, whether it has commercial value, what counts as reasonable confidentiality measures and how infringement should be investigated. For companies, the central message is that protection will depend not only on the value of the information, but also on whether internal controls, access limits, confidentiality agreements, digital safeguards and evidence trails are in place.
The provisions also recognise that unsuccessful research can have commercial value. Stage-by-stage technical results, failed experimental data and development paths that save time or cost in future research may qualify for protection if they meet the legal conditions. That is especially relevant for AI labs, pharmaceutical developers, electric vehicle makers, chip design firms and advanced manufacturing groups, where failed trials can reveal important technical boundaries and prevent competitors from repeating expensive mistakes.
Regulators have been given practical enforcement tools, including powers to inspect business premises, question individuals, copy documents, examine electronic records and take action against materials linked to suspected infringement. Penalties can include orders to stop unlawful conduct, confiscation of illegal gains and fines that may reach CNY5 million in serious cases. The framework also covers improper acquisition, disclosure, use or permission to use trade secrets obtained through theft, bribery, fraud, coercion, electronic intrusion or breach of confidentiality obligations.
For multinational companies operating in China, the new rules create a mixed picture. Stronger protection could help firms defend proprietary data, software systems and industrial processes in a market where trade secret disputes have often been difficult to pursue. At the same time, wider protection for data and algorithms may increase compliance complexity, particularly in joint ventures, outsourced research, cloud services, employee mobility, cross-border collaboration and licensing arrangements.
Technology companies are likely to face tougher expectations over documentation. Firms seeking protection will need to show that the information was not easily accessible, carried economic value and was actively protected. Generic claims that an algorithm or dataset is confidential may not be enough. Companies will be expected to classify sensitive assets, restrict access by role, track downloads and transfers, maintain logs, use encryption or watermarking where appropriate, and ensure that employment and partnership contracts define confidentiality obligations with precision.
The rules also sit alongside China’s broader data and security regime, including laws on data security, personal information protection, cybersecurity and export control. That overlap could make enforcement more powerful but also more complicated. A dataset may be a trade secret, a regulated data asset and a cross-border transfer concern at the same time. Businesses handling AI training material, user behaviour data or industrial performance data will need to assess those obligations together rather than treating trade secret protection as a standalone issue.
BrainCo expects a sharp rise in sales of its robotic hands this year as China’s humanoid robotics industry pushes beyond laboratory demonstrations into factory trials, logistics pilots and commercial component sourcing. The Hangzhou-based prosthetics and neurotechnology developer, founded in 2015, is seeing demand broaden from medical bionic hands to dexterous hands designed for humanoid robots. Its latest Revo hand models place the company in a fast-growing supply […]
Johannesburg has become the opening stage for a European Union push to turn a pledged €12 billion investment package for South Africa into bankable projects, with about 200 companies joining the bloc’s first investment roadshow in the country as competition intensifies over critical minerals. The event, hosted at the Johannesburg Stock Exchange on Monday, marked the first major effort to mobilise private capital under the EU-South Africa […]
Parcel-locker group InPost will invest a further €500 million in France by 2030, strengthening its out-of-home delivery network as e-commerce growth and consumer demand for flexible collection points reshape Europe’s parcel market. The commitment adds fresh weight to the expansion strategy of the Poland-based logistics company, which has been building France into one of its most important markets outside its home base. The investment is intended to […]
Coal India Ltd cut coal production in May by 11.6 per cent year-on-year to 56.13 million tonnes, underscoring a shift in the country’s energy market as high inventories, uneven industrial demand and rising non-fossil capacity alter the operating rhythm of the world’s largest coal miner.
The May figure, based on provisional operational data for the month ended 31 May, came against a monthly target of 66.28 million tonnes. Coal offtake, the volume supplied to power utilities and other customers, rose 2.26 per cent to 66.18 million tonnes, showing that dispatches continued to outpace production as the company worked down inventories rather than pushing output at full pace.
The fall marks the second straight month of reduced production after April output dropped 9.7 per cent to 56.1 million tonnes. The pattern points to a deliberate balancing act by Coal India, which remains central to electricity security but is also facing the consequences of heavy stock accumulation at mines and the growing role of solar, wind, hydro and nuclear generation in meeting demand.
Coal India, through its subsidiaries, accounts for about four-fifths of domestic coal output. Its production in the first two months of the 2026-27 financial year stood at 112.19 million tonnes, below the target of 127.85 million tonnes. The company’s annual production target for the year is 815 million tonnes, a demanding goal at a time when the power market is becoming more seasonal and less dependent on continuous coal expansion.
Demand for coal has not collapsed. Peak electricity demand touched a record level of about 270.8 gigawatts in May as a severe heatwave lifted cooling needs across several regions. Coal-fired plants remain the backbone of the grid, generating more than 70 per cent of electricity despite the rapid expansion of non-fossil capacity. Yet the pressure on Coal India is no longer simply to mine more. It is to supply coal to the right locations at the right time while avoiding excessive stock build-up at pitheads.
Inventories have become a key concern. Coal stocks across the system stood at about 168 million tonnes in late May, including 47.6 million tonnes at power plants and 113.5 million tonnes at Coal India mine-heads. The company has said those reserves are enough for 19 days of consumption. Mine-head stocks were about 10 per cent higher than a year earlier, creating operational and financial incentives to moderate production while dispatches catch up.
The May subsidiary-wise data showed a mixed picture. Mahanadi Coalfields produced 14.26 million tonnes, about 20.1 per cent lower than a year earlier, while Northern Coalfields fell 23.69 per cent to 9.47 million tonnes. Bharat Coking Coal declined 25.51 per cent to 2.28 million tonnes. Western Coalfields dropped 8.4 per cent and Eastern Coalfields was down 3.63 per cent. South Eastern Coalfields was the exception, increasing output 4.53 per cent to 14.42 million tonnes, while Central Coalfields edged up 0.44 per cent to 6.2 million tonnes.
The company’s offtake profile was more resilient. Mahanadi Coalfields dispatched 18.34 million tonnes in May, up 5.77 per cent, while Central Coalfields rose 17.45 per cent and Eastern Coalfields gained 6.48 per cent. South Eastern Coalfields increased dispatches by 3.18 per cent. The weaker areas included Bharat Coking Coal, where offtake fell 16.16 per cent, and Northern Coalfields, down 8.44 per cent.
The wider power sector is changing quickly. Non-fossil fuel capacity reached 283.46 gigawatts by the end of March, including 150.26 gigawatts of solar, 56.09 gigawatts of wind, 51.41 gigawatts of large hydro and 8.78 gigawatts of nuclear power. Renewable energy additions in 2025-26 were driven mainly by solar, which has become a significant contributor during daylight peaks. Even so, the grid still leans heavily on coal after sunset and during periods when renewable output weakens.
That split has created a more complex operating environment. Coal India is being asked to ensure reliability during heatwaves, support power plants with low stocks and maintain supplies to non-power consumers, while policymakers are also pushing cleaner energy, storage and transmission upgrades. The result is a coal market where peak demand can be exceptionally strong even as average growth in coal consumption becomes less predictable.
SoftBank Group has overtaken Toyota Motor as Japan’s most valuable company, underlining a sharp shift in investor preference from the country’s traditional manufacturing champions towards businesses seen as central to the global artificial intelligence build-out.
Shares in Masayoshi Son’s technology investment group surged in Tokyo trading, lifting its market value to about ¥47.2 trillion, or roughly $296 billion, ahead of Toyota’s ¥45.7 trillion after the carmaker’s stock fell nearly 5 per cent. The move placed SoftBank at the top of Japan’s corporate valuation table for the first time in more than two decades and added momentum to a Nikkei 225 rally that pushed the index above 67,000.
The change is more than a stock-market milestone. It reflects how the AI boom has reshaped capital allocation in Japan, where investors are assigning higher value to companies with exposure to semiconductors, data centres, power infrastructure and generative AI platforms. Toyota remains one of the world’s largest and most profitable carmakers, but its valuation is now being weighed against a slower earnings outlook, tariff pressure, currency swings and the heavy cost of electrification.
SoftBank’s advance has been driven by a powerful combination of portfolio gains and expectations that its AI-linked holdings could generate fresh liquidity. The group’s exposure to Arm, the British chip-design company it took public in 2023, has become a key pillar of its market value. Arm’s technology is used widely across smartphones, cloud computing and increasingly AI-related chips, giving SoftBank a central position in the semiconductor supply chain.
OpenAI has become the second major driver of investor attention. SoftBank has committed tens of billions of dollars to the ChatGPT developer and is positioning itself as a core financier of AI infrastructure. Expectations that OpenAI could move towards a public listing have intensified interest in SoftBank’s asset base, even as analysts continue to debate how much of the group’s valuation depends on private-market pricing and future monetisation.
The latest surge followed SoftBank’s plan to invest up to €75 billion in AI infrastructure in France, including data centres and power-intensive computing capacity. The first phase is expected to involve about €45 billion of investment to build 3.1 gigawatts of capacity by 2031, with further expansion potentially taking the total to 5 gigawatts. The project places France at the centre of Europe’s push to develop sovereign AI infrastructure, helped by its nuclear-heavy power system and available industrial sites.
SoftBank is also moving to create public-market vehicles around AI infrastructure. SB Energy, its power and data-centre platform, is preparing for a potential US listing and has been linked to a valuation above $50 billion. The company is involved in large-scale power projects designed to support AI workloads, including a 1.2-gigawatt data-centre development in Texas. A separate robotics venture, Roze, is also being prepared for a possible listing, highlighting SoftBank’s attempt to build an ecosystem around energy, construction automation and computing capacity.
Toyota’s fall in ranking does not signal operational weakness. The carmaker reported operating income of ¥3.8 trillion for the financial year ended March 2026, supported by vehicle sales and pricing power despite tariff costs and rising expenses. It remains a global force in hybrid technology, production efficiency and supply-chain management. However, investors have become more cautious about its growth outlook as the auto sector faces higher regulatory costs, slower battery-electric vehicle adoption in some markets, and intensifying competition from China-based manufacturers.
The contrast between SoftBank and Toyota captures a broader reordering of Japan’s equity market. AI-linked names, chip suppliers and infrastructure companies are drawing strong inflows, while parts of the auto sector and older industrial groups face questions over margin durability. Kioxia, the memory-chip maker, has also climbed sharply this year, showing how investor enthusiasm has spread beyond SoftBank into companies tied to storage and high-performance computing.
The rally has strengthened the profile of Son, whose investment record has swung between spectacular gains and painful losses. SoftBank’s Vision Fund suffered heavy write-downs after the collapse in technology valuations in 2021 and 2022, while earlier bets such as WeWork damaged confidence in the group’s risk controls. Its comeback has been powered by a more concentrated AI narrative, but that also leaves the shares vulnerable if expectations around OpenAI, Arm or infrastructure listings are revised lower.
Copper prices advanced in New York and London as traders moved into a decisive month for the US tariff review that could reshape global flows of the metal used across power grids, construction, electronics and defence manufacturing. Benchmark copper on the London Metal Exchange rose 0.4 per cent to $13,687.50 a tonne on Monday morning in Shanghai trading, while the US Comex contract climbed 1 per cent […]