News related to
macro

A new stablecoin backed by the Argentine peso has been launched by the Latin American crypto exchange Ripio, signalling a significant step in the region’s digital finance landscape. The token, named wARS, is available on the Ethereum, Base and World Chain networks and is intended to provide users with 24/7 access to local-currency funds without relying on the US dollar or traditional bank systems.

Ripple effects are already evident across the fintech sector as Ripio seeks to leverage its more than 25 million users throughout Latin America to build cross-border payment rails denominated in local currencies. Ripio’s management says the introduction of wARS is part of a broader strategy to bring real-world assets such as fiat currencies and tokenised debt onto blockchain platforms. The move follows the company’s earlier launch of a tokenised sovereign bond in Argentina.

The economic context makes the launch especially noteworthy. Argentina’s inflation rate fell to around 31.8 % this year, down from close to 292 % in April 2024 under President Javier Milei’s government. The peso remains subject to strict controls and capital restrictions, creating demand for crypto alternatives and dollar-linked stablecoins. A peso-pegged token could serve as an on-chain alternative for Argentines seeking to transact in their local currency while bypassing conventional banking and remittance infrastructure.

Market analysts point to three immediate implications. First, wARS offers a familiar reference point for domestic users who know the peso, rather than US-dollar-backed tokens. Second, by operating on multiple blockchains, it allows integration with decentralised finance applications across ecosystems. Third, the design could appeal to freelancers, exporters and cross-border businesses connecting Argentina with Brazil, Chile and other Latin American economies that currently settle in US dollars or face fragile local-currency rails.

Still, several challenges lie ahead. Liquidity and market acceptance remain uncertain outside major cryptocurrencies, and the value of a peso-pegged token will likely be sensitive to broader macroeconomic policy changes and FX-control shifts. Regulatory clarity is another concern: while stablecoins tied to major currencies have faced scrutiny in major jurisdictions, less attention has been paid to local-currency tokens in emerging markets. One analyst cautions that “regulators worldwide have not fully caught up with stablecoins that reflect non-dollar fiat currencies, so scalability and risk need careful governance.”

Seventeen years after the publication of the nine-page document titled “Bitcoin: A Peer-to-Peer Electronic Cash System,” authored under the pseudonym Satoshi Nakamoto on 31 October 2008, the digital asset known as Bitcoin has evolved from an experimental peer-to-peer payment proposal into a multi-trillion-dollar fixture of global finance.

At its launch, the paper proposed a decentralised network free of financial-institution intermediaries, aiming to avoid double-spending through a proof-of-work mechanism. Over the years the network has grown into a dominant cryptocurrency, and observers say that Bitcoin’s role in financial markets has shifted markedly. A study examining institutional adoption found that Bitcoin’s correlation with major equity indices — once low — rose to as high as 0.87 in 2024, signalling growing integration with mainstream markets.

Institutional interest forms a central pillar of this transformation. Following the approval of spot Bitcoin exchange-traded funds in the United States in January 2024, which drew in more than $50 billion in inflows, traditional asset managers such as BlackRock and Fidelity Investments gained routes for mainstream investors to access Bitcoin. Some corporations have adopted Bitcoin as part of corporate treasury strategy: around 80 companies now hold approximately 3.4 per cent of total Bitcoin supply.

Despite this ascent, some early proponents of Bitcoin’s original vision — that of a decentralised digital cash usable for everyday transactions — argue that the current model leans more toward its status as “digital gold” than as peer-to-peer money. Payment-system advances like the Lightning Network seek to restore that vision, enabling faster and cheaper transactions on-chain. Meanwhile, critics highlight that energy consumption and regulatory uncertainty continue to pose risks to Bitcoin’s wider adoption.

Regulatory momentum also remains uneven. While the United States moves closer to clearer rules through legislation such as the proposed Clarity Act — which analysts estimate has an 80 per cent chance of passing by early 2026 — global approaches vary significantly. Some jurisdictions have embraced crypto frameworks, while others maintain prohibitive stances. The potential for banks and custodial institutions to operate more directly with digital assets is gaining attention.

Technologically, Bitcoin remains foundational. The original protocol, unchanged at its core since its launch, still underpins a thriving ecosystem of wallets, exchanges and blockchain analytics. That continuity has contributed to its brand as the ‘first mover’ in the cryptocurrency space. At the same time, ecosystem participants are attending to scalability challenges, security risks tied to quantum computing and ecosystem fragmentation through forks.

On the macro-economic front, Bitcoin is increasingly viewed as a hedge or alternative asset, though its extreme price volatility continues to limit its suitability for everyday payments for most users. A survey found 63 per cent of Americans did not feel confident investing in or using cryptoassets, and among adults aged 50 or over that figure rose to 71 per cent. At the same time, the asset’s market cap has situationally breached the $2 trillion mark, reflecting its material scale within finance.

The evolution of Bitcoin also reflects a broader shift in financial architecture: decentralised networks and tokenised assets are increasingly challenging traditional models of money, payment and settlement. Analysts argue that the next phase of Bitcoin’s maturation will hinge on regulatory clarity, technological scalability and an enhanced role in everyday commerce, rather than only institutional accumulation.

Net Profit Surges over 25%, Proposed an Interim Dividend of HK 1.0 cent per share Financial Highlights For the six months ended 31 Aug HK$’000 2025 2024 Change Profit before taxation 44,696 35,962 +24.3% Profit for the period attributable to shareholders 38,381 30,535 +25.7% Net profit margin 46.8% 35.1% +11.7 p.p Basic earnings per share (HK cents) 2.0 1.6 +25.0% HONG KONG SAR – Media OutReach Newswire […]

Ethereum’s trajectory is showing signs of strengthening as institutional demand, staking growth and protocol upgrades converge to position the network for a possible lead in the upcoming crypto cycle. The asset has been trading in a holding pattern around the $4,000–$4,300 range while market watchers debate whether this consolidation presages a breakout or a renewed test of support. According to exchange-data and on-chain indicators, Ethereum’s fundamentals are increasingly robust as it faces critical technical levels.

Institutional flows into Ethereum-related products have doubled since early 2025, with fund holdings reaching an estimated 6.5 million ETH and staking totals climbing to a record near 36.1 million. These developments reflect rising confidence in the network’s long-term value proposition as more traditional investors enter the space. On-chain records show that major whale wallets and “smart money” participants are accumulating, while staking reduces circulating supply and enhances scarcity dynamics.

Ethereum’s dominance in the decentralised finance and stable-coin settlement sectors amplifies that structural momentum. The network remains the foundational layer for smart-contract use-cases, layer-2 roll-ups and tokenised assets, lending greater weight to its ecosystem compared with more speculative cryptocurrencies. Developer-activity metrics place Ethereum ahead in creating new builds, deploying upgrades and supporting applications, reinforcing its role as a critical infrastructure asset rather than simply a trading vehicle.

On the technical front, key resistance near $4,250–$4,300 has become a focal point for analysts. A sustained breakout beyond that zone could unlock targets in the $5,000–$6,000 range and potentially much higher over the next year or two. Conversely, failure to clear that barrier could invite a re-test of support zones around $3,900–$4,000, a scenario flagged by bearish analysts. Macro-conditions such as global interest-rate policy, liquidity flows and risk-appetite remain wild cards, keeping short-term momentum fragile even as the long-term case strengthens.

Competition from alternative layer-1 blockchains and regulatory uncertainties remain headwinds. While Ethereum remains the ecosystem leader, other chains are gaining traction with lower fees and faster speeds; the extent to which Ethereum preserves its dominance will depend on its ability to scale and manage cost pressures. Moreover, regulatory scrutiny of crypto assets and staking vehicles may alter the institutional adoption timeline, requiring cautious interpretation of bullish narratives.

Emerging upgrades to the network architecture provide a catalytic backdrop. The so-called “Fusaka” upgrade, scheduled for late 2025, aims to deliver enhancements to sharding and data-availability that should improve throughput and reduce fees. These technical improvements may lower entry barriers for decentralised-applications and stimulate further ecosystem growth, thereby reinforcing Ethereum’s value proposition. At the same time, staking yields continue to incentivise long-term holders and reduce the liquid supply, offering a structural support mechanism for price.

Gold regained momentum as the US dollar’s slide and expectations of a shift in Federal Reserve policy helped lift the metal above the psychologically important $4,000-per-ounce mark. Spot gold rose around 0.7 % to $4,009.39 per ounce, while US gold futures for December delivery edged up to $4,022.10. At the same time, broader factors have introduced both bullish and cautionary signals to the market.

Investor interest is rekindled by the weaker dollar, which makes gold relatively cheaper for buyers holding other currencies, and by widespread anticipation that the Fed will adopt a more dovish stance. The dollar index fell roughly 0.1 % as markets weighed the possibility of rate cuts. At the same time, certain easing in trade-tensions between the US and China has slightly reduced gold’s role as a safe-haven asset. The confluence of these opposing forces has begun to shape a more nuanced outlook for the metal.

Analysts say that the rebound above $4,000 should not be taken as a strong bullish assurance yet. While the technical bounce signals renewed buying interest, momentum must be supported by fundamentals. One market commentator observed that “buyers who were waiting on the sidelines for gold are now being tempted into taking positions at these price levels. Also, we are seeing a bit of softness from the dollar, which is giving gold a reprieve”.

The wider context shows that gold has already surged markedly this year, up more than 50 % in 2025, and reached a record high near $4,381.21 in mid-October. The rally has been fuelled by a combination of geopolitical anxiety, central-bank buying and expectations of monetary easing. But the pull-back seen earlier this week underscores that investor discipline and macro clarity are still required for any sustained rise.

Emerging trends in the market reveal more structural undercurrents. Research from noted finance academics suggests that gold’s role is evolving: it may increasingly function as a high-quality liquid asset, competing with traditional safe-havens and benefiting from de-dollarisation in global reserves. But at the same time, some firms argue the rally may be overstretched: one analysis warned that with gold already up so sharply this year, its next move could be a “mini-bust,” with projections that prices might fall toward $3,500 by 2026 if support from central-bank demand weakens.

Forecasts for 2026 have also shifted. A poll of analysts and traders indicates a median expectation that average gold prices will exceed $4,000 per ounce next year – a milestone in itself – although forecasts vary widely, reflecting both optimism and caution. On the upside, institutions such as Goldman Sachs remain bullish, pointing to potential further gains on the back of monetary accommodation and geopolitical risk. On the downside, if trade tensions ease and inflation moderates, some believe gold could correct.

The interplay between stimulus expectations and dollar dynamics remains crucial. A softer dollar supports gold, but if authorities signal confidence in economic recovery and maintain higher interest rates, gold’s appeal could diminish because it offers no yield. Additionally, the safe-haven narrative is under pressure as expectations of improved US-China relations gain traction, which may lower investors’ impetus to hold gold purely for risk hedging.

Strength in demand from global central banks has supported prices thus far, but market watchers caution that this may face constraints as gold holdings rise and incremental purchases become harder. For now, the up-move above $4,000 may signal a tentative buying opportunity for traders who believe a rate-cut cycle is on the horizon. For longer-term investors though, vigilance remains essential, as valuations are elevated and market dynamics could shift rapidly.

Matein Khalid The supply glut in crude oil, the fragile geopolitics of the Levant, the Gaza wars, the thinnest sovereign credit spreads since the summer of 2006 have not ended the scramble to pick up MENA credit when the issuer is not a serial borrower/distressed credit and the bonds issue reflects improving political/economic fundamentals. The year ago, Oman and Bahrain provided some amazing opportunities for capital gains […]

Dubai-based Emirates Integrated Telecommunications Company PJSC announced that its third-quarter results delivered a 7.9 per cent year-on-year jump in revenues to AED 3.87 billion, underpinned by growth in mobile, fixed and ICT businesses. The company reported an EBITDA of AED 1.85 billion, which equated to a margin of 47.8 per cent, while normalised net profit rose by 25.8 per cent to AED 732 million. Chief Executive Fahad […]

Advertisements

Microsoft has raised the price of its Xbox development kit from US$1,500 to US$2,000—a jump of approximately 33 per cent. Sources familiar with the matter state that the price increase applies globally, covering regions beyond the United States. The move follows earlier price hikes for the Xbox Series X and S consoles and increases to the Xbox Game Pass subscription. Microsoft attributes the change to broad “macroeconomic […]

LAGOS – Fintech company Moniepoint Inc. announced yesterday that it has raised more than US $200 million in a Series C equity financing round aimed at accelerating its expansion across Africa and into diaspora markets. The round was led by British private equity firm Development Partners International through its African Development Partners III fund, with participation from impact-investor LeapFrog Investments, Google Africa Investment Fund, global payments giant […]

The implied volatility of Bitcoin has remained unusually elevated even as the equity-market gauge of fear, the S&P 500 Volatility Index, has receded to its usual levels. Data show Bitcoin’s 30-day implied volatility hovering above 50 % after the October 10 market shake-up, while the VIX slipped back below 20 %. This divergence signals a significant recalibration of risk within crypto markets.

Analysts point to a cluster of structural pressures within the crypto ecosystem that are now being priced in: chief among them are auto-deleveraging mechanisms on exchanges, thinning liquidity depth, and offshore funding stress. According to Wintermute co-founder Yoann Turpin, “Bitcoin volatility was subdued earlier… It has now become clear that new risks … such as ADL were underestimated and are now being fully priced in.” In practice, when an exchange triggers ADL it forces closure of profitable offsetting positions when an insurance fund is depleted—this introduces an additional risk vector not present in the mainstream equity markets. The residual impact of a major liquidation event on October 10–11, estimated at over billion, has sharpened market caution.

Liquidity concerns are compounded by the behaviour of market-makers during the crash. According to a recent study, market makers withdrew roughly million from key order-books within hours of the triggering event, creating a vacuum in bid-ask depth and amplifying price moves. Participants say that while the VIX drop reflects a return of calm to equity markets after the shock, Bitcoin’s elevated IV suggests the market is in a higher-volatility regime rather than merely bouncing back. Liquidity in offshore markets, which heavily influences Bitcoin trading, appears particularly tight: for example, the Hong Kong Interbank Offered Rate has returned to pre-May levels even as the U. S. dollar index has risen, signalling funding stress that tends to feed into crypto volatility.

Another factor cited is the rapid growth of exchange-traded funds and over-the-counter desks absorbing Bitcoin supply, creating a supply-shock risk for derivatives and making hedging more expensive. A report warned of a potential “liquidity crisis” within six months for Bitcoin ETF structures unless infrastructure adapts. Meanwhile, the macro backdrop of easing interest-rates and previously abundant liquidity has given way to tighter conditions, which amplify volatility across leveraged assets.

Institutional interest in hedging Bitcoin risk has surged. Following the liquidation that knocked Bitcoin from about to roughly, investors rushed into options contracts that bet on further price drops—put-buying spiked as a hedge against renewed turbulence. Such demand for protection keeps implied volatility elevated even if spot prices settle. At the same time, the VIX’s retreat suggests equity investors believe the shock has passed; crypto markets apparently disagree.

The divergence is significant because implied volatility represents the market’s expectation of future price swings. A 50 % annualised IV for Bitcoin implies expected one-month moves of roughly; by contrast, a 20 % IV for the S&P 500 implies one-month moves of around. Such a gap underscores the unique risk environment in which crypto operates—where leverage, thin liquidity and exchange-specific infrastructure risk matter significantly. Academic research supports this: a recent study found Bitcoin’s risk-premia vary across volatility regimes, and that downside risk is significantly more priced in than with equities.

Market makers and trading desks are adapting. Some are widening spreads, reducing inventory and limiting exposure during volatile episodes—actions that in effect undermine liquidity further and contribute to the “sticky” implied volatility. One trader said that “no one slept” during the weekend of October 10–11, as the cascade of liquidations forced hedge funds and desks to scramble for cover amid evaporating depth.

Global investment bank Goldman Sachs has secured the richest place in regional mergers and acquisitions activity in the Middle East and North Africa market, advising on 24 deals worth a combined US$104 billion in the first nine months of 2025, according to data from LSEG Deals Intelligence. The firm’s Co-head of Investment Banking for the Middle East & North Africa, Jassim AlSane, said the growth was driven by “national champions … with significant growth objectives” and government-backed strategies.

M&A volumes across the region have picked up substantially, supported by sovereign backing and major consolidation efforts. According to LSEG’s broader MENA investment banking review, M&A activity hit US$66.4 billion in the first quarter alone, illustrating a robust trajectory for the region. The strong performance underscores an increasingly active market for deals even amid global macro-economic headwinds.

Goldman’s dominance emerged as national-champion companies in the Gulf co-led big transactions. These firms often benefit from state support and predefined strategic mandates that accelerate investment decisions. AlSane highlighted that the top-10 deals for the firm in the region were “underpinned by an approved strategy” and “government-backed,” signalling a close alignment between private investment banks and states seeking large-scale diversification.

Key sectors powering the deal flow include energy-transition assets, infrastructure, and digital platforms. Observers note that the MENA region is embracing its role as a growth frontier for capital deployment, leveraging both private and sovereign funds to consolidate industries and build scale quickly. In particular, Saudi Arabia and the United Arab Emirates continue to push forward national frameworks that incentivise large transactions.

Despite the gains, the environment is not without uncertainty. Globally, deal volume has not uniformly increased — while deal value is up, the overall number of transactions in certain markets remains flat or declining. In the MENA context, some deals have faced delays or regulatory hurdles associated with cross‐border scrutiny and the need for state coordination. Critics argue that heavy reliance on government-backed mandates may reduce private-sector initiative and create hurdles in negotiation and valuation.

Goldman’s rise in the region also reflects wider trends in global investment banking. The firm posted a 42 per cent jump in investment-banking fees in the third quarter of 2025, citing advisory revenue jolts of 60 per cent year-on-year. While that data is global rather than specifically MENA-focused, it indicates that investment banking hunger for strategic transactions is rising and Goldman is benefiting. These elevated fee levels are the highest the firm has seen in years and point to a structural shift in deal-making dynamics.

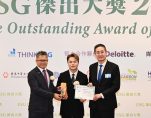
Uunderscoring HGC’s Dedication to Embed ESG into Business Operation HONG KONG SAR – Media OutReach Newswire – 23 October 2025 – HGC Global Communications (“HGC” or the “Group”), a fully-fledged ICT service provider and network operator with extensive global coverage, today announced it has been awarded “The Outstanding Award of ESG 2025”, making it the only telecom operator in Hong Kong recognized this award in 2025. This […]

Japan’s exports rose by 4.2 % in September compared with a year earlier, marking the first increase after five consecutive months of decline. The rebound was driven by a 12.6 % jump in shipments of semiconductors and electronic components as demand across Asia strengthened. Meanwhile shipments to the United States fell by 13.3 %, reflecting persistent tariff pressures.

The official data released by the Ministry of Finance show total export value reached ¥9.41 trillion, while imports rose 3.3 % to ¥9.65 trillion, resulting in a trade deficit of ¥234.6 billion. Economists had expected exports to climb about 4.4 %.

The shift in trade dynamics highlights Japan’s evolving export mix. Analysts attribute the up-turn primarily to regional technology supply-chain demand, particularly from China and other parts of Asia, where exports climbed by around 9.2 %. Shipments to mainland China rose approximately 5.8 %. By contrast, the United States market remained weak, hit by ongoing tariffs and cooling automotive exports.

Japan has been repositioning itself within the global semiconductor industry, capitalising on strengths in chip-making equipment and materials, even as it lags peers in logic-chip fabrication. According to the ASEAN+3 Macroeconomic Research Office, Japanese firms still hold about 30 % of global equipment market share and roughly half of materials supply, although they are behind in advanced logic nodes.

With global demand shifting toward next-generation technologies such as artificial-intelligence servers and 5G infrastructure, Japan’s export engine appears to be realigning. The sharp rise in chip-related shipments suggests that Japanese firms are responding to increased regional tech investment and supply-chain diversification away from the US-China axis.

Japan’s auto industry remains under pressure, however. The drop in exports to the US was exacerbated by a 15 % tariff on Japanese autos imposed in July, which continues to dampen shipments to that key destination. This has left Japan reliant on growth elsewhere. Japan’s new prime minister, Sanae Takaichi, who took office amid this trade shift, sees the export data as an early boost; her government has pledged fiscal stimulus and monetary support to sustain momentum.

The export recovery still carries caveats. While the semiconductor and electronic component sectors are expanding, traditional export categories such as automobiles and machinery have not yet shown comparable strength. Imports rising faster than forecast reflect continuing underlying demand for energy and raw-material inputs, and the trade deficit underscores Japan’s ongoing reliance on external inputs despite the export uptick.

Japan’s export performance could indicate a structural shift rather than a temporary bounce. The country’s strategy to revive its chip industry through initiatives such as the Rapidus consortium and the Japan Advanced Semiconductor Manufacturing venture illustrates a long-term push into advanced-node technologies and supply-chain resilience. These initiatives, supported by government subsidies targeting thousands of billions of yen, aim to re-establish Japan as a key node in advanced electronics manufacturing.

Oil markets have turned once again into a supply-heavy arena as investors take note of swelling global production and a lagging demand backdrop. Prices for Brent crude slipped below $61 a barrel, while U. S. West Texas Intermediate hovered near $57, on signals that stockpiles and tanker-held quantities are climbing. Data from analytics firm Vortexa show that crude and condensate in transit rose to 1.24 billion barrels […]

Greenlogue/AP The 28th edition of the trade-fair and conference platform Ecomondo 2025 will convene from 4 to 7 November at the Rimini Expo Centre, Italy, with a reinforced international agenda that organisers expect will draw more than 1,000 exhibitors and upwards of 100,000 visitors. This year’s event is emphasising several strategic growth areas: climate-tech innovation, digitalisation in resource management, blue economy and Mediterranean-Africa partnerships. The organising body, […]

The world’s largest cryptocurrency, Bitcoin, vaulted above $111,000 after a steep dip earlier this week, triggering sharp gains across major tokens including Ethereum, XRP and Solana. On-chain metrics signalled accumulating momentum while traditional equity markets in Asia registered fresh highs, boosting risk-assets overall.

Bitcoin climbed to around $111,223, representing a gain of approximately 3.7% within 24 hours, after briefly touching a low near $103,602. Other digital assets followed: Ethereum reached roughly $4,062, XRP $2.47 and Solana approximately $193.33, with 24-hour gains of between 3% and 5%.

Analysts highlight several factors underpinning this recovery. On-chain data show the realised value-to-transaction ratio for Bitcoin has declined — a historical marker of heightened accumulation rather than passive holding. A crypto-analytics firm noted that “strong declines in the RVTS have preceded major bull phases, as they indicate that Bitcoin is being used, accumulated, and transferred — not just held.”

Broader market dynamics provided further tailwinds. In Japan, the Nikkei 225 index soared past 49,000 for the first time, advancing the year-to-date gain to 25%. The move followed media reports indicating that the country’s leading opposition party plans to join coalitions which position its fiscal-dove leader for the prime ministership — one with a policy inclination towards low interest rates and expansionary fiscal measures.

Meanwhile, China’s third-quarter gross domestic product growth of 4.8% year-on-year narrowly exceeded forecasts of 4.7%, providing support for risk assets globally.

Beyond macro-signals, institutional behaviours also deserve attention. A leading publicly listed company with large Bitcoin holdings, Strategy, has signalled fresh crypto purchases — adding a layer of institutional demand to the structural thesis.

Within the crypto space, major platforms tied to tokenisation and stable-coin activity are also part of the narrative. Analysts at Galaxy Digital emphasise three structural drivers: increased AI-capex from tokenised assets, accelerating stable-coin infrastructure, and the migration of real-world assets onto blockchain networks. These are seen as propositions that may sustain momentum beyond short-term price moves.

Yet, market participants remain cautious. Liquidity remains thin and residual risks — such as further macro headwinds, regulatory tightening or a reversal in risk appetite — continue to warrant vigilance. As one analyst put it: “The near-term message is caution — respect thinner liquidity, post-crash psychology and a ‘wall of worry’ mood. The medium-term message is resilience.”

Within altcoins, XRP is gaining renewed focus ahead of potential ETF-related developments, while Solana is benefitting from its association with on-chain tokenisation flows. Market-data platform CoinGecko shows that XRP trades at around $2.46, with volume flows increasing as sentiment rebuilds.

Matein Khalid Stock exchange folklore in pre-1929 Jazz Age New York has one priceless insight for me – “you be buying when they are crying, you be selling when they are yelling”. So as I scan the markets, I realized that the mother of all yelling is taking place in the AI arena and its decibel count is loudest where the ignorance about its nuances is the […]

Gold continues its ascent worldwide as festival-driven demand collides with macroeconomic turbulence. Spot prices have broken past $4,300 an ounce, prompting Indian domestic rates to reach ₹1,31,699 per 10 grams and record premiums in key markets. HSBC, recalibrating its outlook, now forecasts average gold at $3,355 for 2025 and $3,950 for 2026, citing sustained safe-haven interest. Buyers in India are shifting patterns: instead of heavy gold jewellery, […]

Over $250 million has been wiped out from leveraged positions across major cryptocurrency markets within the last 60 minutes, according to real-time tracker alerts. The bulk of the liquidations hit long bets, triggering a sharp lash of volatility that rattled traders across exchanges.

Data from multiple crypto-analytics feeds show that Bitcoin and Ethereum bore the brunt of the forced closures, with long positions cascading under mounting downward pressure. The alerts indicate that around $200 million of that total was liquidated in just the preceding 15 minutes. Margin calls and automatic stop-loss triggers have sharply pared back open interest.

Market participants point to a combination of lower-than-expected macro signals and heightened global risk aversion as catalysts for the sudden liquidation wave. Macro equity markets have seen risk assets fall under pressure over the past sessions, prompting a spillover into speculative crypto positions. The added strain from derivatives exposure amplified the move.

Crypto exchange data show that Binance, Bybit and OKX recorded the highest volumes of liquidations, especially in their perpetual futures markets. On Binance alone, over $80 million in long positions may have been forcibly closed, according to traders cross-checking the on-chain and order-book flows. Ethereum perpetuals also registered substantial losses, particularly in mid- and high-leverage tiers.

Analysts observing funding rates and open interest across exchanges have flagged an abrupt deleveraging. The funding rates for many altcoins flipped negative, signalling that the short side was gaining dominance as leverage unwound. Open interest across high-risk tokens dropped by 15 – 20 % in many cases, suppressing liquidity and heightening slippage.

Several algorithmic trading desks and quant funds experienced knock-on effects. As large liquidations pulled prices lower, stop orders cascaded, exacerbating the decline in thin markets. Some trading firms reported losses due to slippage and forced exits—even though positions were hedged—with automated strategies failing to escape the downdraft in time.

A few larger holders, often designated as ‘whales’, appear to have opportunistically repositioned. Some have placed bids closer to now-discounted levels in anticipation of a bounce; others reduced exposure altogether. On-chain indicators suggest increased inflows to stablecoin pools and accumulation in non-spot holdings, hinting at a cautious redeployment rather than wholesale exit.

Institutional interest remains muted amid the turmoil. According to contacts in digital-asset fund management, most institutions were already operating with limited leverage and hedges in place. Few entered new positions during the seizure of volatility, and many paused trades to watch whether support levels would hold.

Multiple posts flooding social media demand accountability—users call for a regulator-led probe, the CEO’s arrest, and deep scrutiny of Binance’s internal systems. The outcry follows recent chaos around synthetic tokens USDe, BNSOL, and wBETH, which lost their pegs on Binance amid massive liquidations. Compensation is flowing, but the narrative now centers on whether the crash was a desperate scramble or a deeply orchestrated exploit.

When Binance announced it would pay $283 million to users affected by depegging and associated liquidations, it framed the move as a goodwill gesture to restore stability. The payout applies to users whose positions used USDe, BNSOL, or wBETH as collateral between 21:36 UTC and 22:16 UTC on October 10. The exchange said compensation covers the difference between liquidation price and market price at 00:00 UTC on October 11, plus fees. It also promised to improve its risk-control systems and change how its indices weigh collateral assets..

These remedial steps, however, have not assuaged skeptics. Analysts at Uphold argued the event was no accident: they see the crash as a coordinated exploit of a vulnerability in Binance’s unified margin system, in which USDe, BNSOL, and wBETH were accepted as collateral. Because the exchange valued collateral based on internal order-book data instead of aggregated external prices, they say the system could be manipulated from within the venue itself. That, they believe, allowed an attacker to locally crash prices and trigger a cascade of liquidations.

One widely cited theory points to timing. Binance announced on October 6 it would update its pricing mechanisms to rely more on external oracles, with the changes scheduled for October 14. The incident happened on October 10—right in the middle of that eight-day window. In effect, critics argue, the exchange had acknowledged the flaw but had not yet implemented the fix, leaving a vulnerability no one should have touched. On-chain data shows USDe dropped to as low as $0.65 on Binance while remaining near parity across other markets, and wBETH and BNSOL showed similar divergence. The fact that only these three tokens—and only on Binance—were massively disrupted raises the specter that this was a targeted strike, not a systemic weak spot.

The theory gains further support from social media researchers. A thread by a user called “ElonTrades” describes how roughly $60–90 million of USDe was dumped on Binance to manipulate its order book, triggering forced liquidations in unified-account positions. That thread also links to outsized short positions opened elsewhere in anticipation of a broad market drop. Combined, the strategy would allow the attacker to profit while setting off mayhem across crypto markets.

Binance has rejected claims of an external exploit. In its public statement, the company argues that extreme market volatility predated the depegs, and that local platform issues amplified rather than initiated the crash. It also suggests some of the price distortions stemmed from interface display glitches—tokens with very small values were rendered as zero on users’ screens—while others reflect execution of long-dormant limit orders. The company contends liquidation volume occurring on its platform was only a fraction of broader market activity.

Even some industry voices have pushed back against blanket condemnation of Binance. One analyst told reporters that attributing the crash entirely to internal failure is premature, and that extreme leverage and macro market turmoil may have interacted with, not originated from, the exchange’s anomalies.

Yet the optics are harsh and the damage is real. The crypto community remains intensely uneasy. Many traders point to how precisely the exploit—or crash—focused on three collateral tokens, how it preceded a planned patch, and how quickly the stains were cleaned up by compensation. To many, the $283 million seems less like accountability than a strategic PR move to calm markets and buy time.

BNB, the exchange’s native token, soared after the compensation announcement, reaching a high near $1,370. That rally suggests some market participants interpreted the payout as a signal that Binance could backstop risks if needed. But it has not quelled deeper anxieties: users are now demanding full transparency about trades, collateral decisions, and the CEO’s role in risk oversight.

Amanda, a margin trader who lost funds in the incident, told crypto forums: “This wasn’t a market tantrum. The order flow was too precise, too surgical. It felt like someone pulled the plug on us.” Other users posted examples of margin calls executed within fractions of seconds after the depeg, with little time or warning to react.

The sequence of events presents too many coincidences: a pricing flaw known and scheduled for repair, large collateral-related token dumps executed mid-window, massive liquidations cascading in an insular system, and a rapid compensation move. Taken together, the evidence aligns with a narrative of design-level risk exploited rather than location-level chaos.

If the worst scenario proves true—that Binance’s unified margin design was manipulable from inside its own infrastructure—the implications ripple far beyond a single crash. Centralized exchanges, hailed for their convenience and liquidity, might now be exposed as fragile ecosystems. Traders could demand stricter oversight, regulators more frequent audits, and entire collateral frameworks could be reassessed.


By K Raveendran Oil prices fell to their lowest level in five months on Tuesday, continuing a slide that has gathered pace over the past several weeks. The benchmark Brent and West Texas Intermediate crude futures have both dipped significantly, erasing much of the year’s earlier gains. In stark contrast, gold has soared to an […]
The article Gold Feeds On Oil’s Misfortune; One Hits The Roof, The Other Down In The Dumps appeared first on Latest India news, analysis and reports on Newspack by India Press Agency).

Traders on the U. S. prediction market Kalshi are assigning a 55 percent chance that Bitcoin will exceed $130,000 by the end of 2025, with probabilities of 34 percent for surpassing $140,000 and 24 percent for topping $150,000. That places the market’s expected annual high at roughly $132,000.

Those figures reflect a steadily intensifying optimism about Bitcoin’s trajectory, drawing attention from institutional and retail participants alike. Kalshi’s “How high will Bitcoin get this year?” market is driving price discovery around extreme outcomes for the cryptocurrency.

That optimism today sits alongside growing institutional flows into related assets. Bitcoin spot ETF issuers have been attracting multi-billion dollar inflows across several jurisdictions; analysts view that as a cornerstone of structural demand, tightening supply in spot markets. At the same time, the derivatives market is registering sharply skewed positioning in favour of upside moves, especially in out-of-the-money call options.

Crypto research platforms note that exchange reserves of Bitcoin are at multi-year lows, meaning a smaller buffer for large sell orders to exert downward pressure. Some large holders are moving coins to cold storage or long-term custody, reducing the circulating float further. That dynamic can magnify even moderate inflows into a pronounced price rise.

Macroeconomic factors are reinforcing these tailwinds. Markets broadly expect the U. S. Federal Reserve to shift toward a less restrictive stance in the months ahead, which would lower the opportunity cost of holding a risk asset like Bitcoin. Inflation pressures, geopolitical uncertainty, and currency devaluation narratives have been pushing capital toward non-sovereign stores of value — a trend some asset allocators perceive as supportive for digital assets.

Kalshi itself has expanded rapidly. In October 2025, the company announced growth into over 140 countries following a $300 million funding round that values it at $5 billion. This capital boost is intended to improve infrastructure, broaden partnerships, and scale its product stack beyond simple yes/no event contracts. The valuation surge underscores confidence in prediction markets as a means of tapping collective foresight.

Kalshi is currently viewed as a leader in the prediction-market space, outpacing rivals like Polymarket. As of mid-October, Kalshi’s valuation exceeds that of Polymarket by a wide margin, though the latter retains star appeal in crypto circles.

BlackRock chief executive Larry Fink asserted that cryptocurrencies carry a role akin to gold in investment portfolios, calling Bitcoin “a decent tool for diversification” while warning that it should not form a major slice of one’s holdings.

Speaking on 60 Minutes on CBS, Fink said: “There is a role for crypto in the same way there is a role for gold … For those looking to diversify, it is not a bad asset, but I don’t believe that it should be a large component of your portfolio.”

Fink’s remarks mark a notable shift from earlier positions. In the past, he dismissed Bitcoin as a facilitator of money laundering, stating that none of his clients expressed interest in crypto. The evolution of his thought underscores how digital assets have moved further into mainstream investment discourse.

His comments come amid rising institutional engagement with digital asset markets, with BlackRock among firms championing the development of spot Bitcoin ETFs. The firm has also begun pushing into tokenization, envisioning the conversion of traditional financial products such as equities, bonds or real estate into digital token formats. Fink described tokenization of all assets as “the next wave of opportunity” over the coming decades.

Analysts view Fink’s balanced tone—acknowledging both potential and restraint—as calibrated for the climate of heightened volatility and regulatory uncertainty in crypto markets. He is signalling openness without forfeiting caution.

Some investors welcomed the endorsement as validation from one of finance’s most influential figures, though sceptics note that Fink’s insistence on limiting crypto to a small portfolio slice reflects enduring reservations.

Crypto proponents point out that Bitcoin’s often low correlation with equities or bonds—and its non-sovereign character—make it attractive as a diversification instrument. BlackRock itself in earlier internal research has characterised Bitcoin as a “unique diversifier,” citing its tendency to behave differently from traditional assets during episodes of macro stress.

Yet the environment remains fraught. Price swings, regulatory fragmentation across jurisdictions, and infrastructure challenges continue to deter widespread adoption. For instance, debates persist around how to regulate digital assets, custody risks, taxation, and classification.

Roughly $706 million in leveraged crypto positions were liquidated over the past 24 hours, with long bets accounting for $456 million and shorts making up more than $249 million, according to Coinglass data. Ethereum led by asset class with $234 million in liquidations, Bitcoin followed with $168 million, and other altcoins totaled about $68 million. Meanwhile, U. S. spot Bitcoin and Ethereum ETFs recorded sharp capital withdrawals of $326 million and $428 million respectively, marking a second straight session of outflows for both.

The wave of forced sell-offs comes amid intensifying volatility across crypto markets, driven by macro uncertainties and amplified leverage. Analysts point to U. S.–China trade tensions and abrupt tariff escalations as triggers that rattled institutional positioning. The ensuing “flight to safety” saw leveraged traders squeezed out, pushing volatility higher.

Ethereum’s dominance in the liquidation mix underscores its exposure to leveraged structures: its liquidations outpaced Bitcoin by roughly 40%. That suggests traders running shorter time horizons or more aggressive leverage in the ETH derivatives market. Some observers interpret this as symptomatic of recent rotations within crypto capital flows, where speculative bets on altcoins become more vulnerable during stressed conditions.

ETF outflows add another layer to the stress narrative. The $326 million pulled from spot Bitcoin ETFs and the $428 million withdrawn from Ethereum ETFs reflect a broader retreat by institutional capital. For Ethereum ETFs, Monday’s $428 million exodus represented the steepest daily outflow in several weeks. Within those redemptions, BlackRock’s ETHA alone led with over $310 million withdrawn.

Those moves reverse inflows seen in prior weeks: Ethereum funds had aggregate positive flows of nearly $488 million in the prior week, while Bitcoin products had also drawn substantial capital. Market analysts caution, however, that the shifts may not signal structural withdrawal from crypto exposure but rather tactical repositioning under duress.

Volatility in derivatives markets has drawn scrutiny to structural stress points. Funding rates, margin requirements, and thin liquidity in some trading venues magnify the impacts of sudden directional moves. Experts suggest that while ETF outflows may exacerbate short-term weakness, sustained pressure will hinge on macro stability.

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA