News related to
business

Nairobi-based electric mobility firm Roam Electric Ltd has begun talks to monetise carbon-offset credits generated by its motorcycles while launching a global crowdfunding campaign to raise working capital. Each machine sold by Roam is designed to offset around three tonnes of CO₂ annually; with about 4,000 units currently in circulation, the company estimates roughly 12,000 tonnes of emissions reduction per year—equivalent to the output of some 2,600 […]

India’s workforce is entering a critical phase as artificial intelligence reshapes job markets and industry demands, with upskilling emerging as a non-negotiable necessity for both individuals and organisations. According to a recent assessment of the Asia-Pacific region, India needs to scale up its skilling efforts rapidly to avoid falling behind in the global AI marathon. A report by Asian Development Bank and Google. org warns that without accessible AI-skilling initiatives, large segments of the workforce risk being left out of the transition.

The country already boasts one of the youngest and fastest-growing workforces in the world, offering a potential advantage in the AI era. Yet the report highlights a mismatch: numerous workers in labour-intensive sectors such as textiles, manufacturing and logistics perform roles with high automation risk — for example data-entry, scheduling and support functions — and these roles are disproportionately held by women and informal workers. With AI-driven automation advancing quickly, these groups could be among the hardest hit unless targeted training interventions are introduced.

Data published by NASSCOM indicates that India’s existing AI talent pool, estimated at around 600,000 today, must expand to more than 1.2 million by 2027 to fill expected demand—implying a shortfall of more than a million skilled professionals. This gap emerges despite the country producing hundreds of thousands of engineering graduates each year. Industry trackers indicate that more than half the workforce in technology services is already undergoing training in AI, machine learning and related domains, yet skills still lag employer expectations.

Business research from Microsoft found that across Indian organisations two-thirds of employees and four-fifths of leaders are now familiar with AI agents. Within the next 12-18 months more than half of these companies will place upskilling at the top of their agenda, and more than half expect AI training to become a core team responsibility within five years. These trends confirm that industry demand is ahead of the skill supply curve.

Beyond technical expertise, new job roles are emerging. Organisations are recruiting for “AI Workflow Designers”, “Software Operators” and multi-agent system builders. The most vulnerable workers are those in roles focused on infrastructure management, manual testing, and basic coding — positions that technology is already beginning to automate. This points to an imperative for current employees to acquire cross-functional, human-centric skills such as critical thinking, adaptability and collaboration with AI.

Educational institutions and vocational training providers are responding. For example, an initiative at Andhra University in partnership with NASSCOM integrates advanced skill modules into non-engineering streams and appoints department-wise coordinators to ensure student readiness. The move reflects recognition that skilling must extend beyond traditional tech fields to arts and sciences, and must address digital literacy gaps.

Nonetheless, major structural obstacles remain. A digital divide persists: only about one in five young adults in some South Asian regions has reliable internet access at home, limiting participation in online skilling programmes. Language barriers and low digital literacy further hamper effective engagement. Informal-sector workers, who often lack formal training and social protections, face a double risk of displacement without clear pathways into higher-value work.

The informal economy accounts for a large share of India’s employment, and workers in this segment are often overlooked in skill-development policies. Analysts warn that unless training programmes are redesigned for accessibility — offering tailored formats for women re-entering the workforce, rural populations and digitally disadvantaged groups — AI adoption may deepen existing inequalities.

Kenya’s banking sector is under pressure as impaired loan ratios hover at elevated levels even though pre-tax profits and capital buffers point to resilience, according to a recent assessment by ratings agency Fitch Ratings. The sector’s net impaired loans to equity stood at around 23 per cent in the first half of this year, reflecting persistent debt servicing challenges. Fitch estimates that the sector-wide ratio of impaired […]

  Papio Consulting recently launched an AI-powered ESG platform. As Steven Jansen, Founder of Papio Consulting, states MENA is one of the fastest-evolving regions for ESG transformation, with a long-term vision where transparent ESG performance becomes a competitive advantage. Governments are increasingly advancing sustainability agendas and innovation, and companies are ready to integrate smart tools. “Our Papio Sustainability Manager helps reduce the time and cost of ESG reporting by up […]

A substantial shift in sentiment around Alphabet Inc. has taken shape following the firm’s elevation to ‘Buy’ from ‘Hold’ by Loop Capital, with the brokerage raising its price target to $320 from $260. The upgrade underscores a decisive move by Wall Street away from doubts about Alphabet’s core search business toward bullish conviction in its AI-driven future. Loop Capital’s managing director, Rob Sanderson, observed that earlier concerns […]

Major online platforms including Cloudflare, Inc., ChatGPT and X experienced widespread accessibility issues after a network disruption at Cloudflare, a critical internet infrastructure provider. Cloudflare’s own status page recorded scheduled maintenance across multiple datacentres and a subsequent investigation into elevated error rates across its services. The disruption caused significant spill-over effects that impacted end-users globally and raised concerns over reliance on centralised networks. Beginning in multiple regions, […]

BEIJING, CHINA – Media OutReach Newswire – 18 November 2025 – On November 12, 2025, the thematic investment promotion event “Synergy Between Beijing and Hong Kong, Connecting the World – Towards a Brighter Future with Chaoyang” was successfully held at the Hong Kong Convention and Exhibition Centre. Jointly hosted by the Chaoyang District People’s Government and the Beijing Investment Promotion Service Center, and organized by the Chaoyang […]

Advertisements

The Ministry of Human Resources and Emiratisation has announced the holiday for the private sector in observance of Eid Al Etihad, aligning with the cabinet’s decision to recognise official public holidays. The holiday will offer employees in the private sector a designated time off to mark the festive occasion. The Eid Al Etihad holiday typically reflects national pride and unity, as it is celebrated across the country, […]

From nostalgic dress-up dolls to designing digital avatars — discover how fashion evolves through imagination 22 November to 2 December at Gate33 Gallery @ AIRSIDE HONG KONG SAR – Media OutReach Newswire – 18 November 2025 – Organised by the Hong Kong Design Centre (HKDC), curated by digital fashion innovator FabriX, and sponsored by the Cultural and Creative Industries Development Agency, ‘Play, Pose & Pixel’ is a […]

Aster DM Healthcare has secured a substantial financial boost of AED 265 million from the Emirates Development Bank, marking a significant step towards expanding its healthcare footprint in Dubai. The funding is designed to support the development of two multi-specialty hospitals, which will be pivotal in enhancing the UAE’s healthcare infrastructure. The facility, with potential for upsizing, underscores the growing demand for advanced healthcare services in the […]

Smart cities have emerged as a transformative vision for the future of urban life, integrating cutting-edge technologies to enhance living standards, boost sustainability, and improve service efficiency. However, as these cities evolve, they face growing concerns regarding cybersecurity. With vast amounts of sensitive data being collected, processed, and transmitted across networks, securing these data exchanges is paramount. The role of modern cryptographic solutions in safeguarding these environments […]

The Middle East’s aviation market is poised for an extraordinary expansion, according to Airbus’s Global Market Forecast 2025. The region, currently experiencing rapid economic growth and a surge in travel demand, is expected to see its in-service fleet more than double over the next two decades. The forecast reveals that the fleet will increase from 1,480 aircraft in 2024 to 3,700 by 2044, driven by both the […]

Michele Faissola, a senior figure at the family office of Qatar’s former emir, has joined a growing list of high-net-worth individuals relocating from the UK, driven by rising taxes on the wealthy. Faissola, who had been a prominent London-based executive for more than a decade, has shifted his primary residence to Italy, according to recent filings. This move comes amid a surge of wealthy individuals seeking more favourable tax regimes, a trend that has accelerated in recent years.

Faissola, a former Deutsche Bank executive, joined the Dilmon family office in 2018. The office manages the vast fortune of Sheikh Hamad bin Khalifa Al Thani, the former emir of Qatar. The decision to relocate marks a significant departure for the 57-year-old, who had long been part of London’s financial elite. His move highlights the growing concerns over the UK’s increasing tax burden on the rich, which has led to a shift in both the financial landscape and the geography of its wealthiest residents.

While Faissola did not immediately respond to requests for comment, his decision reflects a broader trend among ultra-wealthy individuals. They are increasingly looking outside the UK for residence options that offer more favourable tax conditions. The move is not isolated, as numerous other high-profile figures have also sought alternative locations with tax incentives. London, long considered a global financial hub, has seen some of its most affluent residents relocate to places such as Switzerland, Monaco, and, in Faissola’s case, Italy.

The British government has raised taxes on high earners in an effort to address its budget deficit. The increase in income tax, capital gains tax, and other levies has sparked significant debate about the impact on the wealthy. Critics argue that these changes could drive away much-needed capital, potentially harming the country’s financial sector and economy. Supporters of the tax hikes, however, contend that the changes are necessary to balance public finances and ensure social welfare.

The rise in taxes is part of a broader trend in the UK, where the wealthiest citizens are facing higher rates of taxation. The introduction of the so-called “surcharge” on the highest earners’ income and the steady increase in capital gains taxes has left many individuals questioning whether the UK remains an attractive place to live and do business. This has prompted many to seek jurisdictions with lower tax rates or more favourable tax treatment for high-income earners.

For those like Faissola, who manage significant family fortunes, the decision to relocate is not purely financial. The tax environment is a key factor, but considerations around lifestyle, security, and political stability also play a role in these decisions. The growing trend of wealthy individuals leaving the UK has prompted discussions about the potential long-term effects on the country’s attractiveness to global investors and its position as a financial centre.

The trend of high-net-worth individuals moving abroad is also being driven by the increasing mobility of the wealthy. With the advent of digital platforms and remote work, it is easier than ever for executives and business owners to operate across borders. As the global economy becomes more interconnected, the ability to move assets and people efficiently has become a key consideration for the wealthy.

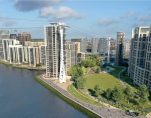
Arada, a UAE-based property developer, has secured an 80% stake in the Thameside West project, located in the Royal Docks area of London. This ambitious waterfront development, with an estimated value of 12 billion dirhams, is set to create a substantial transformation in East London’s housing market.

The project promises to deliver a significant number of new homes, with at least 5,000 residential units planned for construction. In a move designed to prioritise sustainability and quality of life, the development will also allocate half of its site to green spaces, providing a kilometre of active waterfront along the River Thames. This initiative is part of a broader effort to create a modern, eco-conscious urban environment that aligns with London’s sustainability goals.

This acquisition marks Arada’s second major investment in the London residential sector. The company, which has made a name for itself through large-scale projects across the Middle East, made headlines in September with its purchase of Regal, a local developer. Following this acquisition, Arada’s London pipeline has expanded significantly, with the company now managing plans for around 15,000 homes. However, the firm is not stopping there; it has ambitious goals to grow this number to 30,000 units within the next three years.

Arada’s expansion into London reflects broader trends in global real estate, where international investors are increasingly turning to established, high-demand markets like the UK capital. London’s real estate sector continues to attract foreign investment due to its status as a global financial and cultural hub, coupled with its resilient property market. The Thameside West project, in particular, stands out due to its proximity to key transport links and growing commercial sectors around the Royal Docks area.

The development also taps into the trend of mixed-use, community-oriented designs that integrate residential, leisure, and green spaces. The focus on active waterfronts and ample green space addresses the growing demand for sustainable living solutions in urban centres. As cities around the world look to improve quality of life for residents, projects like Thameside West are seen as a forward-thinking model of urban regeneration.

Arada’s entry into the UK market comes at a time when London’s residential sector is undergoing significant changes. As the city continues to recover from the challenges posed by the global pandemic, there is renewed demand for high-quality residential developments, particularly in emerging areas like the Royal Docks. With its large-scale investments, Arada is positioning itself as a key player in reshaping the city’s housing landscape.

The Royal Docks area, where Thameside West is situated, is undergoing a major revitalisation effort, with several high-profile projects aimed at transforming the formerly industrial district into a thriving residential and business hub. The location’s appeal is strengthened by its proximity to London City Airport and the forthcoming Crossrail station at Custom House, which will provide enhanced transport links to Central London and beyond.

Arada’s move to expand its portfolio in London follows a broader trend of Middle Eastern developers seeking high-profile projects in key global cities. The firm’s recent activities indicate a strategic push to diversify its holdings, particularly in international markets where it sees growth potential. In addition to its focus on London, Arada has a number of active developments in the UAE and broader GCC region.

Despite the challenges posed by global economic uncertainties, the demand for high-quality residential units in London remains strong. The city continues to be an attractive proposition for investors, with its longstanding appeal to both domestic and international buyers. This is especially true in East London, where regeneration projects like Thameside West are breathing new life into historically underdeveloped areas.

The launch of the UAE’s Financial Inclusion Strategy has been hailed as a pivotal move in advancing economic access for all, not only within the country but also across the broader Middle East and North Africa region. Ousmane Dione, Vice President for the World Bank’s MENAAP region, underscored the significance of the initiative, framing it as a transformative step that will set a precedent for further developments in financial inclusion.

Speaking at the MENA Leaders’ Summit on Financial Inclusion in Abu Dhabi, Dione expressed his enthusiasm for the UAE’s leadership in this area. He noted that the nation’s decision to launch a comprehensive financial inclusion strategy demonstrates its forward-thinking approach, which aligns with global objectives of promoting equal economic opportunities. The event, organised by the Central Bank of the UAE in collaboration with the Arab Monetary Fund and the World Bank, served as a forum for regional leaders to exchange insights on tackling the challenges that hinder financial access in the MENA region.

The UAE’s initiative seeks to enhance financial services for underserved and unbanked populations, including women, low-income households, and small businesses. This strategy is in line with global efforts to bridge the financial inclusion gap, particularly in emerging economies where a significant proportion of the population remains excluded from formal financial systems.

Dione’s remarks highlighted the importance of creating an inclusive financial ecosystem that enables individuals and businesses, regardless of their background or income level, to access essential financial services. The UAE’s strategy addresses several key areas, including expanding digital payment systems, enhancing financial literacy, and ensuring the accessibility of financial services to remote and underserved communities.

The summit, which brought together leaders from across the MENA region, was a significant step towards addressing the region’s financial inclusion challenges. Many countries in the MENA region still face considerable hurdles in achieving universal financial inclusion, such as limited access to banking infrastructure, low levels of financial literacy, and insufficient regulatory frameworks to support digital finance innovations.

A key topic of discussion at the summit was the role of digital technologies in fostering financial inclusion. Mobile banking, digital wallets, and blockchain-based financial services were identified as critical enablers of inclusive financial systems. These technologies provide a means for individuals who lack access to traditional banking services to participate in the financial ecosystem, empowering them to save, borrow, and invest in their futures.

In his comments, Dione acknowledged that while progress has been made in several MENA countries, significant challenges remain. He emphasised the need for continued collaboration among governments, financial institutions, and technology providers to overcome barriers to financial access. The World Bank has committed to supporting regional efforts to enhance financial inclusion, providing technical expertise and financial resources to initiatives like the UAE’s strategy.

The UAE’s leadership in this area reflects its broader ambitions to position itself as a regional and global leader in financial services. Over the years, the country has invested heavily in developing its financial infrastructure, becoming a hub for banking and fintech innovation. The launch of the Financial Inclusion Strategy is a natural extension of these efforts, aiming to ensure that the benefits of economic growth are more equitably distributed.

One of the notable aspects of the UAE’s strategy is its focus on women’s financial empowerment. Women in the MENA region have historically faced significant barriers to accessing financial services, with factors such as cultural norms and limited financial literacy often preventing them from participating fully in the economy. The UAE’s strategy includes targeted measures to increase women’s participation in the financial system, recognising that empowering women is crucial for driving broader economic growth and development.

The event in Abu Dhabi also underscored the growing importance of regional cooperation in tackling financial inclusion challenges. Leaders from various MENA countries exchanged best practices and discussed ways to harmonise regulatory approaches to digital finance. The World Bank’s involvement in the summit highlights its commitment to supporting the region’s efforts to build more inclusive financial systems.

AccuKnox, a prominent player in Zero Trust Cloud-Native Application Protection Platforms, has entered into a strategic partnership with Frentree, a cybersecurity solutions provider based in South Korea. This collaboration seeks to enhance the security of cloud, container, and AI workloads for businesses across the region.

The integration of AccuKnox’s innovative security technologies with Frentree’s established presence in the South Korean market will enable enterprises to better defend against emerging cyber threats, particularly those targeting cloud-native environments. As businesses increasingly rely on cloud infrastructures and AI-driven workloads, the need for robust security frameworks that can scale and adapt to new vulnerabilities has never been more critical.

AccuKnox’s Zero Trust model, which operates on the principle of verifying every request within a network, regardless of origin, is designed to provide continuous protection against both internal and external threats. By requiring strict authentication and authorisation for all access requests, this security approach eliminates traditional trust models that have proven vulnerable in today’s dynamic digital landscape. This model is particularly effective in safeguarding complex cloud-native environments, where assets may be spread across multiple platforms and locations.

Frentree, with its local expertise and established relationships in South Korea, is poised to play a pivotal role in implementing these advanced security measures within the region. Their deep understanding of local enterprise needs, regulatory frameworks, and operational challenges positions them as an ideal partner for AccuKnox. By leveraging Frentree’s on-the-ground presence, AccuKnox aims to accelerate the adoption of Zero Trust security models, providing South Korean businesses with the tools necessary to meet their cybersecurity requirements in the face of increasing cloud adoption.

The collaboration between the two companies also highlights a broader trend in the cybersecurity industry, where regional partnerships are becoming more prevalent. With cyber threats becoming more sophisticated, businesses are increasingly looking for tailored solutions that not only address global challenges but also account for specific local risks and regulations. By working with a trusted regional partner like Frentree, AccuKnox can ensure that its Zero Trust CNAPP solutions are delivered in a way that meets the unique needs of the South Korean market.

South Korea, which has seen rapid digital transformation in recent years, is a particularly fertile ground for this kind of security innovation. As industries such as finance, telecommunications, and manufacturing embrace cloud computing and AI technologies, the country has become a prime target for cyberattacks. With high-profile breaches making headlines, there is growing pressure on organisations to improve their security postures. The Frentree-AccuKnox partnership is thus timely, as it provides local enterprises with a comprehensive security solution to mitigate these risks.

The partnership is also a response to the rising complexity of cyber threats. The increasing use of cloud-native applications and AI workloads introduces new vulnerabilities, which traditional security models struggle to address. Zero Trust security frameworks, with their focus on micro-segmentation and continuous monitoring, offer a promising solution to these challenges. By focusing on verifying every access attempt rather than trusting devices or users, these systems offer a much higher level of assurance against cyber threats.

Looking ahead, both AccuKnox and Frentree are committed to expanding their reach and impact in the region. This partnership is just the beginning, as the two companies plan to work closely to refine and enhance their offerings based on the specific needs of South Korean enterprises. With the cybersecurity landscape continuing to evolve rapidly, they aim to stay ahead of emerging threats by continuously innovating their security models.

DoorDash, the popular food delivery service, has confirmed that a cyber attack has compromised the personal data of millions of users. The breach, which has sparked significant concern, was the result of a sophisticated social engineering attack targeting the company’s systems. This incident has exposed sensitive user information, including names, email addresses, phone numbers, and in some cases, delivery addresses. The breach reportedly affected users across four […]

Awarded AmCham’s “Quantum Leap in AI & Digital,” 2Stallions digital marketing agency demonstrates how practical AI automations streamline operations and boost productivity for businesses. SINGAPORE – Media OutReach Newswire – 18 November 2025 – At the recent AmCham Singapore Represent Awards 2025, held at Raffles Sentosa and officiated by Guest-of-Honour Indranee Rajah, Second Minister for Finance, 2Stallions Digital Marketing Agency received the “Quantum Leap in AI & […]

Cybersecurity breaches are becoming an increasingly costly issue for Indian enterprises, with nearly a quarter of organisations reporting losses exceeding $1 million over the past three years. This has prompted a sharp uptick in cybersecurity spending, especially in artificial intelligence and cloud security solutions, as businesses aim to protect themselves from sophisticated cyber threats. However, the sector still faces significant challenges, particularly in securing skilled talent to manage the growing complexity of cyber risks.

A recent report by PricewaterhouseCoopers highlights that 23% of Indian businesses have incurred losses of over $1 million due to cyber incidents, underscoring the severity of the issue. These breaches range from data theft and ransomware attacks to more advanced persistent threats targeting critical infrastructure. PwC’s findings suggest that the financial impact on Indian firms is only likely to rise as cybercriminals become more organised and capable, exploiting vulnerabilities in emerging technologies and systems.

The shift towards digital transformation and cloud adoption has undoubtedly exposed businesses to greater risk, with sensitive data being increasingly stored and accessed online. According to PwC, the cloud is now seen as both a critical business enabler and a potential vulnerability. As cloud infrastructures evolve, they are often targeted by cybercriminals seeking to exploit misconfigurations and inadequate security protocols.

In response, Indian businesses are ramping up their cybersecurity investments. Spending on AI-driven security solutions is one of the key focus areas. These technologies allow businesses to proactively identify and neutralise threats in real-time, enabling a faster response to evolving attack patterns. AI is particularly useful for detecting abnormal behaviour and potential risks that traditional security systems might miss. It is also being leveraged for predictive analytics to foresee potential vulnerabilities before they can be exploited by malicious actors.

However, despite the increased allocation of funds towards cybersecurity, the shortage of skilled professionals remains a significant roadblock. The demand for cybersecurity experts far outweighs the supply, with firms struggling to recruit individuals with the necessary expertise in areas such as AI, cloud security, and threat intelligence. The PwC report indicates that many organisations are forced to rely on third-party vendors to manage their cybersecurity needs, further driving up costs.

Experts suggest that to address the talent gap, Indian firms must invest in long-term solutions, such as upskilling existing employees and forging partnerships with educational institutions to nurture the next generation of cybersecurity professionals. The government has also been urged to play a more proactive role by fostering public-private collaborations to enhance the country’s overall cybersecurity ecosystem.

The rise of AI and cloud technologies has, however, brought additional complexities. While these tools can greatly improve security, they also introduce new attack vectors. Cloud environments, if not managed properly, can expose businesses to significant risks, including data breaches and unauthorised access. Moreover, the increased use of AI-driven solutions can create new challenges, such as ensuring the ethical deployment of AI and protecting against adversarial AI attacks.

Despite these hurdles, the Indian cybersecurity landscape is expected to see significant improvements over the coming years. As businesses continue to embrace AI and cloud technologies, security budgets are likely to increase, with a stronger emphasis on automated security measures and real-time threat detection. Additionally, as the global cyber threat landscape evolves, businesses are expected to collaborate more closely with government agencies and international organisations to stay ahead of cybercriminals.

Canonical has taken significant steps to address the needs of security-conscious organisations by introducing new features in both its Kubernetes distribution and Ubuntu Long Term Support offerings. The company’s latest enhancements focus on improving compliance and security, which are crucial for industries requiring stringent safeguards. The addition of FIPS 140-3 validation to Canonical’s Kubernetes distribution marks a major update in the company’s commitment to security. FIPS 140-3 […]

Ebury, a leading financial services provider, has confirmed its role as a key sponsor for the upcoming Scotland London Africa Week in 2025. The event, organised by the Scottish Africa Business Association, aims to foster stronger economic ties between Scotland and the African continent, highlighting the role of trade, investment, and business opportunities in the region.

The partnership with Ebury, renowned for its expertise in global trade finance and foreign exchange solutions, underscores the growing importance of financial services in facilitating cross-border business relationships. The firm’s sponsorship will be centred around the Scotland Africa Networking Reception, which will take place at Dover House in London. This reception serves as a key platform for Scottish businesses, entrepreneurs, and investors to engage with African counterparts and explore new avenues for collaboration.

Scotland London Africa Week is a prominent event that brings together leaders from both public and private sectors to discuss and promote the growing potential of the African market. Through networking sessions, panel discussions, and targeted events, the week-long celebration will provide an opportunity for businesses to forge partnerships, tap into new markets, and discover emerging opportunities within Africa.

Ebury’s involvement with the event highlights the company’s commitment to supporting the economic relationship between Africa and the UK, especially Scotland, which has increasingly sought to expand its international trade network. The company’s expertise in cross-border payments and currency exchange is expected to add valuable insights to the discussions around enhancing financial inclusivity and reducing barriers for businesses in Africa and the UK.

Scotland, with its strong international trade links and vibrant financial services sector, continues to be a key player in fostering relationships with Africa. The country’s emphasis on promoting innovation, sustainable development, and investment in emerging markets aligns well with the strategic goals of the Africa Week.

With the backing of Ebury, the networking reception will focus on addressing critical issues such as trade finance, investment flows, and economic partnerships. The reception will also offer an invaluable networking opportunity for delegates from across the continent and beyond to exchange ideas and explore avenues for collaboration. This sponsorship comes at a time when both the UK and African nations are looking to bolster trade relations and deepen economic cooperation.

Dubai has earned a coveted position as one of the world’s top travel destinations, securing third place in the 2025 Tripadvisor Travelers’ Choice Awards, trailing only London and Bali. The accolade underscores the city’s growing appeal among global travellers, who continue to flock to its iconic landmarks, luxurious shopping experiences, and vibrant cultural offerings. With its blend of modernity and tradition, Dubai has long been a prominent […]

Kubernetes maintainers have confirmed that Ingress NGINX, a cornerstone of many cloud-native infrastructures, will be retired by March 2026. This decision marks a significant change for developers and organisations relying on the popular ingress controller for managing internal and external traffic in Kubernetes clusters. Ingress controllers are essential components in cloud-native environments, facilitating the routing of traffic between external users and Kubernetes-based applications. Ingress NGINX, specifically, has […]

An in‑depth probe by the International Consortium of Investigative Journalists has unveiled a sprawling network of criminal finance powered by cryptocurrencies, highlighting how digital asset platforms, cash‑to‑crypto storefronts and unregulated exchange desks have become central to laundering money for human‑trafficking rings, drug cartels and Russian organised crime groups. The investigation, under the title “The Coin Laundry”, involved more than 100 journalists across 38 news outlets and casts a harsh light on how the crypto‑space has evolved into a parallel shadow financial system.

The core finding of the ICIJ project is that thousands of transactions—ranging from hundreds of millions of dollars—have flowed through crypto platforms that either lacked robust anti‑money‑laundering safeguards or deliberately facilitated anonymity. Some of the biggest cryptocurrency exchanges are shown to have moved hundreds of millions in funds tied to illicit actors even after criminal pleas and enforcement actions. The scale and the reach of the systems uncovered suggest that the digital‑asset industry has matured from niche speculation into a global conduit for organised illicit flows.

The architecture of this criminal system reveals several layers. First, cash‑to‑crypto storefronts operating in places like Dubai, Toronto and other jurisdictions emerge as physical bridges where cash is converted into crypto away from traditional banking rails. These outlets, according to the investigation, serve entities that “have lots of cash they want to offload without using a bank”. Secondly, certain crypto exchanges and wallets have been used to take funds from traffickers, drug networks or Russian criminal gangs, convert them into digital assets, transfer those across borders, then convert back into fiat currencies—often in jurisdictions with weak enforcement. Thirdly, mixers, anonymised cryptocurrencies and opaque wallet‑chains have enabled the origin and destination of funds to be obscured, making law‑enforcement tracking significantly harder.

Criminal networks profiting from these systems include people‑trafficking racks, where victims are moved across borders and payment flows routed via crypto; drug cartels that convert illicit cash into digital tokens to hide funds and move value swiftly; and Russian organised crime groups that make use of sanctions‑evading platforms to transfer funds internationally. The investigation points out how several Russian‑linked exchanges came under scrutiny after moving billions in assets on behalf of sanctioned individuals.

For regulators and law‑enforcement agencies, the ICIJ findings pose a serious challenge. Cryptocurrency was once hailed for its transparency because of blockchain traceability, yet the system has matured into one where anonymisation tools, cross‑jurisdictional flows and cash‑on‑ramps erode that promise. One analysis notes how the boundaryless nature of crypto and cash conversions has “erased national borders” in laundering schemes. The combination of weak regulatory oversight, technological complexity and global jurisdictional gaps means that the crypto sector now offers potentials previously reserved for traditional offshore banking and shell‑company networks.

From a regulatory‑policy perspective the report surfaces key faultlines. Many exchanges either operate in regulatory grey zones or rely on lax “know your customer” checks, enabling high‑risk actors to open accounts and move funds. The ICIJ investigation underscores how crypto to cash workflows are particularly acute in jurisdictions where enforcement is weak or cash‑based storefronts operate with minimal oversight. In India for example, investigators found that 144 cases over three years involved crypto routes used to funnel stolen or illicit cyber‑crime proceeds into global syndicates. That observation underscores how burgeoning crypto markets in emerging economies may be especially vulnerable to exploitation.

Industries beyond crypto feel the fallout. Traditional banking institutions face reputational risk when their clients or connected transactions use crypto intermediaries. Law‑enforcement agencies face mounting costs tracing and investigating these flows when the end‑destination is hidden behind layers of wallets or front businesses. Victims of people‑trafficking or drug networks often find no effective path to recovery, as the digital funds vanish into complex webs. One ICIJ commentary notes that while crypto platforms have profited from these illicit flows, those harmed are “left with little hope of justice”.

The ecosystem enabling this laundering structure demonstrates a careful interplay of legitimate and illegitimate actors. On one side are mainstream crypto exchanges, sometimes guilty of compliance failures or negligent oversight; on the other are fringe services—mixers that convert one token to another to obfuscate origins, anonymous coins such as Monero, and cash‑to‑crypto kiosks possibly operating in jurisdictions with lax enforcement. In the French legal reform context, a law recognising funds passing through anonymisation tools as part of money‑laundering was introduced, acknowledging how tools once fringe are now central to criminal flows.

From the enforcement standpoint the challenge is two‑fold: tracing funds and prosecuting high‑level actors. Blockchain analytics can trace token flows, but when the end‑recipient wallet is converted into cash via shadow exchanges or laundromats, it becomes a near‑impossible task. This is compounded when jurisdictions refuse to cooperate or when the conversion happens in physical storefronts beyond bank controls. One academic note highlights that conventional AML practices struggle to detect “subgraph” laundering patterns that exploit layered wallet behaviour and network effects.

The global regulatory environment currently appears mismatched to the scale of the problem. While policy makers have begun to act—such as the French law targeting anonymisation tools—many jurisdictions lack the statutory frameworks or enforcement resources to address crypto‑laundering at scale. Regulatory gaps are further compounded when major jurisdictions focus only on tokens traded on exchanges rather than on emerging narratives involving cash‑to‑crypto desks, unregulated decentralized platforms or off‑ramp services. One commentator described the flow from cash into crypto as “after tax‑havens, dirty money finds a new home: cryptocurrency”.

From a financial‑crime perspective, the finding that major exchanges still processed illicit funds even after criminal prosecutions signifies systemic weakness. This suggests that bad‑actor networks can rely on deep pockets, jurisdiction shifting and complex intermediaries to keep funds moving. The ICIJ investigation lists two of the world’s largest exchanges moving hundreds of millions in illicit funds after pleading guilty to crimes related to money laundering. These revelations raise questions about whether enough internal controls exist in the high‑volume crypto market and whether enforcement action has produced meaningful change.

The implications for victims of organised crime and for global governance are stark. For people trafficking survivors the money flows support networks that exploit human lives yet vanish into anonymous wallets across jurisdictions, making asset recovery and restitution extremely difficult. For drug‑trafficking networks, the agility and cross‑border speed of crypto conversion process provide large scale advantage. For states dealing with sanctions enforcement, the ability of crypto platforms to host cross‑border flows undermines the effectiveness of sanctions regimes.

While the ICIJ investigation sets out a clearer map of how these systems function, it also signals that the public and private sectors face an urgent need for stronger deterrence. Some proposals include mandatory global standards for exchange KYC/AML, registration of cash‑to‑crypto on‑ramp services, enhanced international cooperation for wallet tracing, seizure frameworks for anonymised funds and real‑time monitoring of conversion windows. A related academic analysis recommends adopting subgraph‑based network detection systems to identify laundering patterns earlier.

Industry players replying to the revelations argue that the bulk of legitimate crypto transactions are untainted and that enhancements to compliance are underway. Exchanges emphasise that transparency is improving with on‑chain traceability and that many illicit flows represent a small fraction of total volume. Some operators point out that regulators themselves are still developing the controls needed for a digital‑asset environment and that over‑regulation risks stifling innovation.

In parallel, a cultural shift is emerging where law‑enforcement bodies increasingly view crypto not just as a speculative market but as a core part of the financial‑crime ecosystem. Tasks once reserved for tracking offshore shell companies or cash couriers now must include tracing smart‑contracts, wallet clusters and token flows across borders. That evolution places a premium on technological capacity, inter‑agency cooperation and jurisdiction‑bridging legal tools.


VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA