News related to
business

Alpha Dhabi Holding has reported a significant surge in its second-quarter net profit for 2025, reaching AED 4.53 billion, marking a 118% increase from AED 2.08 billion during the same period in 2024. This growth reflects the investment conglomerate’s strategic positioning in Abu Dhabi’s dynamic market and its diversified portfolio of high-value assets. Revenue for the quarter also saw an uptick, rising to AED 18.4 billion from […]

Arabian Post Staff -Dubai US-based artificial intelligence company Anaconda, Inc. has raised $150 million in a Series C funding round, marking a significant milestone in its expansion plans. Mubadala Capital, the asset management arm of Abu Dhabi’s Mubadala Investment Company, is among the key investors. This round, led by US software investor Insight Partners, aims to accelerate Anaconda’s growth, focusing on new AI capabilities, strategic acquisitions, and […]

Despite mounting international tensions and growing calls for sanctions, India has confirmed its commitment to continuing oil purchases from Russia. The decision, which has drawn both support and criticism, comes in the face of strong opposition from Western powers, particularly the United States.

India’s robust relationship with Russia, especially in energy sectors, remains central to its strategy to ensure energy security amid global market volatility. While the United States has intensified its warnings against increasing trade with Russia, citing geopolitical risks and the ongoing war in Ukraine, Indian officials assert that the decision aligns with the country’s broader economic interests and long-term energy goals.

The timing of the announcement comes as global oil prices continue to fluctuate, driven by factors ranging from OPEC+ production cuts to the ripple effects of the Russia-Ukraine conflict. With Russia now facing significant sanctions from the West, including oil price caps and restrictions on exports, India has emerged as one of the largest buyers of Russian crude oil, navigating complex international pressures while keeping its energy needs in focus.

India’s oil imports from Russia soared in the wake of the war in Ukraine, particularly after Western nations moved to isolate Moscow from the global market. The country, which historically sourced much of its oil from the Middle East, found Russian oil a lucrative alternative as Western sanctions created discounts, allowing India to tap into a relatively cheap energy supply.

Russia, in turn, welcomed the partnership, as it opened new markets and ensured continued demand for its oil. According to official sources, Russia’s increased sales to India, and other non-Western nations, helped offset some of the lost revenue due to sanctions.

India’s government, however, has been careful to position its stance within a framework of neutrality. Public statements highlight that the nation’s energy decisions are based on its own national interest, focusing primarily on economic stability and the welfare of its people. Officials have also pointed out that India is among the world’s most energy-hungry nations and needs to secure a steady and affordable supply of oil to support its growing population and economic expansion.

Internationally, this trade has sparked debates over the moral and strategic implications of engaging with Russia. Critics argue that by maintaining ties with Russia, India risks undermining global efforts to isolate Moscow, particularly as Western governments seek to enforce stricter sanctions. They point out the tensions between India’s non-alignment policy and its deepening economic relationship with a nation under international scrutiny.

On the other hand, some argue that India’s approach reflects a pragmatic understanding of its own strategic priorities, particularly the need to balance international relationships with domestic requirements. With rising fuel costs and inflation becoming pressing issues for many nations, securing affordable energy resources has become a matter of national security.

India’s oil trade with Russia, however, is not without its challenges. Western nations have long pressured India to reduce its dependence on Russian energy. The Biden administration, particularly, has warned that India’s continued imports could strain relations, especially as the US seeks to maintain solidarity with its European allies in pressuring Russia. Washington’s position on the matter is clear: nations that continue to do business with Russia will face consequences, with potential impacts on trade and geopolitical ties.

Yet, India’s economic and geopolitical imperatives make it unlikely to back down. As part of the BRICS group, which also includes Brazil, Russia, China, and South Africa, India has voiced its commitment to a multipolar world order where nations can pursue their own economic paths, free from external coercion. India has also consistently argued for the need for dialogue and peaceful resolution in the Russia-Ukraine conflict, advocating for diplomacy over military escalation.

The ongoing conflict has undeniably reshaped global energy dynamics, forcing countries to reassess their energy strategies and alignments. While India’s stance has garnered significant attention, its broader approach is seen as part of an evolving foreign policy that seeks to advance national interests without being swayed by external pressures.


SHANGHAI, CHINA – Media OutReach Newswire – 1 August 2025 – InMobi, a global leader in mobile advertising and AI-powered monetization, is taking center stage at ChinaJoy 2025, highlighting its unparalleled growth and unwavering commitment to the Chinese developer ecosystem. With over 80% penetration among China’s top 100 gaming publishers and near-complete publisher retention InMobi has acheived a two-fold increase in revenue for Chinese partners between H1 […]

e& has reported an impressive net profit of AED 3.5 billion for the second quarter of 2025, up 9.7 per cent year‑on‑year, driven by a substantial rise in its global subscriber base. The company’s performance outstripped the average analyst forecast of AED 2.84 billion, underlining robust execution in a competitive market. Consolidated revenue for Q2 rose 28.1 per cent to AED 18.0 billion, while earnings before interest, tax, depreciation and amortisation increased by approximately 22.2 per […]

HONG KONG SAR – Media OutReach Newswire – 1 August 2025 – Cushman & Wakefield, a leading global real estate services firm, today released its Life Sciences on the Chinese Mainland – Vital signs: Diagnosing trends in the life sciences real estate market on the Chinese mainland report. It is based on in-depth interview surveys we conducted on professionals active in the life sciences sector on the […]

HONG KONG SAR – Media OutReach Newswire – 1 August 2025 – ShopBack, Asia’s foremost cashback platform, proudly announces its official entry into the Macau market, introducing a sophisticated yet intuitive solution for savvy shoppers to unlock greater value with every transaction. This strategic expansion signifies ShopBack’s commitment to bringing its signature savings-driven shopping experience to a new community of users. ShopBack officially launches in Macau. New […]

Advertisements
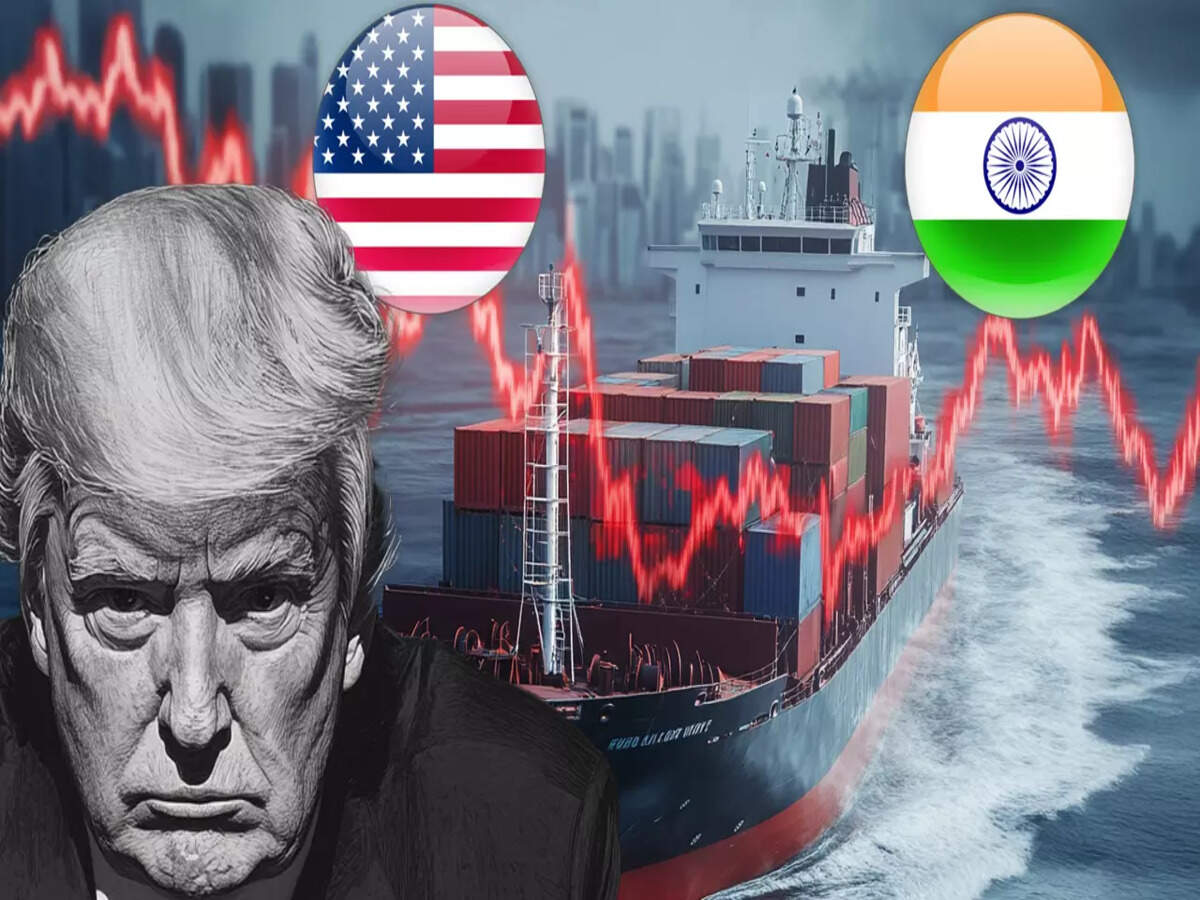
By Dr. Nilanjan Banik Before the August 1 deadline, the U.S. President Donald Trump decided to impose a 25% tariff on Indian exports. He also talked about an additional penalty on Indian exports, which could go up to100% as a surcharge, targeting countries that continue trading oil with Russia. Trump seems to care less about […]

HEIDELBERG moves into defense industry VINCORION Advanced Systems GmbH specializes in power systems for safety-critical applications HEIDELBERG impresses with high vertical range of manufacture and industrialization expertise System partnership with VINCORION marks start of strategic collaboration HEIDELBERG, GERMANY – Newsaktuell – 29 July 2025 – Heidelberger Druckmaschinen AG (HEIDELBERG) is positioning itself in the defense sector with its first concrete project and is entering into a strategic […]

The UAE India Business Council has reaffirmed its collaboration with Expand North Star, marking a significant milestone in fostering cross-border innovation and entrepreneurship. This renewed partnership, now in its second consecutive year, highlights the UAE’s ongoing commitment to positioning itself as a global leader in the startup ecosystem.

Expand North Star, the world’s largest event dedicated to startups and investors, serves as a critical platform for innovation, providing entrepreneurs and investors with opportunities to forge strategic partnerships and explore new ventures. The event, which has grown significantly since its inception, attracts top-tier startups, venture capitalists, and industry leaders from around the globe. Through this renewed alliance, the UIBC-UC aims to amplify the UAE’s role as a hub for high-growth startups, particularly those looking to expand into the MENA region.

The UIBC-UC, a prominent organisation that promotes business ties between the UAE and India, has become instrumental in strengthening the bilateral relations between the two countries, especially in the realm of entrepreneurship and innovation. By partnering with Expand North Star, the council seeks to enhance access to resources, networks, and investment opportunities for startups and entrepreneurs from both nations.

The UAE has been at the forefront of creating a conducive environment for startups, with government-backed initiatives and policies designed to support innovation. Initiatives such as the Dubai Future Foundation, the Mohammed bin Rashid Innovation Fund, and various free zones dedicated to tech startups have positioned the Emirates as an attractive destination for entrepreneurs. The country’s emphasis on digital transformation, coupled with its strategic location between Europe, Africa, and Asia, provides an ideal platform for businesses to scale internationally.

For India, which boasts one of the world’s largest startup ecosystems, the partnership with Expand North Star offers immense potential for collaboration. Indian entrepreneurs, especially those in tech and fintech, have been increasingly looking towards international markets, and the UAE presents a strong opportunity due to its thriving business climate and connectivity. The renewal of this partnership with Expand North Star will undoubtedly encourage more Indian startups to engage with the UAE market and beyond.

The annual event itself is a significant gathering of key players from the global startup and venture capital scenes. This year’s edition is expected to feature prominent speakers, thought leaders, and investors, all aiming to inspire innovation and growth. Attendees will have the chance to network, share ideas, and discuss investment opportunities in sectors such as fintech, healthtech, and green energy – industries that have been gaining momentum in both the UAE and India.

For the UAE, the collaboration with Expand North Star is also part of its broader economic diversification strategy, which seeks to reduce dependence on traditional industries such as oil and gas. By fostering a dynamic and diverse entrepreneurial landscape, the UAE aims to build a sustainable economy driven by innovation. The UAE has seen substantial growth in its startup ecosystem, with a surge in venture capital investments and the launch of several unicorns in recent years. The nation’s commitment to fostering a vibrant startup environment has been instrumental in attracting foreign investors and top-tier talent from around the world.

At the same time, India’s startups are increasingly gaining recognition on the global stage, with many successful exits, IPOs, and growing international footprints. The country’s growing focus on entrepreneurship, combined with a large and diverse consumer base, makes it an ideal partner for the UAE in terms of business and innovation. The collaboration between the UAE and India, therefore, holds significant promise for further enhancing their economic ties and enabling knowledge exchange between the two nations.

The UAE Cybersecurity Council has entered into a significant partnership with Rilian Technologies, aiming to enhance the security of the nation’s critical infrastructure. This collaboration, established in conjunction with CPX Holding, will integrate state-of-the-art technology solutions, both from local and international partners, to safeguard the country’s vital digital and physical assets. This strategic move reflects the UAE’s commitment to fortifying its cybersecurity framework in an era of […]

Casablanca, Morocco— Al Tamimi & Company, the leading full-service legal firm in the Middle East, is pleased to announce the addition of Omar Zizi as Partner in Casablanca, marking a significant step in the firm’s renewed presence in Morocco. This strategic combination reflects the firm’s ongoing commitment to delivering top-tier legal services across North Africa. Omar’s appointment, along with his team, enhances Al Tamimi & Company’s regional […]

The United States has introduced new visa restrictions for citizens of 31 African countries, a move that directly impacts nations such as Nigeria, Ghana, and Gambia. This policy revision limits non-immigrant visas to single-entry permits, significantly altering the travel dynamics for individuals from these countries. The policy, announced by the U. S. State Department, aims to curb perceived abuse of the American visa system while reinforcing the […]

A deadly shooting at the Grand Sierra Resort in Reno, Nevada, on Monday left three people dead and three others wounded, prompting an immediate law enforcement response. The attack, which took place inside the popular casino, occurred around midday, sending shockwaves through the community. Authorities quickly responded to the scene, with Reno Police Chief Kathryn Nance confirming the fatalities and injuries. The victims’ identities have not been […]

South Africa’s trade proposal to the United States remains unaddressed with only four days left before a critical deadline. The proposal, submitted last month, aims to prevent the imposition of steep tariffs on South African goods, which could significantly affect the nation’s economy. As the deadline draws near, the lack of response from Washington has raised concerns among policymakers in Pretoria about the potential impact on exports […]

Noatum Maritime, part of AD Ports Group’s Maritime & Shipping Cluster, has officially opened its first office in Shanghai, marking a significant milestone in the company’s global expansion strategy. The new office will strengthen Noatum Maritime Services’ capabilities in one of the world’s largest trade and logistics hubs, enabling the company to offer comprehensive agency and maritime services to a growing client base in the region. Shanghai’s […]

Greenlogue/AP The Future Investment Initiative Institute, in collaboration with Saudi oil giant Aramco and global consultancy firm Arthur D. Little, has released a comprehensive white paper focused on leveraging artificial intelligence to revolutionise the voluntary carbon market. The paper, titled “AI-Enabled Carbon Markets: Identifying AI Solutions for the Voluntary Carbon Industry,” explores the vital role AI could play in improving transparency, accuracy, and efficiency within the sector, […]

Gold retailer Joyalukkas has secured a significant financing deal with Emirates NBD, confirming a revolving credit facility of 500 million UAE dirhams. The facility will aid Joyalukkas in accelerating its expansion strategy across key international markets, which include the GCC, UK, US, Canada, and Australia. The partnership between Joyalukkas and Emirates NBD is designed to support the retailer’s ambitions by ensuring smooth operational liquidity, particularly during high-demand […]

SINGAPORE – Media OutReach Newswire – 30 July 2025 – Apical has successfully implemented a robust management system to ensure full compliance with the European Union’s Deforestation Regulation (EUDR), which is set to take effect in December 2025. The company’s system assures a traceable, sustainable and deforestation-free supply chain, aligning with the stringent requirements of the regulation. In preparation for the regulation’s full implementation, Apical successfully completed […]

The Central Bank of the UAE has taken decisive action by suspending the motor insurance operations of a foreign insurer’s local branch. This decision, made under Articles and of Federal Decree Law No. of 2023, is aimed at enforcing compliance with regulatory standards in the UAE’s insurance sector.

The suspension stems from the insurer’s failure to meet the solvency and guarantee requirements stipulated by the UAE’s regulations, a breach that has significant implications for the company’s operations within the country. The CBUAE confirmed that while the insurer’s ability to conduct new business has been halted, it remains liable for all existing insurance contracts and their associated rights and obligations.

The UAE’s regulatory framework for insurance companies, introduced under Federal Decree Law No., is designed to ensure financial stability, consumer protection, and sector transparency. By enforcing stringent solvency and guarantee conditions, the CBUAE aims to maintain the integrity of the local insurance market and safeguard the broader financial ecosystem.

The suspended insurer, a foreign entity operating within the UAE, has been under scrutiny for some time due to concerns about its financial solvency. This regulatory action highlights the central bank’s commitment to enforcing the highest standards of compliance in line with national financial stability goals.

The UAE insurance market, which is one of the most developed in the Gulf region, has seen increased oversight from the CBUAE as part of a broader effort to ensure that insurers adhere to strict regulatory standards. This includes robust checks on financial reserves, consumer protection protocols, and transparent business practices. The CBUAE’s regulatory framework is designed to protect both policyholders and the financial system by ensuring that insurance companies have the necessary capital and guarantees to meet their obligations.

While the suspension affects the foreign insurer’s ability to offer new motor insurance policies, the regulator’s actions ensure that the firm will continue to uphold its responsibilities to policyholders who have existing contracts. This decision underscores the CBUAE’s commitment to protecting the rights of consumers and ensuring the financial health of the insurance sector.

The UAE’s insurance industry has been growing steadily over the past decade, with both domestic and international players seeking to capitalise on the expanding market. As a result, the CBUAE has increasingly focused on ensuring that insurers maintain financial solvency and provide adequate coverage to their customers. The central bank’s intervention in this case is part of a broader regulatory strategy to reinforce these standards across the sector.

The foreign insurer affected by this suspension has not made any public statement regarding the situation, and it is unclear how the suspension will impact its broader operations in the UAE. However, analysts suggest that the company may face significant challenges in regaining its ability to operate in the motor insurance market, given the stringent solvency and guarantee requirements that led to the suspension.

The suspension also highlights the growing regulatory scrutiny within the UAE’s financial sectors, where the central bank is increasingly taking proactive measures to ensure that companies adhere to the highest standards. The UAE government has placed a high priority on maintaining a stable financial ecosystem, with regulations designed to support transparency, consumer protection, and overall market stability.

Looking ahead, it is likely that the CBUAE will continue to monitor the financial health of all insurers operating in the country, ensuring that they meet the required solvency standards and operate in line with the national financial framework. The central bank has indicated that it will not hesitate to take similar actions if other companies fail to comply with the law.

French telecommunications provider Orange has confirmed that it was targeted in a significant cyberattack on July 25, which breached one of its critical internal systems. The attack, which has caused considerable disruption to both business and consumer services, appears to be primarily focused on the company’s operations in France. Orange’s response to the incident has been swift, with the company prioritising efforts to contain the breach. According […]

The Dubai Chamber of Digital Economy has introduced The Entrepreneur’s AI Playbook, a strategic guide designed to equip businesses with essential tools to leverage artificial intelligence for growth and innovation. This new initiative is set to support entrepreneurs in integrating AI technologies into their operations and improve overall business performance.

The playbook offers a comprehensive approach to understanding and implementing AI in various sectors, including retail, finance, logistics, and manufacturing. It features step-by-step instructions on how to start using AI, from adopting the right technologies to ensuring scalability. By emphasising AI’s transformative potential, the Dubai Chamber aims to accelerate the digital economy and position the UAE as a global leader in tech-driven entrepreneurship.

Dubai has been at the forefront of the digital transformation in the Middle East, and the launch of this playbook aligns with the Chamber’s vision to create a robust ecosystem for technology adoption across businesses. The playbook is intended to help both established companies and startups identify the most suitable AI tools to streamline their processes, enhance customer experiences, and drive profitability.

The timing of this release comes as AI continues to disrupt industries worldwide, creating both challenges and opportunities for business owners. AI’s ability to automate routine tasks, enhance decision-making, and personalise services makes it an attractive option for companies looking to stay competitive in a rapidly evolving market. However, despite the benefits, many entrepreneurs still face significant barriers to AI adoption, including a lack of understanding, high implementation costs, and concerns about data privacy.

The playbook addresses these challenges by providing clear, actionable insights that guide users on how to navigate these hurdles. It covers various AI applications, including machine learning, natural language processing, and automation tools, providing practical case studies to demonstrate their effectiveness in real-world business scenarios. The playbook also provides resources for entrepreneurs to upskill their workforce, ensuring that companies can build internal capabilities to manage AI integration seamlessly.

One of the key features of the playbook is its emphasis on ethical AI use. As AI systems become more advanced, ethical considerations around data privacy, bias, and transparency are gaining importance. The playbook includes guidelines on how entrepreneurs can ensure their use of AI remains ethical, highlighting the need for responsible data handling practices and fairness in AI-driven decisions.

Experts believe the playbook could significantly improve the UAE’s competitive edge in the global digital economy. By enabling entrepreneurs to harness the power of AI effectively, the initiative could drive innovation across multiple sectors and attract international investments. The playbook also represents the Dubai Chamber’s commitment to creating a future-ready business environment that fosters innovation and digital growth.

The release of The Entrepreneur’s AI Playbook is a part of a broader initiative by the Dubai Chamber to cultivate a thriving digital economy. The Chamber has been actively working to expand the reach of AI and other emerging technologies, offering various training programs, workshops, and collaborations with industry leaders to further the development of digital capabilities among businesses in the UAE.

Entrepreneurs and business owners in Dubai have welcomed the introduction of the playbook, with many highlighting its practical approach to AI implementation. For small and medium-sized enterprises, the playbook offers a valuable resource to overcome the complexity of AI adoption. Entrepreneurs can now explore how AI can be a game-changer in driving efficiency and customer satisfaction without the need for massive upfront investments in technology infrastructure.

MoneyGram, a global leader in digital payments, has announced the resumption of its money transfer services through a newly reinvigorated partnership with Bank AlJazira, one of Saudi Arabia’s prominent banking institutions. This move marks a significant step in advancing the Kingdom’s financial landscape, offering seamless physical and digital cross-border money movement solutions across the country.

The collaboration will allow MoneyGram to leverage Bank AlJazira’s expansive network of physical locations, ensuring that customers in Saudi Arabia can send and receive funds swiftly and securely. It also highlights the growing importance of digital channels in a nation increasingly shifting toward a more digitally integrated economy. The resumption of these services comes at a crucial time, with Saudi Arabia’s Vision 2030 blueprint pushing for greater financial inclusion and a more robust digital ecosystem.

MoneyGram has long been a key player in the cross-border payments industry, with its services spanning more than 200 countries and territories. In Saudi Arabia, the company is now positioned to meet the demands of an expanding customer base that increasingly seeks more accessible, secure, and instantaneous ways to transfer funds internationally.

The partnership with Bank AlJazira, a major player in Saudi’s banking sector, offers a wide-reaching solution for those in the Kingdom who rely on international money transfers for both personal and business purposes. Saudi Arabia has long been one of the largest remittance markets globally, with millions of people relying on money transfer services to send funds to family members overseas.

Saudi Arabia’s vision to become a global financial hub in the region has paved the way for international financial institutions to enter the market, forming partnerships to enhance the ease of conducting international transactions. The latest collaboration between MoneyGram and Bank AlJazira exemplifies this trend, aligning with the Kingdom’s ongoing push to modernise financial infrastructure, streamline cross-border payments, and ensure broader access to digital services.

The financial ecosystem in Saudi Arabia is rapidly evolving. The country’s push for digital transformation is supported by extensive government initiatives, including the Saudi Payments Company and the Financial Sector Development Programme. These initiatives aim to facilitate a more secure, transparent, and inclusive financial landscape. As part of this ongoing transformation, the re-establishment of MoneyGram’s services through a leading bank like AlJazira offers not only more efficient payment processing but also greater accessibility to the broader public.

MoneyGram’s digital capabilities will complement Bank AlJazira’s offerings, ensuring that both physical and digital touchpoints are well-integrated for consumers who demand flexibility in their money transfers. This move also benefits both businesses and individuals, particularly those who may prefer using mobile apps or websites to send money to and from international locations.

The recent resumption of services takes place amidst growing competition in the cross-border payment space. With numerous global players, including Western Union, PayPal, and emerging fintech startups, expanding their presence in Saudi Arabia, MoneyGram’s ability to leverage a strong local partnership enhances its positioning in the market. The company’s collaboration with Bank AlJazira provides it with an opportunity to tap into a network of customers who value both security and convenience.

Bank AlJazira, with its strong reputation in the Kingdom, offers a well-established platform that can seamlessly integrate with MoneyGram’s international remittance network. This partnership will allow consumers and businesses alike to experience an enhanced service offering, particularly in terms of speed and ease of access to funds. With a robust infrastructure already in place, this new initiative seeks to further enhance the efficiency of cross-border payments for people within and outside Saudi Arabia.

With Saudi Arabia focusing on economic diversification and growing international trade partnerships, the enhanced digital and physical money transfer services come at an opportune moment. The Kingdom’s ambitious Vision 2030 plan, which includes bolstering the digital economy and expanding financial services, presents a dynamic backdrop for collaborations like this. By tapping into the burgeoning digital economy, MoneyGram and Bank AlJazira are aligning themselves with the country’s long-term goals.

Greenlogue/AP RIYADH: Strategic adoption of artificial intelligence and climate resilience measures could contribute an additional $232 billion to the Middle East’s economy by 2035, according to a report by PwC. The professional services firm highlights that AI-driven productivity improvements, coupled with focused environmental strategies, are expected to significantly boost the region’s GDP, taking it to an estimated $4.68 trillion by 2035, compared to the current figure of […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA