News related to
China

Suhail bin Mohammed Al Mazrouei, Minister of Energy and Infrastructure, reaffirmed the UAE’s full backing for OPEC+ mechanisms, underlining the nation’s commitment to sustaining equilibrium in global oil markets through capacity expansion and coordinated policy.

At the 9th OPEC International Seminar in Vienna on 9 July, Al Mazrouei praised OPEC+ for its collective decision‑making model, which he said ensures production responds to actual market demand rather than price speculation. He noted that the UAE’s strategic investments in expanding production capacity reflect a readiness to release additional oil when consumption trends warrant, providing a stabilising buffer to global supply. The minister highlighted that this expansion aligns with prudent leadership foresight aimed at reinforcing market resilience.

He emphasised that there has been no substantial rise in inventories despite several months of gradual production increases. “Even with the increases…we haven’t seen a major buildup in inventories, which means the market needed those barrels,” he stated. This observation supports broader OPEC+ data showing that successive monthly output increments have been absorbed by demand, a trend that the UAE believes underlines the rationality behind its expanded quota.

Since April, OPEC+ has reversed approximately 2.17 million barrels per day of voluntary output cuts via a phased rollout: 138,000 bpd in April, then 411,000 bpd in each of May, June and July, followed by a proposed 548,000 bpd increase for August – a move reflecting growing market confidence. Notably, the UAE is set to complete a 300,000 bpd quota increase by September, a benchmark reached ahead of the original 2026 timeline as OPEC+ expedited its capacity hike schedule.

Analysts suggest that such robust production gains could recover roughly 2.5 per cent of global demand by September. Al Mazrouei remarked that the UAE’s investments will strengthen its role within OPEC+ and that once additional capacity comes online, it will serve as a crucial stabilising factor during demand shifts.

He further argued that focusing solely on oil price levels is insufficient. Rather, OPEC+ aims to strike a sustainable balance that encourages long‑term investment. “We need the price to be right for investments to happen,” he said, warning of the consequences of underinvestment across producers.

Current market dynamics appear to confirm this approach: data from mid‑June and early July indicate that inventories across OECD nations remained stable despite the production uptick, confirming demand absorption remains robust. That observation, Al Mazrouei suggested, validates the pace of OPEC+ supply restoration and diminishes concern about a looming oversupply.

While output is increasing, policy is cautious. The Group of Eight core OPEC+ members—Saudi Arabia, Russia, UAE, Kuwait, Oman, Iraq, Kazakhstan and Algeria—are proceeding in measured increments. Al Mazrouei underscored that OPEC+ continues to meet monthly via ministerial and committee reviews, carefully calibrating production relative to shifting market fundamentals.

Beyond ensuring balance, the UAE’s production capacity expansion also carries strategic benefits. Having secured a higher individual quota, the country aims to restore and extend its market share. This reinforcement was acknowledged by external observers, including Richard Bronze of Energy Aspects, who noted “the UAE is benefiting from this speeding up of the quota increases” within a context of broader OPEC+ output acceleration.

Despite concerns about slowing economies in key importers, including China, and rising US trade tensions, OPEC+ retains a cautiously optimistic outlook. Prices in July experienced modest one‑per‑cent gains near $69 per barrel following the announcement of the August supply increase—an indicator that demand continues to absorb the additional volumes.

Nevertheless, OPEC+ remains vigilant about macroeconomic risks. Commentators have warned that demand softness later this year, driven by uncertainties in global growth and trade policies, could pressurise prices. Al Mazrouei echoed that view, stressing that short‑term supply increases must be accompanied by stable investment in oil infrastructure to prevent future shortages.

Persistent coordinated production strategy is a central theme from the Vienna seminar. Ministers emphasised OPEC+’s response to shifting fundamentals rather than geopolitical or speculative impulses. With the group moving to complete the unwind of emergency cuts, markets will closely monitor whether global demand continues to match supply advances.
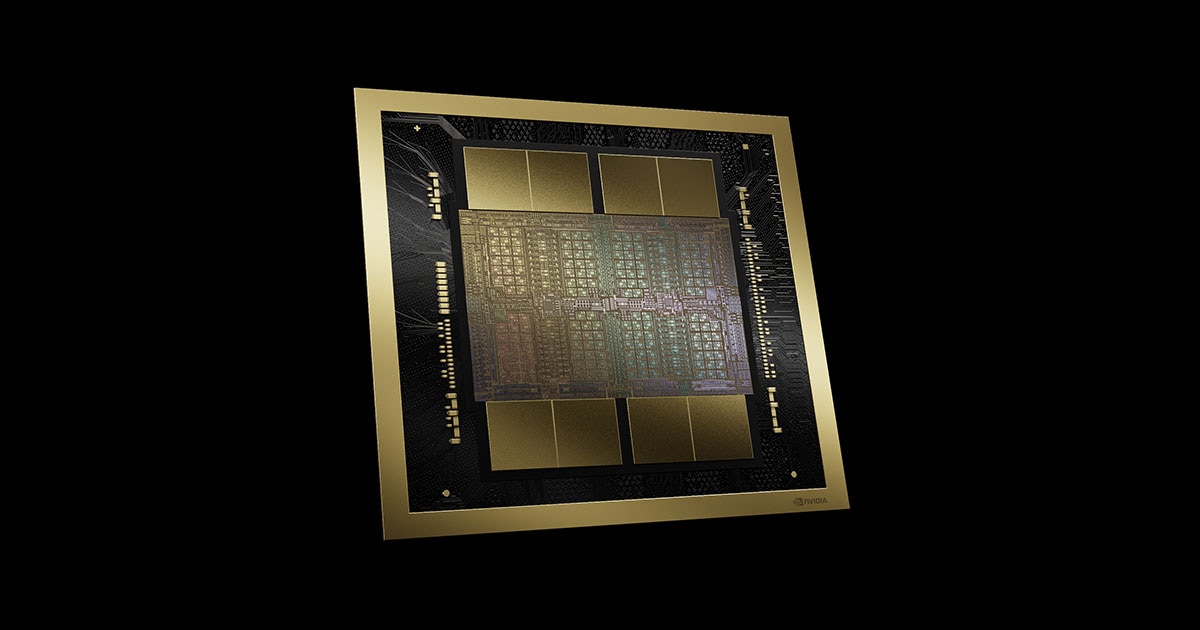
Nvidia is set to begin production of a new, lower‑spec Blackwell‑architecture AI chip for the Chinese market as early as June, aimed at complying with US export controls while maintaining its presence in the nation’s booming data centre sector. Priced between $6,500 and $8,000—significantly cheaper than the $10,000–$12,000 H20—the chip trades performance for accessibility under current regulatory constraints.

The streamlined variant is based on the RTX Pro 6000D, utilising conventional GDDR7 memory instead of high‑bandwidth memory and eschewing TSMC’s advanced CoWoS packaging to stay within US‑mandated memory bandwidth limits of 1.7–1.8 TB/s. Industry analysts note this is markedly below the 4 TB/s capability of the H20.

Yet Nvidia is not stopping there. As part of a dual‑chip strategy, it is reportedly developing a second Blackwell model scheduled to enter production by September. The specifications remain undisclosed but are expected to similarly align with US export regulations.

China accounts for around 13 per cent of Nvidia’s revenue, a slice that has shrunk sharply from a pre‑2022 peak due to export restrictions, which caused market share to decline from roughly 95 per cent to near 50 per cent today. A ban on the H20 in April prompted the company to write off about $5.5 billion in inventory and forgo an estimated $15 billion in sales.

CEO Jensen Huang has acknowledged the company’s “limited” options, stating that until a compliant design is approved by US authorities, Nvidia remains locked out of China’s $50 billion data centre market. Without it, his comments suggest many customers may migrate to domestic alternatives like Huawei’s Ascend 910B.

Domestic competition in China has intensified. Huawei’s Ascend 910B and others have gained momentum, closing the gap to Nvidia’s downgraded models within one to two years, according to semiconductor analysts. Nvidia counters this with its CUDA programming ecosystem — a key competitive advantage. With CUDA deeply integrated into AI development workflows globally, it may anchor developer loyalty even as hardware capabilities shift.

Further complicating the picture are whispers of a third chip internally known as “B30” or “B40”, which appears designed to operate in clusters and align with new export rules by focusing restrictions on individual chip rather than entire systems. Reports indicate interest from China’s leading tech companies—ByteDance, Alibaba and Tencent—with ambitions to produce more than 1 million units this year. Nvidia has not directly confirmed the chip, and one Chinese supplier, ZJK Industrial, briefly announced production ramp‑up for the B40 before retracting the statement, triggering increased market speculation.

US officials have shown concern that widespread availability of such chips—even within controlled clusters—could bolster China’s capabilities in foundational model training and inference tasks. Commerce Department Under‑Secretary Jeffrey Kessler recently told lawmakers that AI chip smuggling “is happening”, echoing longstanding export fears. Nvidia’s Huang maintains there is “no evidence” of diversion, but a consistent black‑market narrative continues to shadow the sector.

Chinese firms have outlined plans to deploy thousands of H100 and H200 chips in new data centres, particularly in western provinces such as Xinjiang and Qinghai, where abundant renewable power and cool climates offer logistical advantages. Target installations indicate upwards of 115,000 such processors in aggregated plans—most of which remain aspirational due to export prohibitions and logistical challenges.

Analysts suggest that while Nvidia’s tiered Blackwell chips may temporarily appease China’s AI infrastructure demands, the deeper impact will depend on regulatory outcomes and the strength of the CUDA ecosystem. If export restrictions ease, Nvidia stands to regain momentum; if they tighten, domestic chipmakers like Huawei will likely secure a larger foothold.

This unfolding scenario underscores a shift in semiconductor geopolitics: global tech leaders are adapting designs to fragmented access zones while local players race to fill the vacuum. The episode illustrates how export policy, market demand and strategic software assets intersect in shaping tomorrow’s AI hardware landscape.

Asia‑Pacific digital‑native firms attracted USD 15.4 billion in artificial intelligence investment in 2024, a figure reported by IDC that underscores a shift towards deeper commitments and strategic growth, even as the volume of deals declined.

Capital concentration has intensified as larger funding rounds become the norm. IDC analysts found that while the number of funded AI startups has dropped, the average investment per deal has risen markedly—reflecting investors’ preference for enterprises closer to market maturity rather than early-stage ventures.

China, South Korea, Japan and India remain at the forefront of investment flows. These major markets, with their diverse tech ecosystems and supportive policies, continue to lead, though Southeast Asian nations are gaining traction as both AI adopters and innovators.

Generative AI, a wave propelled by breakthrough models in natural-language processing and image creation, is swiftly ascending as the dominant investment theme across Asia‑Pacific. IDC forecasts that GenAI allocations will more than double by 2028, reaching USD 54.5 billion and forging a new frontier for enterprise transformation.

There is mounting evidence that corporations are pivoting from rhetoric to implementation. Only 29 percent of digital‑native businesses have scaled AI organisation‑wide, yet more than 42 percent now actively pursue co‑innovation partnerships with technology vendors to integrate AI across operations. These collaborative efforts are reshaping collaboration models between AI startups and incumbents.

Costs associated with infrastructure and data security continue to shape investment flows. Enterprise-grade AI demands not only computational muscle but also robust governance frameworks to mitigate risks such as bias, intellectual property leakage and regulatory non‑compliance. Data from the region show that 34 percent of organisations have embedded governance within generative AI software development, an advanced step beyond policy‑level oversight.

Cloud infrastructure providers are doubling down on AI support across Asia‑Pacific. Amazon Web Services announced a USD 13 billion expansion in Australia and over USD 5 billion for a Taiwan region, alongside large‑scale investments in Singapore, Malaysia and Japan. AWS claims the region’s cloud spending will reach USD 250 billion in 2025, largely driven by AI demands.

This inflow of cloud capital is critical in overcoming entry barriers. Local language support, data sovereignty and integration capabilities have become competitive differentiators for these platforms—Microsoft Azure, Google Cloud and Alibaba Cloud are aggressively pursuing similar capacity expansion. Southeast Asia, in particular, is emerging as the fastest–growing regional cloud market globally.

Startups are adapting to investors’ sharper focus on maturity and scalability. Fewer low‑valuation seed rounds are appearing; instead, late‑stage funding for companies with clear product‑market fit, real revenue streams and enterprise traction is dominating. This trend reflects an increasingly risk‑averse capital environment that emphasises depth over breadth.

The build‑up of AI infrastructure is dovetailing with rising regulatory attention. With supervision frameworks being rolled out around sensitive sectors such as finance and healthcare, investors are seeking startups equipped with compliance capabilities. For instance, financial‑services firms are prioritising traceability and governance as mission‑critical components for future‑ready AI deployment.

In geographical terms, growth hotspots vary by stage of AI ecosystem development. China leads in institutional funding and government-backed initiatives. Japan and South Korea benefit from combined strengths in industrial automation, robotics and semiconductor production. India’s vibrant startup landscape is gaining attention, particularly in generative AI and enterprise software. Meanwhile, nations such as Indonesia and Malaysia are attracting more attention as AI adoption becomes a priority for government digitalisation agendas.

Challenges persist. High‑cost infrastructure, skilled‑talent shortages and fragmented regulatory regimes pose constraints. Yet the rise of public‑private coalitions and university‑industry alliances is beginning to address these gaps—skills acceleration programmes are proliferating, and data‑sharing frameworks are gaining traction.

Investors are now looking past headline metrics to evaluate alignment with national AI strategies, such as Japan’s AI strategy and India’s push for indigenous innovation. Locally relevant models—capable of understanding linguistic diversity, cultural contexts, and industry‑specific workflows—are increasingly being favoured over globalised, one‑size‑fits‑all solutions.

This funding environment has spurred momentum in adjacent areas. Edge computing, AI‑enabled cybersecurity, AI‑driven supply‑chain optimisation and health‑tech verticals are emerging as new battlegrounds for both startups and incumbents. These sub‑domains are drawing fresh rounds of investment and pilot partnerships.

Policy trends are also influential. Governments across Asia‑Pacific are advancing data protection frameworks, AI ethics norms and public‑sector adoption plans—all contributing to clearer roadmaps for private‑sector engagement. The interlinking of regulatory reform and capital deployment is strengthening ecosystem resilience.

Investor sentiment remains cautiously optimistic. Surveys suggest that, despite macroeconomic headwinds and geopolitical risk, most executives view cloud and AI as avenues to cost reduction, efficiency gains and differentiation. As AWS’s APAC vice‑president remarked, “AI is the biggest market opportunity since cloud in 2006,” signalling sustained confidence in long‑term upside.

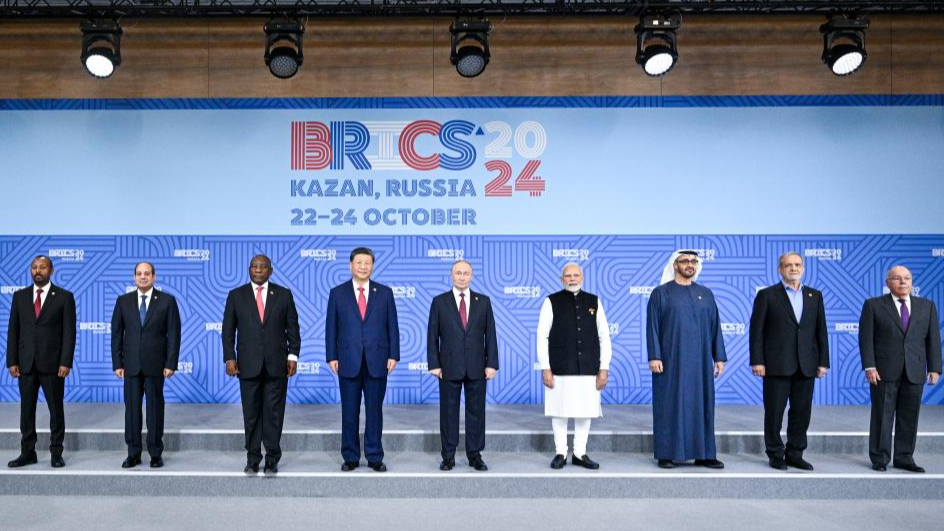
The United Arab Emirates joined the BRICS Finance Ministers and Central Bank Governors Meeting in Rio de Janeiro on 6 July 2025 under Brazil’s rotating presidency, with a focus on the global economic outlook and climate finance. Led by H. E. Mohamed bin Hadi Al Hussaini, Minister of State for Financial Affairs, the UAE delegation included key figures from the Ministry of Finance and the Central Bank of the UAE.

Al Hussaini opened his remarks by stressing the UAE’s commitment to deepening dialogue on the future of the global financial system and strengthening multilateral cooperation frameworks to face development challenges. He asserted that platforms such as BRICS provide “important opportunity to enhance global economic governance, expand access to innovative financing, and support long‑term financial stability”.

The summit’s agenda was structured into three comprehensive sessions: finance ministries, central banks, and a joint forum examining the international economic landscape, climate finance, and policy coordination. Delegates also discussed a proposal by Brazil to pilot a BRICS Multilateral Guarantee fund via the New Development Bank, aiming to mobilise private investment for infrastructure and climate-related initiatives.

In a move signalling its growing climate finance role, the UAE, alongside China, expressed intention to invest in Brazil’s Tropical Forests Forever Facility — a fund supported by BRICS to safeguard tropical forests. Leaders issued a joint statement underscoring the responsibility of developed nations to contribute to climate mitigation efforts.

Further strengthening the bloc’s role in global economic governance, BRICS finance ministers advanced a unified proposal for IMF reform. The initiative calls for a restructured quota system that reflects current global economic realities, incorporating output and purchasing power to boost representation for emerging economies. The proposal is slated for presentation at the 2025 IMF Review in December.

Discussions included plans for a cross-border payments system to enhance financial integration within BRICS, potentially reducing reliance on Western-controlled mechanisms and promoting monetary coordination among member states.

Brazilian President Luiz Inácio Lula da Silva framed BRICS as a beacon of multilateral diplomacy, likening it to the Non‑Aligned Movement, and warned against Western protectionist trends, including carbon border taxes. He emphasised that the bloc represents 40% of global output and over half the world’s population, and advocated reform of institutions like the IMF and UN Security Council.

The UAE, which joined BRICS in January 2024 and entered the NDB in October 2021, is now actively shaping the bloc’s agenda on governance, finance, and sustainability. Its support for key initiatives highlights a strategic effort to elevate its international role in emergent economies and climate action.

XI’s BICKS NO-SHOW: STRATEGIC SHIFT OR SILENT WARNING? CHINESE SYMBOLISM ON CONFIDENCE IN FULL PLAY M A Hossain In the realm of global politics, symbolism matters almost as much as substance. President Xi Jinping of China has decided not to attend this year’s BRICS summit which will be held in Rio de Janeiro. This is the first time President Xi will not be at the summit since […]

U. S. President Donald Trump has announced a sweeping 50 % tariff on copper imports, jolting commodity markets and triggering sharp moves across financial sectors. Copper futures in the United States surged to record highs, while international benchmarks in London and Shanghai retreated under mounting uncertainty surrounding shipment logistics and timing. At a Cabinet meeting, Trump confirmed the unprecedented levy, citing national security and a desire to bolster […]

Continues to see strong growth in traditional powerhouse sectors such as automotive, technology and e-commerce Sees new opportunities in Malaysia for growth in life sciences and healthcare as well as new energy DHL is well-positioned to support Malaysia’s trade and logistics ambitions with expanded investments and capabilities KUALA LUMPUR, MALAYSIA – Media OutReach Newswire – 9 July 2025 – DHL, the world’s leading logistics provider, has reaffirmed […]

Advertisements

U. S. former President Donald Trump has warned that any nations aligning with the BRICS bloc’s efforts to challenge the U. S. dollar will face a 10 % tariff, set to take effect by 1 August unless a deal is struck. Speaking at a Cabinet meeting and in a post on his Truth Social platform, Trump characterised BRICS’ currency ambitions as tantamount to “destroying the dollar,” likening such […]

SHENZHEN, CHINA – Media OutReach Newswire – 8 July 2025 – Smart home innovator Proscenic is kicking off Prime Day 2025 with one of its biggest sales yet, offering up to 40% off its top-rated vacuums on Amazon from July 8–11 (CEST). With prices starting at just €89, customers can upgrade their summer cleaning routine with powerful, easy-to-use devices designed for every home. In addition to the […]

VFS Global’s Education, Trade & Migration Services has teamed up with the Rayad Group to launch specialist advisory services for UAE Golden Visa applicants in India. The new Centres of Excellence, operating in New Delhi, Mumbai, Ahmedabad, Chennai, Hyderabad and Pune, offer legal guidance and AI-enhanced support to individuals eligible for a 10‑year UAE residence visa via government nomination—no requirement to invest in property or establish a business. […]

SINGAPORE – Media OutReach Newswire – 8 July 2025 – The Institute of Singapore Chartered Accountants (ISCA) and the Shanghai Institute of Certified Public Accountants (SHICPA) have signed a Memorandum of Understanding (MOU) today to advance the international development of the accountancy profession and foster deeper collaboration between the accounting communities of Singapore and China. Through this collaboration, ISCA and SHICPA aim to promote the development of […]

European luxury houses are experiencing a marked shift, with faltering Chinese demand prompting a strategic pivot toward alternative markets and refined brand positioning. According to Bain & Co, global personal luxury goods sales are projected to contract by 2–5 per cent in 2025, following a €364 billion market in 2024, suggesting prolonged headwinds in China and weakened consumer confidence across key economies. Concurrently, LVMH reported a 5 per cent decline in fashion and leather goods, while Kering’s Gucci saw a 24 per cent slump in Q3 2024—underscoring the drag from Chinese spending.

Amid this slowdown, brands are accelerating efforts to broaden geographic reach. McKinsey projects that the US luxury market will grow by 4–6 per cent annually through 2027—outpacing China and Europe—and emerging regions such as the Middle East, Latin America and Southeast Asia are gaining traction as bright spots. Evidence of reorientation is visible: LVMH is expanding its US production capacity, and Kering, Hermès and Prada are intensifying investment in North America.

Not all brands are equally affected. Brunello Cucinelli, less exposed to Chinese consumption, disclosed robust sales forecasts—upgrading its annual growth outlook to 11–12 per cent based on strong European demand and continued traction among ultra-high-net-worth clients. Hermès, too, has weathered the storm, maintaining sales growth while peers grapple with revenue declines.

The luxury slowdown in China is rooted in multiple structural challenges. Economic growth has softened below 5 per cent, real estate woes persist, and shifting demographic trends have eroded consumer sentiment. Simon‑Kucher reports that many Chinese consumers are becoming cost-conscious, displaying a polarization between aspirational and high-end luxury buyers, and embracing domestic brands as alternatives. Particularly, cultural shifts—such as “luxury shame”—have fuelled a move toward discretion and frugality in visible consumption.

Although major international houses such as Chanel and Dior continue to engage Chinese consumers through culturally attuned storytelling—launching region‑specific collections and targeted local campaigns—some smaller brands have shuttered stores in mainland China, acknowledging a recalibration of in‑market commitment.

Domestic luxury players are also benefitting from this transition. Laopu Gold, a jewellery brand rooted in traditional Chinese symbolism, has doubled same‑store sales and quadrupled online revenue this year, with a market valuation exceeding HK$170 billion, thereby challenging European incumbents—though its international footprint remains limited.

Global brands recalibrating their China approach are employing a range of strategic pivots: tighter inventory control to avoid discounting and preserve brand equity; stimulant-focused aspirational campaigns; and product diversification into understated luxury or second-hand luxury to resonate with new consumer segments. The second‑hand luxury market in China alone has grown at an annual rate exceeding 30 per cent since 2020.

Europe itself remains central to the luxury ecosystem, as evidenced by European markets holding nearly half of Armani’s revenues in 2024—an increase relative to Asia Pacific’s diminished share—while the group strategically channels investment into flagship stores and digital-commerce. Cost control, brand consistency, and quality-focused messaging have become priorities as demand becomes more selective.

Globally, brand strategies are evolving with renewed emphasis on sustainability, resilience and storytelling. Price hikes once driven by so‑called “greedflation” are now tempered, with average increases forecast at 3.5 per cent in 2025—lower than peak levels—and justified by genuine craftsmanship and material innovation. Product lines are being refined: leather goods, jewellery and beauty segments are poised for stronger performance, while deeper integration of sustainability and consumer‑centric narratives is prioritised.

Brands are also investing in localisation in other markets and exploring omnichannel retail strategies. Digital-owned channels, experiential stores, and culturally sensitive campaigns are being deployed to engage consumers in tier‑2 and tier‑3 urban centres, particularly in Asia outside China.

European luxury houses are at a strategic inflection point: with the decline in Chinese demand now measurable, success hinges on geographic rebalancing, product portfolio refinement, inventory discipline and culturally resonant marketing. The winners will be those able to preserve brand prestige while adapting to economic reality and evolving consumer psychology across diverse global markets.

Iran has achieved its highest energy output in nearly half a century, as crude production and exports continue expanding despite escalating tensions and Western sanctions. In 2024, total oil output—including crude and gas liquids—reached approximately 5.1 million barrels per day, marking levels unseen since before 1978. Indicators from the first half of 2025 signal further growth, reinforcing Tehran’s stance that its energy sector remains resilient even under pressure.

China remains the principal destination for Iranian crude. According to Vortexa and Kpler data, Beijing imported an average of 1.4 million bpd of Iranian crude and condensate during the first half of 2025. In June alone, Chinese imports surged to a record 1.8 million bpd, exploiting floating storage reserves accumulated previously.

Despite U. S. legal restrictions, these volumes endure through intricate shipping methods and discounts. As of June, Iranian crude was being sold to China at discounts of $3.30–$3.50 per barrel below Brent—the widest spread since 2023—partly triggered by weak demand from independent Chinese “teapot” refineries and additional U. S. sanctions on mid-tier processing firms in Shandong province. Refineries such as these have cut utilisation rates to around 51 per cent, down from 64 per cent last year.

Iran’s export capacity has been safeguarded by infrastructural alternatives designed to bypass the Strait of Hormuz. The Goreh‑Jask pipeline and Jask terminal—capable of exporting around 300,000 bpd—offer strategic flexibility, although actual utilisation fell to under 70,000 bpd in late 2024. Elsewhere, Saudi Arabia and the UAE have also enhanced their own bypass routes through the Strait to mitigate risk.

Nonetheless, current events pose fresh challenges. Israeli strikes in June damaged parts of oil infrastructure near Tehran and affected the South Pars gas field—responsible for up to 700,000 bpd of condensate. Exports from key terminals such as Kharg Island briefly dropped below 120,000 bpd from a weekly average of 1.7 million bpd. However, Iran manages significant stockpiles—approximately 27.5 million barrels afloat—that can sustain exports for weeks.

Domestic dynamics complicate this energy story further. Iran’s gasoline consumption has outpaced refining capacity by nearly 15–20 per cent since late 2024, triggering reliance on reserves and imports to fill shortfalls. Peak summer demand reached unprecedented levels, surpassing 143 million litres in a single day. Panic-buying followed some military strikes, exposing strains in planning and supply.

Iran’s global energy standing aligns with broader market projections. The International Energy Agency forecasts that global oil supply will exceed demand in 2025 by around 1.8 million bpd, a backdrop that may soften impacts from Iranian output. At the same time, discussions in Washington about lifting U. S. sanctions have raised concerns in Beijing, particularly for its fragmented independent refining sector. Analysts warn that a sudden lifting of sanctions could flood global markets—with an additional 500,000 bpd of Iranian oil—and undercut smaller Chinese players by crushing their margins.

Iran’s energy strategy shows calculated resilience. While nuclear tensions invite military risks, the oil ministry appears intent on diversifying markets, expanding infrastructure, and leveraging geopolitical leverage. Iran Daily reported that production comprised 4.3 million bpd of crude plus around 0.7 million bpd of other liquids in 2024. Analysts advocate that increased domestic use, ageing facilities, and investment gaps could temper the pace of future gains unless Tehran secures long-term funding and technical partnerships.

Observers note the inherent paradox: Iran continues ramping production even as global energy security faces renewed uncertainty. Control over chokepoints such as the Strait of Hormuz remains central. Although no full closure has occurred—the Iranian parliament proposed closure in late June pending council approval—the symbolic threat alone underlines Tehran’s strategic positioning. Global markets, buoyed by inventories and diversified routes, have so far absorbed the shock. Yet any escalation could rapidly unsettle thresholds.

Bitcoin held in exchange wallets has plunged to levels not seen in years, data from Coinglass and Glassnode indicate, underlining a shift towards long‑term holding and tightening liquidity.

According to Coinglass, total Bitcoin reserves across centralised exchanges have fallen to approximately 2.07 million BTC, marking a fresh low measured in this multi‑year timeframe. Glassnode data confirms that exchange-held Bitcoin as a percentage of total supply has dipped below 15%—a level unseen since 2018.

The depletion has been rapid: Coinglass reports that around 65,000 BTC exited major exchanges last week, pushing exchange balances down to near record lows. CryptoQuant analysis shows hot OTC reserves have also shrunk to roughly 146,000 BTC—declining from 480,000 BTC in September 2021—signalling broader supply erosion across both exchange and OTC channels.

Market analysts interpret these metrics as evidence of sustained accumulation by both retail and institutional investors. Transfers to cold storage and self‑custody wallets are rising sharply, coinciding with surging inflows to spot Bitcoin exchange‑traded funds since early 2024. Long‑standing holders and whales appear to be shifting their assets off‑platform, leading to what many describe as a looming supply shock.

This supply constriction factors into Bitcoin’s recent upside, where the price has rallied above the US $100,000 threshold and briefly touched US $110,000. Reduced available supply on exchanges dampens immediate selling pressure, while rising demand—particularly from ETF vehicles—supports upward momentum. Sentiment indicators reinforce this stance: CryptoQuant notes more than 85% of Bitcoin holders are in profit, suggesting limited incentive to sell.

Institutional trends underpin the narrative. Major asset managers such as BlackRock and Fidelity are funneling substantial reserves into ETF custody, moving assets off‑exchange and altering the liquidity dynamic. Corporates including MicroStrategy continue on‑chain accumulation as part of treasury strategies, while some national financial bodies are exploring Bitcoin holdings.

Analysts warn, however, that reduced float may lead to heightened volatility. A supply shock typically amplifies price moves—up and down—with heavy liquidations already observed: Coinglass data shows US $203 million of Bitcoin short positions were liquidated in under 24 hours during the brief rally above US $110,000. At the same time, positive global factors such as easing US–China trade tensions and expectations of interest‑rate cuts are adding fuel to risk assets, including Bitcoin.

Examining the wider picture, the halving event of April 2024, which halved block rewards to 3.125 BTC, continues to weigh on supply dynamics. With new issuance curtailed and existing supply migrating into private custody, on‑chain metrics show persistent outflows from exchanges. CryptoQuant’s Fund Flow Ratio also points to historic levels of “hodling” behaviour.

Whale activity mirrors the shift. Over the past month, Coinglass recorded withdrawals totalling more than 56,000 BTC from centralised exchanges. At the same time, metrics from CryptoQuant show centralised exchange reserves falling by roughly 550,000 BTC since mid‑2024, tightening the supply significantly.

While most analysts interpret the current balance trends as bullish, some caution is warranted. If investor sentiment reverses or macro‑economic shocks trigger rapid sell‑off, the thin on‑exchange liquidity could exacerbate price swings. Still, the dominant view frames the phenomenon as a structural supply retraction, particularly intensified by institutional demand.

TikTok is preparing a standalone version of its app for U. S. users, slated for launch on 5 September 2025, as part of its strategy to comply with the U. S. law mandating a sale or ban of its American operations. The current app will remain functional until March 2026, although officials say this date is subject to change. Under the Protecting Americans from Foreign Adversary Controlled […]

By Nantoo Banerjee It is difficult to believe that India, the world’s fourth largest economy by gross domestic product (GDP) and a major military power, ranks below even the tiny states of Kuwait and Greece when it comes to defence spending as a percentage of GDP. Considering the tricky geo-political situation in the south Asian […]

GUIYANG, CHINA – Media OutReach Newswire – 7 July 2025 – Eco Forum Global Guiyang 2025, China’s only national-level international forum dedicated to ecological civilization, kicked off on Saturday in Guiyang, the capital of southwest China’s Guizhou Province. This photo taken on July 5, 2025 shows a sign of the Eco Forum Global Guiyang 2025 in Guiyang, southwest China’s Guizhou Province. This year’s event, themed “Harmonious coexistence […]

KUALA LUMPUR, MALAYSIA – Media OutReach Newswire – 7 July 2025 – Kenanga Investment Bank Berhad (“Kenanga Group” or “The Group“), Malaysia’s no. 1 issuer of structured warrants, proudly announces the launch of its first-ever Hang Seng China Enterprises Index (“HSCEI“) structured warrants – HSCEI-CAA and HSCEI-HBA – and Hang Seng TECH Index (“HSTECH“) structured warrants – HSTECH-C30 and HSTECH-H27 – under its flagship brand, NagaWarrants by […]

Dubai’s Roads and Transport Authority has formalised a Memorandum of Understanding with Pony. ai to commence pilot trials of self‑driving vehicles across the emirate later this year, laying the foundation for a fully driverless commercial service by 2026. The agreement marks a pivotal milestone in Dubai’s Smart Self‑Driving Transport Strategy, which aims to convert a quarter of the city’s journey volume into autonomous mobility by 2030. Senior […]

Finance ministers from the BRICS nations have pressed the International Monetary Fund to adopt sweeping reforms that would recalibrate its governance and better represent developing economies. They jointly advocated for a modernised quota formula, increased voting power for emerging and low-income countries, and the installation of a merit-based leadership system, rather than the customary European-led management. Meeting in Rio de Janeiro ahead of the BRICS summit, ministers […]

Abu Dhabi Securities Exchange has opened the pricing stage for the first blockchain-based digital bond in the Middle East and North Africa, issued by First Abu Dhabi Bank and powered by HSBC Orion, marking a significant leap in regional capital market innovation. Global investors will be able to participate through accounts at the Central Moneymarkets Unit in Hong Kong, Euroclear, Clearstream or via HSBC Orion, either directly or through […]

Heads of government gathered in Rio de Janeiro for the 17th BRICS summit on 6–7 July 2025, yet Iran’s President Masoud Pezeshkian will not attend in person, opting to join virtually amid escalating regional tensions. This marks a notable shift in IRGC diplomatic strategy and signals Tehran’s cautious engagement with the global bloc. Brazilian host Lula da Silva extended formal invitations to all member nations, including Iran. […]

By Nitya Chakraborty On the eve of the 17th BRICS Summit scheduled at Rio de Janeiro in Brazil on July 6 and 7, the ongoing discussions among the senior officials of the member countries for the preparation of the draft joint declaration from the Summit, are showing big divergence of views on the two major […]

Global tourism is projected to reach 30 billion trips by 2034 and contribute $16 trillion to world GDP, growing 1.5 times faster than the global economy, according to the World Economic Forum’s latest report. Amid this surge, Saudi Arabia is emerging as a pivotal force, ranking the second fastest-growing tourism destination and leading global investments in innovation, infrastructure, and sustainability The WEF report, Travel and Tourism at a Turning […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA