News related to
prices

Oil benchmarks surged on Friday following a major Israeli military operation in Iran, sparking fears over potential disruptions to Middle Eastern oil supplies. Brent crude climbed more than 7 %, reaching an intraday peak of approximately $78.50, before settling at around $74.23 a barrel. The US West Texas Intermediate benchmark mirrored the jump, with intraday highs near $77.62 and a close at $72.98—a 7 % increase and the largest […]

FDI inflows into the Gulf Cooperation Council economies are set to decelerate in 2025, according to S&P Global Market Intelligence, ending a decade-long surge. Investor apprehension, shaped by evolving US trade policy, subdued oil prices, and delayed economic diversification, is expected to weigh on international capital flows. Investor uncertainty stems partly from the US administration’s tariff stance. Though current levies exclude energy products, supply‑chain disruptions and broader uncertainty […]

Over 1,800 flights have been disrupted and more than 650 cancelled after Israel’s airstrikes on Iran prompted sweeping airspace closures over Israel, Iran, Iraq, Jordan, and Syria, prompting carriers worldwide to reroute or suspend services. Tel Aviv’s Ben Gurion Airport remains closed indefinitely, while Iran’s state media confirmed grounding all flights. The European Union’s aviation safety agency has classified the region as a high-risk zone.

Flight-tracking platforms like Flightradar24 and Cirium recorded a sudden clearance of air traffic in the affected region. Planes were diverted south via Egypt and Saudi Arabia or north through Turkey, Azerbaijan, and Central Asia. Airlines such as Emirates, Qatar Airways, Etihad, Air India, Lufthansa, British Airways, Delta, United, and El Al have either cancelled or dequeued flights due to safety concerns.

El Al announced suspension of all inbound and outbound operations, evacuating its fleet from Israel. Its budget counterpart, Israir, has similarly withdrawn aircraft from Tel Aviv, with full suspension through to at least 15 June. On the US side, United suspended its Newark–Tel Aviv service until 30 June, and Delta halted routes from JFK through 31 August.

In Europe, national carriers tightened flight operations. Lufthansa extended cancellations to Tel Aviv and Tehran through July, and halted flights to Amman and Beirut until 20 June. KLM, SWISS, Aegean, Ryanair, and EasyJet collectively cancelled flights into Israel, some as late as October. Turkish Airlines, Flydubai, Pegasus, and AJet suspended routes to Iran, Iraq, Jordan, and Syria until mid‑June.

The flight disruptions are exacting a toll on airlines’ financial performance. US carriers Delta, United and American saw share prices fall between 3.5% and 5%, while the US Global JETS ETF dropped around 3.5%. Rising oil prices—spiking between 7% and 11%—have compounded the burden. Investor sentiment across transatlantic carriers remains cautious as volatility in the Middle East continues to unsettle markets.

Aviation risk consultancy Osprey Flight Solutions reports six commercial aircraft have been shot down unintentionally, with three near-miss incidents since 2001, including downed civilian jets in Kazakhstan and Sudan. Such events have heightened the emphasis on airspace risk assessment in conflict zones. International Air Transport Association Director‑General Willie Walsh stressed the need for more coordinated information sharing between states, airlines, and global flight advisory systems.

Operation Rising Lion, the designation given to Israel’s offensive, involved over 200 fighter jets striking more than 100 Iranian targets—including nuclear enrichment sites at Natanz, ballistic missile facilities, and senior military commanders. Iran retaliated with missile and drone strikes, although most were intercepted. The escalation has forced Israel to place its defence units on high alert for further retaliation.

Operationally, airlines have adapted fast. Air India rerouted 12–16 flights—spanning transatlantic and Europe‑India services—via Vienna, Frankfurt and other hubs. Emirates diverted flights from Manchester to Istanbul, and Flydubai rerouted services from Belgrade to Yerevan. Abu Dhabi’s airports issued advisories urging passengers to verify status before travelling, as disruptions are expected to persist through the weekend.

The widespread closure underscores the commercial aviation sector’s exposure to geopolitical volatility. As routes are restructured to avoid conflict zones, carriers face longer routings, elevated fuel costs, crew redeployments, and cancellations—all eroding profit margins already weakened by post‑pandemic recovery strains.

Safety remains paramount. While no civilian aircraft have been lost in the current hostilities, the track record of past downings amplifies concerns. Airlines now rely heavily on real‑time risk intelligence from platforms like OPSGROUP’s Safe Airspace and coordination with aviation authorities. Russia’s Rosaviatsia has also barred its carriers from the contested airspace and banned flights to Iran and Israel until at least 26 June.

Global aviation authorities now face calls to bolster measures: real‑time intelligence sharing, harmonised flight advisories, and contingency routing to maintain safety while minimising disruption. But as long as the Israel‑Iran confrontation rages, the skies remain fragile. Passengers worldwide are urged to monitor airline communications and government travel advisories as the situation remains highly fluid.

Markets across the Gulf and beyond plunged on Friday following a sharp military escalation after Israel struck Iranian nuclear and military sites, triggering drone counter‑attacks by Iran and a broader risk‑off reaction among investors.

Dubai’s benchmark index tumbled 5.1%, its steepest single‑day loss since May 2022, while Abu Dhabi’s dropped 3.5% before paring losses. The rout extended into Israel, where the shekel slid as much as 3.5% against the dollar, with long‑dated Israeli bonds and select regional government debt also weakening.

Commodity markets mirrored investor anxiety. Brent crude surged over 6%, touching its highest level in nearly five months, as traders assessed the risk of supply disruptions through the Strait of Hormuz. Gold likewise rallied, reaching two‑month highs as capital flowed into safe‑haven assets.

Airline stocks were among the hardest hit. Air Arabia shares plunged more than 4%—some reports suggest nearly 8%—as carriers rerouted flights away from airspace over Iran, Israel, Iraq and Jordan. Regional exchanges in Riyadh and Doha were closed on Friday, with trading set to resume on Sunday amid anticipation of continued volatility.

The market shockwaves reverberated worldwide. Europe, Asia and US indices all registered dips: the S&P 500 dropped roughly 0.4% mid‑day, the Dow slipped nearly 1.8% and the Nasdaq around 1.3%, while Tokyo’s Nikkei and Hong Kong’s Hang Seng also declined.

Analysts warned that while markets historically absorb such shocks fairly quickly, the sustained threat of conflict brings inflation and growth risks. Chris Scicluna of Daiwa Capital Markets noted the initial oil spike “hasn’t been too extreme” but cautioned that a sustained rise toward US $80 oil would be problematic for central banks. Meanwhile, Tariq Kakish of FH Capital pointed out that geopolitical instability remains “the key factor affecting investors’ sentiments”.

Concerns centred on the Strait of Hormuz, which channels approximately one‑third of global seaborne oil, raising the potential for disruption. Demand for insurance on tankers in the Gulf surged, and traders remain on edge over possible Iranian retaliation targeting shipping or oil infrastructure. However, OPEC+ sources suggest that Saudi Arabia and others retain sufficient spare capacity and are monitoring the situation closely.

Financial markets also showed classic risk‑off behaviour: US Treasury bonds rallied even as yields ticked higher, reflecting investor concerns about energised inflation, as per Axios commentary. The dollar strengthened, while gold and the Swiss franc benefited from increased flight‑to‑safety demand.

In Asia, the ASX 200 slipped modestly, offsetting losses in financials and consumer sectors with gains in energy and mining stocks. In Mumbai, Reliance Industries’ shares fell nearly 1.8% as Brent crude surged past $75 per barrel amidst the tensions.

Political and economic analysts emphasise two themes: the possibility of an enduring inflation shock from energy price escalation, and the risk of prolonged conflict dragging in wider regional powers. While some argue Gulf states may help mitigate supply-side shocks via increased production, others highlight that even modest increases in oil prices could influence global inflation and central bank policy.

Despite the turbulence, multiple analysts noted past flare‑ups between Israel and Iran tended to cool within weeks, with markets rebounding once diplomatic pathways re‑opened. Yet this episode differs: it involves overt attacks deep into Iranian territory, targeting nuclear and ballistic infrastructure, and marking a new phase in the conflict. The outcome may recalibrate norms for military engagement in the region—and investor expectations alongside them.

Foxconn’s latest customs data confirms that from 1 March to 31 May 2025, an overwhelming 97 per cent of all iPhones assembled in India were destined for the United States, totalling $3.2 billion in exports—nearly double the 50 per cent average seen throughout 2024. May alone accounted for almost $1 billion, the second‑highest monthly export value ever recorded—just behind March’s $1.3 billion. This sharp shift reflects Apple’s concerted effort to navigate escalating U.S. tariffs targeting Chinese […]

UAE’s economy is set to expand by 4.6% in 2025, bolstered by a strong non‑oil core and a gradual return in oil output, according to projections from the World Bank’s June “Global Economic Prospects” edition. This represents a 0.6‑point upward revision from January. The outlook for 2026 has also been upgraded to 4.9%, with growth anticipated to hold at that level in 2027. At the heart of […]

Stock markets across Asia plunged as global investors rushed to safe-haven assets following a military strike by Israel on Iran’s nuclear and ballistic missile facilities, intensifying geopolitical tensions in the Middle East. U.S. equity futures dropped sharply, while commodity prices surged—fuelled by fears of supply disruption and escalating conflict.

Crude oil futures reacted violently, with Brent surging about 9 % to approximately US $75.36 per barrel and West Texas Intermediate climbing to US $74.20, both marking the largest daily gains in months. Goldman strategists and energy analysts attributed the spike to risk premiums linked to potential retaliation and threats to regional infrastructure, especially across the Strait of Hormuz.

Precious metals and defensive currencies were also swept up in the panic. Spot gold rose by around 1.5 % to trade near US $3,434 per ounce, inching closer to its April record peak of US $3,500. The Swiss franc strengthened by roughly 0.4 % to reach two‑month highs against the U.S. dollar, while the yen appreciated by about 0.3 %—classic indicators of risk-off sentiment.

Asia’s leading equity indices suffered notable losses: Tokyo’s Nikkei 225 fell between 1.2 % and 1.4 %, Seoul’s Kospi dropped about 1.1 %, and Hong Kong’s Hang Seng declined roughly 0.8 %. U.S. S&P 500 E‑mini futures and Nasdaq futures plunged between 1.7 % and 1.8 %, while Pan‑European STOXX 50 futures slid around 1.6 %.

In India, the Nifty 50 and Sensex tumbled approximately 1.2 %, with the oil and gas sector leading losses thanks to narrower refining margins and soaring crude prices. Stocks of Bharat Petroleum, Indian Oil Corporation and HPCL each shed between 3.5 % and 6 %. Airline stocks, already shaken by a recent Air India crash near Ahmedabad, declined further as travel costs and uncertainty weighed heavily.

Debt markets saw a flight to quality. U.S. Treasury bonds rallied, pushing the 10‑year yield down to around 4.31–4.35 %, its lowest in a month. Currency markets mirrored these moves: the dollar index rose around 0.5 %, while the euro and sterling retreated slightly.

Analysts suggested the next moves hinge on Iran’s response. Charu Chanana, chief strategist at Saxo, noted that if tensions ignite, safe-haven demand and commodity volatility will likely persist. Matthew Haupt from Wilson Asset Management described this as a “classical risk‑off move,” adding that duration and scale of Tehran’s likely response will shape market impact.

This episode compounds earlier market strains. The global economy already faces headwinds from volatile U.S. trade policy and high inflation, while negotiations over Iran’s nuclear programme have stalled. A planned sixth round of talks in Oman was overshadowed as military actions overshadowed diplomacy.

Market indicators suggest traders are swiftly reducing risk exposure ahead of the weekend. Tony Sycamore from IG forecast continued selling in equities, saying that prudent investors will likely trim positions until further clarity emerges.

Energy market strategists warned of wider contagion. According to Saul Kavonic of MST Marquee, unless Iran specifically targets major oil infrastructure, supply impact remains limited—but persistent unrest could be enough to constrain output and flow through the region.

Advertisements

Running a business in 2025 is increasingly moving online — and documentation is no exception. One of the most common questions among entrepreneurs and freelancers is how to quickly and correctly issue an invoice without involving accountants, dealing with paperwork, or registering on complex platforms. While managing finances and sending invoices is becoming simpler, it’s just as important to have a reliable online presence to support your […]

The World Bank has raised its forecast for the UAE’s gross domestic product to 4.6 percent in 2025, marking a notable upward revision of 0.6 percentage points from its January outlook. The renewed projection is driven by strong momentum in non‑oil sectors—tourism, construction, transportation and finance—while the phased easing of OPEC+ production cuts is expected to support oil output growth.

Overall GCC growth is also tipped to rise to 3.2 percent in 2025, climbing further to 4.5 percent in 2026 and 4.8 percent in 2027. Globally, however, the World Bank projects a slowdown to 2.3 percent in 2025, the weakest expansion outside recessions since 2008 — due mainly to elevated trade tensions and policy uncertainty.

Within the UAE, the non‑oil sector is poised to expand by roughly 4.9 percent in 2025, outpacing oil‑based growth. This upturn reflects robust activity in tourism, real estate, transport, and financial services. The first nine months of 2024 saw non‑oil GDP rise by 4.5 percent, a stronger contributor than the 1.5 percent growth recorded in oil GDP.

Analysts point to the UAE’s strategic economic diversification as central to this trajectory. Public investment in infrastructure and tech industries, alongside governance reforms aimed at enhancing the business environment, have significantly boosted competitiveness. Free‑zone facilities and logistics integration—especially in Abu Dhabi—are improving supply chain efficiency, while the nation’s Comprehensive Economic Partnership Agreements are broadening international trade links.

OPEC+ adjustments remain influential. The group is implementing a gradual withdrawal from voluntary oil output limits between May 2025 and September 2026, which the World Bank says will bolster oil GDP amid global price pressures. The UAE’s oil GDP is thus anticipated to gain ground after a lull, providing a stabilising complement to the diversification agenda.

Risks persist, including uncertainty around global trade, fluctuating energy prices, and regulatory slowdowns. The World Bank notes that logistics sectors across the GCC could be affected by broader trade disruptions. Meanwhile, lower oil revenues may limit fiscal flexibility, even as sovereign buffers remain robust.

In Abu Dhabi, economic diversification efforts are visibly gaining traction. The non‑oil sector there grew by 6.2 percent in 2024, representing over half of the emirate’s GDP at AED 644.3 billion. Large‑scale initiatives—such as new business districts, enhanced transport infrastructure, and collaborative zones linking academia with private industry—are expanding economic capacity.

Despite global headwinds, the UAE’s fiscal position remains sound. The 2024 fiscal surplus stood at approximately 4.6 percent of GDP, supported by counter‑cyclical spending and healthy sovereign reserves. Inflation has moderated to near 2.3 percent, with the Central Bank maintaining supportive liquidity without compromising price stability.

Employment is also expected to benefit. The International Labour Organization projects job growth to remain around 3.3 percent in 2025, with unemployment steady at roughly 2.1 percent. Nonetheless, structural issues—such as high youth unemployment and gender disparities—persist, particularly among younger and female cohorts.

Looking ahead, the UAE is on track to sustain growth above 4 percent through 2027, with oil and non‑oil sectors contributing in tandem. Yet, global vulnerabilities underscore the need for continued diversification, fiscal prudence and trade resilience.

Japanese investment firm Metaplanet has scaled its way into the top ten corporate Bitcoin holders by acquiring a further 1,088 BTC for roughly $117.9 million, boosting its total holdings to 8,888 BTC and vaulting above Galaxy Digital and Block Inc. into ninth place worldwide. The firm purchased the coins at an average price of approximately $108,400 each, signalling deepening confidence in its treasury strategy underpinned by sustained market uncertainty.

Metaplanet’s pivot from hotel management to cryptocurrency began in 2024. Since then, its stock has surged dramatically, at times rising over 8,850 per cent in just two years, as the company pursued a bitcoin‑centric treasury model. That performance has mirrored similar moves in the sector, including U.S. software firm Strategy, whose model inspired Metaplanet’s pivot.

The firm announced a plan to raise approximately $5.3–5.4 billion via stock acquisition rights—the largest warrant issuance in Japan—to scale its bitcoin holdings to 210,000 BTC by the end of 2027. Metaplanet previously outlined a target of 21,000 BTC by the end of 2026, which has since been superseded by the more ambitious 100,000 BTC milestone for next year.

Metaplanet’s CEO, Simon Gerovich—a former Goldman Sachs derivatives trader—told investors that Bitcoin serves as a hedge against a weakening yen, prolonged negative interest rates, and rising concerns over sovereign debt, setting it apart from traditional safe‑haven assets such as government bonds. This reflects broader market trends: analysts at Bitwise and Bitfinex suggest high sovereign bond default probabilities and consolidation above cost basis support further upside for Bitcoin prices.

Metaplanet’s strategy, dubbed the “555 Million Plan” and following its earlier “21 Million Plan”, channels nearly all funds raised into bitcoin purchases while maintaining flexibility to adjust funding based on market conditions and shareholder dilution safeguards. Its holdings, valued at close to $1 billion, now compare with those of Strategy, which boasts over 580,000 BTC, and ranks first among corporate holders.

Investor reactions have been swift: Metaplanet’s stock surged 15–22 per cent following the acquisition announcement and financing plan, underscoring strong market appetite for its bold strategy. Still, scepticism remains; industry analysts such as Standard Chartered caution that corporate reliance on Bitcoin may heighten balance‑sheet risk during market downturns and raise concerns about overvaluation in proxy‑stock structures.

This aggressive accumulation mirrors industry-wide dynamics. Over 60 public companies now hold more than 3 per cent of Bitcoin’s total supply, with estimates suggesting corporate demand may channel up to $330 billion into Bitcoin by 2029. In this environment, Metaplanet is positioning itself as Asia’s counterpart to MicroStrategy, not only through fearless accumulation but also via initiatives like the forthcoming ‘Bitcoin Hotel’ in Tokyo and educational outreach through its Japanese licence of Bitcoin Magazine.

Nevertheless, experts warn that this model carries heightened exposure to Bitcoin’s extreme volatility, potential regulatory shifts, and macroeconomic undercurrents. While some view Metaplanet as a pioneer advancing institutional acceptance of crypto, others argue the strategy intensifies concentration risks within corporate treasuries.

Dubai master developer Emaar Properties has introduced VYOM, a digital resale platform designed to streamline the sale of Emaar homes through secure, transparent and user‑controlled processes. Available now to global users, the platform enables homeowners and investors to manage listings, upload images, set prices and handle inquiries—all within an integrated, intuitive interface.

Mohamed Ali Alabbar, Emaar’s founder, emphasised that VYOM reflects a shift towards autonomy, trust and speed in the property market. “VYOM is more than a platform—it’s a new way of thinking about property resale,” he said, adding that it places control firmly in the hands of customers. The move addresses persistent inefficiencies in traditional resale methods, including pricing opaqueness, communication delays and fragmented processes.

VYOM emerges as part of Emaar’s broader digital transformation strategy. The platform aims to reduce friction in resale transactions, allowing direct buyer‑seller interactions without intermediaries. For users, the result is a streamlined experience: creation of personalised listings, real‑time updates, and enhanced transparency across the transaction journey.

Analysts suggest the launch positions Emaar ahead in a market increasingly adopting digital property solutions. Industry commentary notes that VYOM could prompt competitors—such as Damac Properties—to roll out similar digital resale or even rental platforms. One real estate expert reflected, “With Damac launching its e‑commerce property site, a trend is underway”—a transformation likely driven by rising online demand.

Emaar views VYOM as the first stage of a phased rollout. Future enhancements include integrated rental management and expanded analytics tools, offering marketing insights and valuation support to users. The initial launch focuses on resale, but the roadmap points to a full‑cycle platform guiding owners from purchase through resale and rental.

Market conditions in Dubai reinforce the appeal of digital platforms. Transaction volumes remain buoyant, and buyers are increasingly seeking end‑to‑end online clarity. Traditional resale has been hampered by agents’ commissions and uneven quality, often leaving sellers and buyers without real‑time updates or direct communication. VYOM seeks to bridge these gaps.

Emaar’s track record lends weight to this evolution. The company has been steadily digitising its portfolio, incorporating virtual tours, property management apps and smart home integrations in key UAE developments. VYOM aligns with these investments, reinforcing Emaar’s image as a tech‑forward developer.

Technology infrastructure behind VYOM is built on robust security and data‑protection standards, ensuring user authenticity, encrypted communications, and verified listings. This digital-first model is expected to reduce instances of fraud and misinformation that sometimes plague secondary property markets.

Investor sentiment appears optimistic. Although Emaar has not disclosed specific growth targets, experts believe VYOM could significantly boost customer retention and retention rates for repeat domestic and overseas investors. A senior property economist commented that such platforms “elevate resale liquidity and deepen buyer confidence in the Emaar brand”.

The Dubai Land Department, while not officially commenting, has previously expressed support for digitisation in property services and title registration. Platforms like VYOM may dovetail with government efforts to digitalise real estate transactions across the emirate, including escrow reforms and blockchain‑enabled land registry trials.

Homeowners who have previewed VYOM report an improved experience. One early user noted that the ability to revise prices instantly and manage viewings through the platform eliminated delays often caused by agent coordination. The user highlighted how features such as buyer messaging templates helped standardise and speed up negotiations, while integrated market insights assisted pricing strategies.

Emaar has also invested in training programmes for sales teams and customer‑care staff to ensure consistent support for VYOM users. This back‑end readiness suggests the platform will do more than merely exist online; it will be backed by human expertise and service continuity.

Financial analysts underscore the commercial implications. VYOM can retain undisclosed resale transaction fees and promote secondary market activity within Emaar’s ecosystem. Over time, data harvested from user behaviour could feed predictive tools, generating new revenue through ancillary services such as refinancing, renovation or interior design partnerships tied to resale activity.

While VYOM’s earliest phase targets the resale of Emaar properties—off‑plan and completed—broader implications may follow. Market watchers consider the platform a bellwether for digital transformation in real‑estate heavyweights, signalling a shift towards owner-empowered brokerage and vertical integration.

Deyaar Development PJSC has officially launched Downtown Residences, a twin-tower residential project rising to a striking 445 metres in Dubai’s golden triangle where Sheikh Zayed Road meets Downtown Dubai and Business Bay. The development will house 522 units across one- to three-bedroom apartments, duplexes, penthouses and an exclusive Royal Palace perched at the summit, marking a new milestone in vertical luxury living.

Dubai is amid a surge of super‑tall skyscraper projects. Alongside Deyaar’s venture, Burj Azizi is planned to reach approximately 725 metres, while Burj Binghatti Jacob & Co is projected at around 557 metres. Downtown Residences, with more than 110 floors, will rank among the tallest residential towers in the emirate and is set for delivery in the fourth quarter of 2030.

Deyaar’s chief executive, Saeed Mohammed Al Qatami, described the project as a transformation of urban living, combining comfort, style and advanced amenities. He emphasised its potential to attract both residents and investors while enhancing the Dubai skyline. The company signals that the project is part of its strategy, expanding its 2025 pipeline beyond an earlier target of AED 8 billion through new launches.

Drawing inspiration from Maslow’s Hierarchy of Needs, the design concept organises the residential experience into five vertical zones, each catering to a different level of wellbeing and lifestyle aspiration. The lower zone—Dynamic Avenue—will include family areas such as children’s creative spaces, playrooms, and communal lounges, fostering social connection. The Sensory Oasis, positioned midway, will offer floating gardens, air yoga zones, AI-powered meditation pods and an “invisible spa” combined with fitness amenities.

At roughly 100 floors high, Summit Society will provide private dining venues, exclusive lounges, and a screening room. The Residents’ Club will include AI-enhanced workspaces, executive pods and networking hubs, while the Sky Pinnacle 360 zone culminating in the Sky Mansion and Royal Palace will represent the architectural pinnacle.

Architecture highlights include a dramatic central slit, vertical gardens woven through the structure, and podium-level urban oases. Outdoor terraces and community spaces such as The Collective and Serenity Haven aim to blend urban energy with serenity. Panoramic views of the Burj Khalifa, Arabian Gulf and Sheikh Zayed Road will feature prominently, underscoring the building’s centrality and visual impact. The site is also adjacent to the Business Bay metro station, emphasising convenience and connectivity.

In context, Downtown Residences forms part of a robust real estate market supported by government initiatives such as long‑term residency schemes and golden visa programmes, along with strong investor interest. Last year, Dubai recorded AED 761 billion in real estate deals, a 20 percent year-over-year increase, while unit prices rose nearly 19 percent. However, recent analysis from Fitch warns of a potential 15 percent price correction in the face of increasing supply as new units deliver in 2025 and 2026.

Within the current landscape, several super‑tall residential towers are either in planning or under construction. For instance, the 557‑metre Burj Binghatti Jacob & Co is expected to top out in 2027. Meanwhile, the 725‑metre Burj Azizi and a host of other vertical developments are progressing. Downtown Residences will complement these, contributing to a vertical growth strategy that increasingly defines Dubai’s urban identity.

Deyaar, with a 23‑year history in the UAE real estate sector, has previously completed numerous projects across Business Bay and downtown districts. The developer anticipates concluding the current series of launches with AED 4 billion in sales for 2025.

Compared with the tallest completed residential towers in Dubai, such as Marina 101 and Princess Tower, Downtown Residences will exceed these heights, adding further prestige to the skyline. In the under‑construction category, towers like Bayz 101 and Six Senses are among peers.

Dubbed a “vertical residential community”, Downtown Residences aims to offer more than luxury living; it’s intended as a lifestyle destination combining wellness, exclusivity and high‑end design. By aligning with evolving buyer preferences—especially among high‑net‑worth and remote‑worker demographics—the development emphasises contextually relevant amenities, location and architectural prominence.

As Dubai positions itself at the forefront of global luxury real estate, Deyaar’s Downtown Residences emerges as a test case in balancing scale, innovation and market demand. With units reportedly starting from AED 1.8 million, early indicators suggest strong investor interest in the lower‑priced tiers. Simultaneously, the Royal Palace and sky‑level offerings reflect ambitions to cater to ultra‑luxury buyers.

Deyaar’s vision, articulated by both Al Qatami and Patrick Bernard Rouse, frames Downtown Residences as more than just a building—it is a calibrated response to hierarchical human needs and emerging market dynamics. By integrating connectivity, wellbeing, community and status across vertical zones, the concept attempts to redefine high‑rise living.

Dog owners across Nigeria are trimming meals and turning to homemade alternatives as soaring inflation and currency devaluation drive imported pet‑food costs up to levels equivalent to the national minimum wage. A crisis in livestock staples has now reached the country’s urban pet economy. Inflation in Nigeria has surged since May 2023, when the government removed a long-standing fuel subsidy and devalued the naira. General inflation hit nearly […]

Daily active users in the global cryptocurrency market have surged to 30.8 million, marking a 30-fold increase since early 2020 when the figure hovered around just one million. This extraordinary growth underscores a pivotal shift in digital finance adoption, driven by both mainstream institutional participation and decentralised finance innovations.

The five-year acceleration in user activity reflects a maturing market that has gradually moved from speculative volatility toward widespread utility and integrated applications. Analysts link this exponential climb not only to rising asset prices but also to expanding real-world use cases and adoption in emerging markets where crypto offers alternatives to unstable fiat currencies or limited banking access.

Between 2020 and 2021, crypto markets experienced a spike in retail investor interest as Bitcoin and Ethereum reached new price highs. But the subsequent years saw a more diversified set of contributors to active user growth. These included Layer-2 solutions that reduced transaction costs, central bank scrutiny that validated digital assets as long-term economic factors, and increased capital flows into decentralised applications that are now used for lending, trading, and payments.

The upswing has also been aided by a shift in demographics. Users between the ages of 18 and 35 continue to dominate, but there is a discernible rise in users over 50 participating in digital asset portfolios through robo-advisors and automated wealth apps. Fintech platforms have played a central role in onboarding new users, offering wallet services directly within traditional mobile banking interfaces, especially in Southeast Asia, Latin America, and Sub-Saharan Africa.

Regulatory tailwinds have also contributed to this surge. After years of ambiguity, several governments began laying out clearer frameworks for crypto usage and taxation. The European Union’s Markets in Crypto-Assets regulation, now in force, has created greater legal clarity for wallet providers and stablecoin issuers. Meanwhile, jurisdictions such as Singapore, the UAE, and Hong Kong have developed regulatory sandboxes that attract developers without compromising on compliance. The clarity around Know-Your-Customer norms and licensing requirements has encouraged institutional custodians and payment processors to enter the space, further legitimising its growth.

Daily active wallet addresses, which measure unique addresses interacting with blockchain networks, are now being driven by utility rather than speculation. Decentralised social media platforms, blockchain-based gaming, and metaverse transactions contribute heavily to user engagement. On-chain metrics show that average wallet-to-wallet transactions have grown in both frequency and diversity, indicating a broader shift from holding digital assets to actively using them.

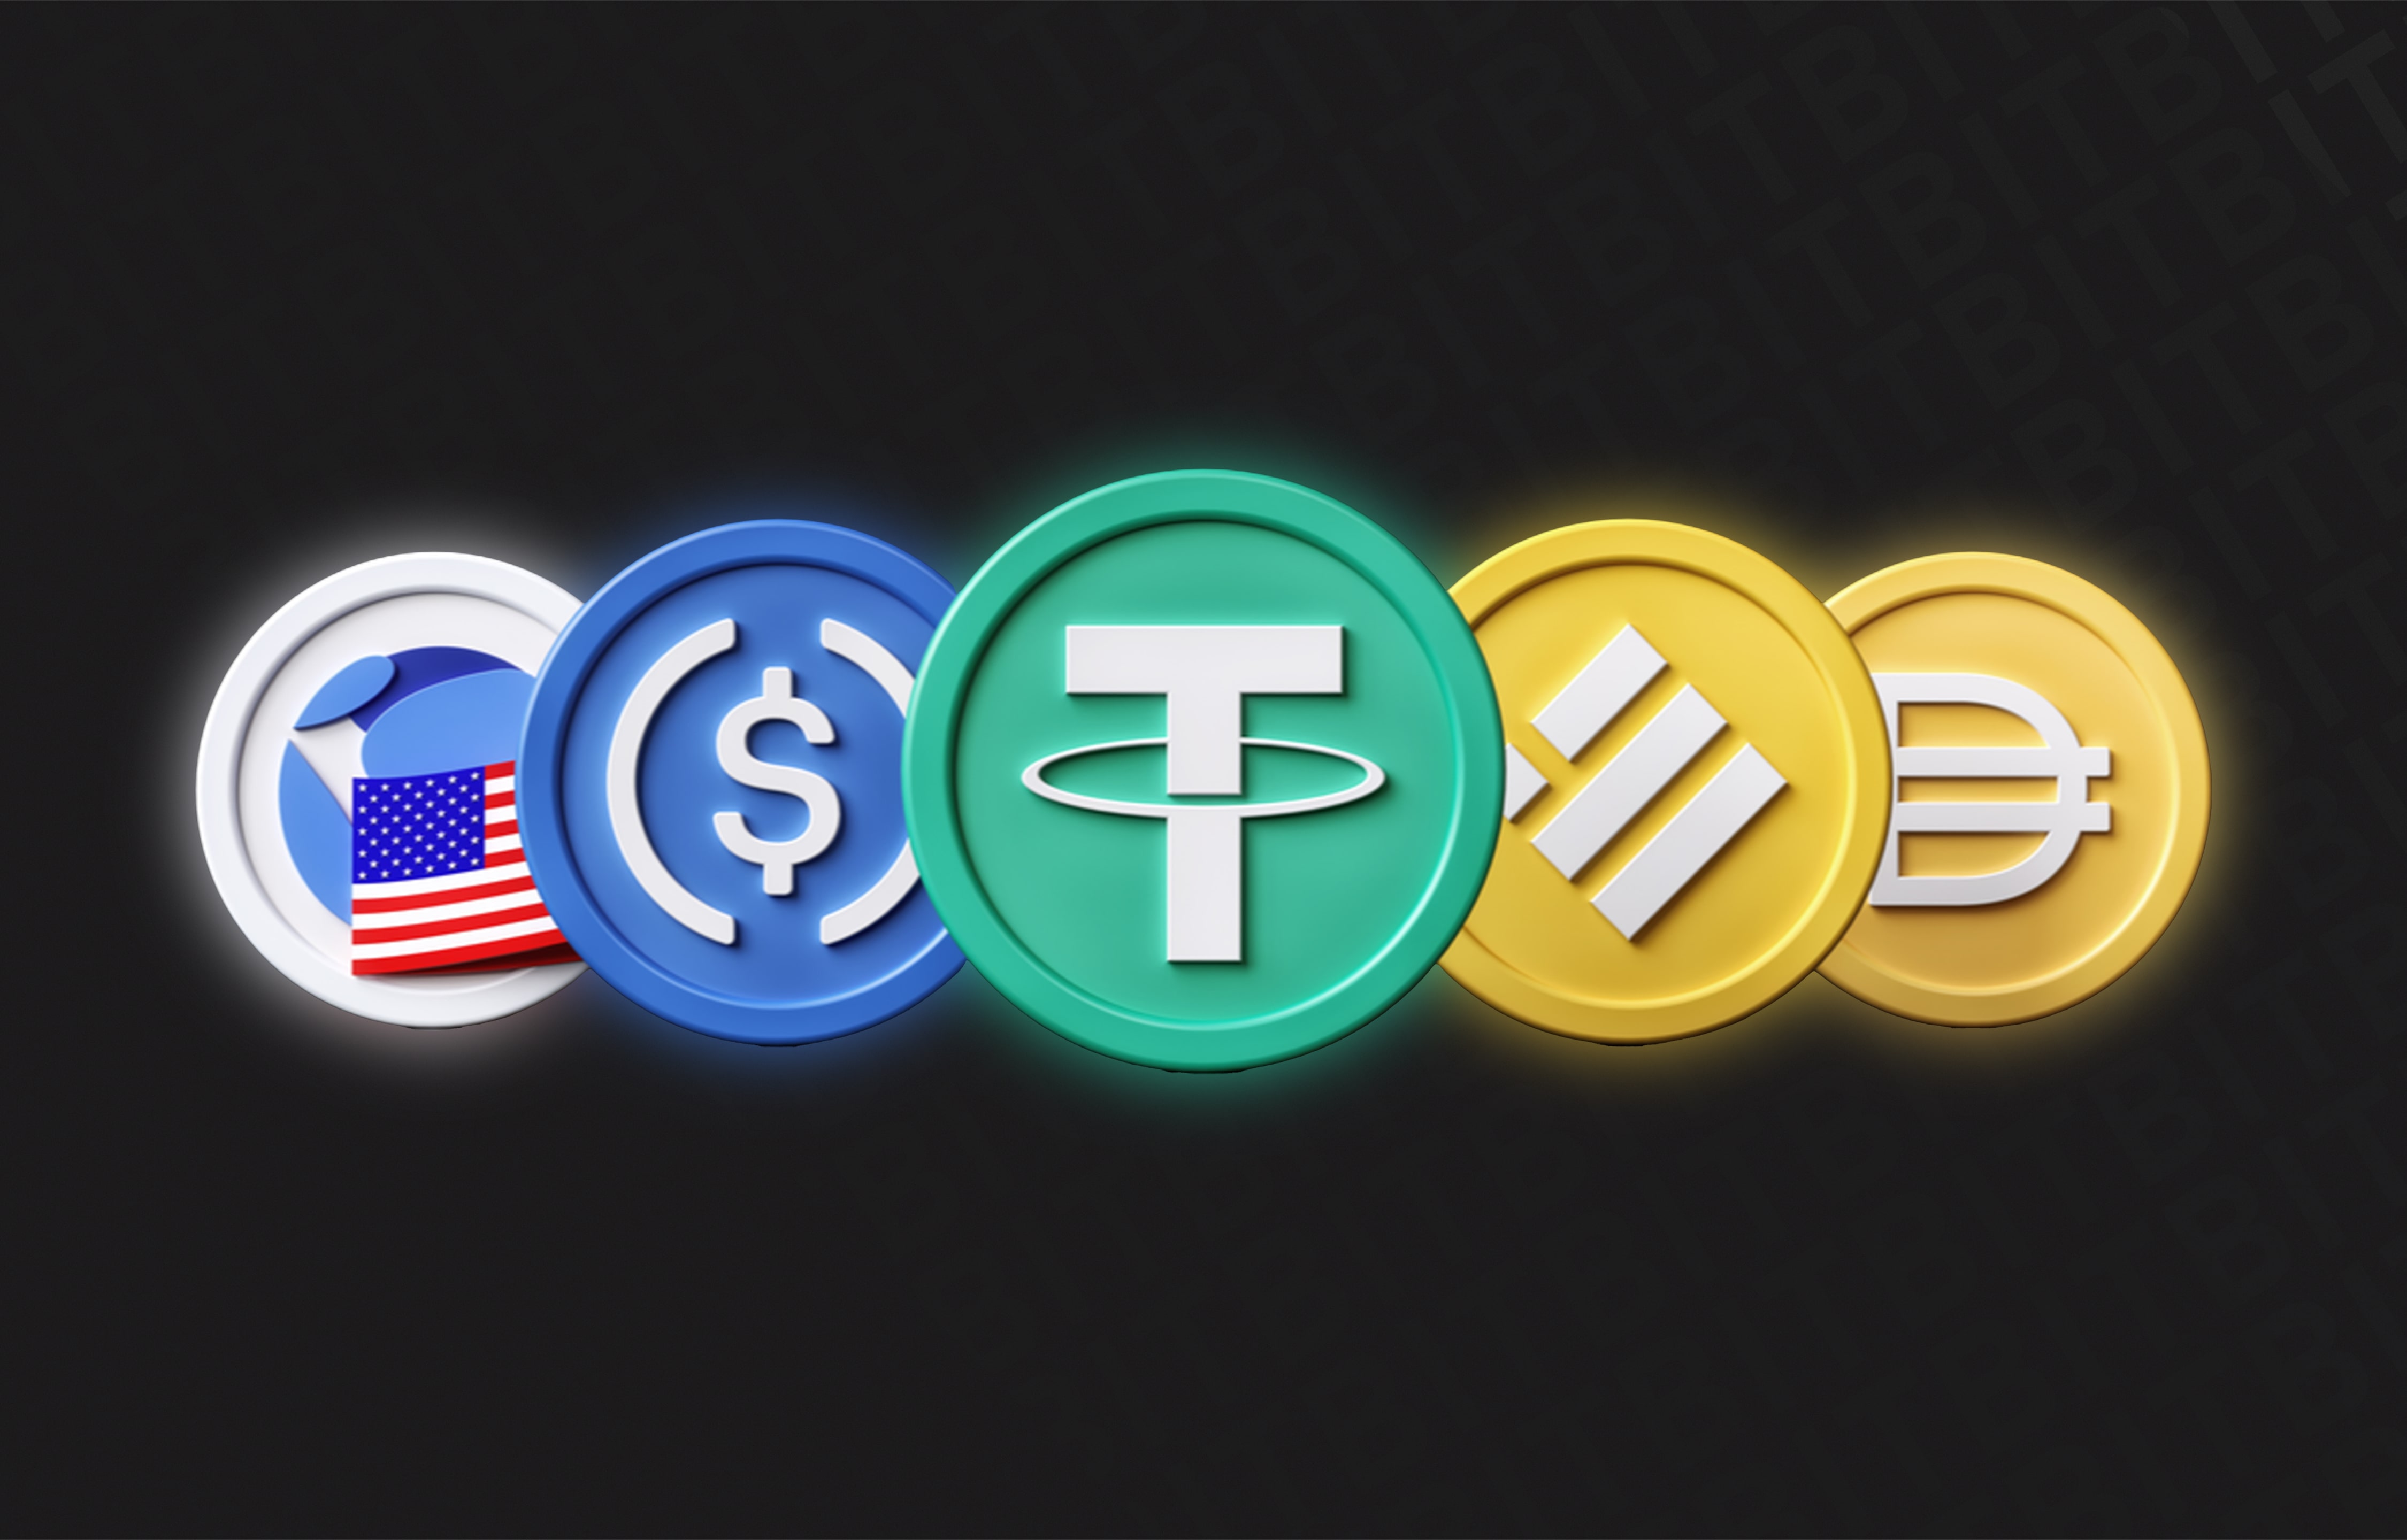
Stablecoins remain a major catalyst. With daily transaction volumes frequently surpassing those of major card networks, these tokens are increasingly used for remittances, salaries, and cross-border commerce. Businesses in Argentina, Nigeria, and the Philippines now routinely accept stablecoins to hedge against inflation and currency volatility. Dollar-pegged tokens such as USDT and USDC remain dominant, but a new wave of regionally anchored stablecoins linked to the euro, yen, and dirham are gaining traction.

This growth has coincided with new product launches by global crypto service providers. Coinbase, Binance, and OKX have all introduced wallet products tailored for mobile-first users, while decentralised apps like MetaMask and Trust Wallet have streamlined onboarding by integrating fiat-to-crypto gateways and social recovery features. Wallet-as-a-service solutions have also proliferated, allowing e-commerce platforms and loyalty programmes to integrate tokenised rewards and payments.

However, the expansion hasn’t been without setbacks. Security breaches and phishing attacks continue to pose significant threats, especially on mobile wallets lacking robust encryption or biometric safeguards. In 2024 alone, more than $600 million was reportedly lost to wallet-targeted hacks. This has forced wallet providers to enhance security protocols and increase user education around seed phrase storage and recovery mechanisms.

The surge in user activity also raises questions about scalability and environmental impact. Ethereum’s successful shift to a proof-of-stake consensus has alleviated some concerns, reducing energy consumption by over 99 percent, but congestion on other chains like Solana and BNB Smart Chain persists during peak usage periods. Developers are now turning to zero-knowledge rollups and modular chain architectures to manage the growing demand without compromising on decentralisation or throughput.

Investment in wallet infrastructure has sharply increased, with venture funding in crypto wallet startups exceeding $2.5 billion over the past year. Several firms are focusing on embedded crypto solutions that operate invisibly behind e-commerce and payment interfaces, enabling crypto usage without requiring users to understand blockchain mechanics. This backend integration has become crucial to onboarding the next 100 million users, according to fintech consultants.

On the macroeconomic front, crypto wallets are increasingly being viewed as components of digital identity. National digital currency trials in countries like Brazil and India are exploring hybrid models that link sovereign wallets to decentralised ones, potentially enabling programmable money systems that maintain user agency while complying with monetary policy.

As blockchain integration deepens across sectors, from healthcare to real estate, wallet functionality is expanding beyond currency storage. New generations of wallets offer token-gated access, voting rights in decentralised autonomous organisations, and certification for digital credentials. These features are pushing crypto adoption beyond financial speculation into everyday life.

Saudi Arabia will export about 47 million barrels of crude to China in July, marking a modest decline of one million barrels compared with June allocations. Despite the slight reduction, this remains the third consecutive month of elevated shipments to the world’s largest crude importer, underscoring Riyadh’s resurgence in securing market share. This shift follows a decision by OPEC+—a coalition of the Organisation of the Petroleum Exporting […]

Starbucks has announced price reductions averaging 5 yuan on select iced and tea‑based beverages in China, marking a significant shift in its pricing strategy within its second‑largest market. The move, effective from this Tuesday, will place some drinks at 23 yuan, aiming to broaden appeal during afternoon hours amid mounting competitive and economic pressures.

China’s coffee landscape has grown increasingly fragmented, driven by a prolonged deflationary trend and cautious consumer sentiment. Deflation persisted into its fourth month as of May, with consumer prices dipping 0.1 per cent year‑on‑year, prompting retailers across sectors to adjust pricing. Domestic chains such as Luckin Coffee, Manner Coffee and Cotti Coffee now retail Americanos for between 14–15 yuan, while JD.com and Alibaba‑affiliated delivery services can bundle drinks via promotions for as low as 2.9 yuan. Bubble‑tea giant Mixue has entered the fray with tea coffees priced at around 6.9 yuan, following a $444 million IPO in Hong Kong.

A spokesperson closely involved with Starbucks China, speaking anonymously, maintained that the adjustments are not a capitulation to a price war but rather a strategic effort to attract more afternoon foot traffic, particularly towards non‑coffee offerings like frappuccinos and tea lattes. This follows a subtle shift over recent months, where the company introduced smaller drink sizes and more digital coupons to stimulate transactions.

As of late 2024, Starbucks operates 7,685 outlets across the mainland, having added a roasting plant in Kunshan and continued store expansion. Nonetheless, slowing China growth—4.7 per cent in Q2 2024—and deflationary trends have eroded consumer confidence, with job insecurity prompting tighter spending in discretionary areas such as cafés.

Starbucks’ appeal has long rested on its “third‑place” ambience—charging premium for experience. But critics and analysts note that domestic players emphasise product innovation and affordability. Kearney’s Sherri He described the shift: “Starbucks is targeting white‑collar professionals… but broader masses opt for lower‑cost, trend‑driven products”. Indeed, Luckin now runs more than 20,000 stores nationwide, tripling Starbucks’ footprint in major urban centres.

Luckin’s resurgence—after accounting scandals and bankruptcy—has been marked by aggressive volume strategies and rapid recovery in same‑store sales, recording triple‑digit net income growth in late 2024. That firm’s continued expansion underscores the pricing threat Starbucks faces, particularly in lower‑tier cities where cost sensitivity is acute.

Analysts point to broader strategic recalibrations within Starbucks. Last week, the company reportedly explored partnerships and divestments tied to its China operations as part of a wider turnaround push. In recent financial reports, Starbucks admitted North America and China comp store performance remained under pressure, with CEO Brian Niccol pledging menu simplification and improved customer experience.

Starbucks’ pivot seems aimed at reintroducing affordability while defending its premium image. While global chains retreat from steep discounting, in China delivering price accessibility may be essential ground‑level defence. Observers will be monitoring whether afternoon footfall increases and if lower price points sustain margins amid stiff competition.

The broader market vibrates with innovation and localisation. Domestic players are accelerating menu iterations—bubble‑tea flavours, brown sugar boba lattes, coconut‑coconut variants—tailored to Gen‑Z preferences. Mixue’s model, which prioritises ingredient and equipment revenues to franchisees, allows ultra‑low pricing and rapid store proliferation—a direct challenge to Starbucks’ directly‑operated format.

Starbucks’ push into smaller Chinese towns—far beyond tier‑one cities—is another key differentiator. With a goal of opening 9,000 outlets by end‑2025, the company is banking on long‑term expansion even as urban discretionary spending decelerates. But this scale‑up entails heightened exposure to price‑led local competitors.

BANGKOK, THAILAND – Media OutReach Newswire – 10 June 2025 – Gother, a tourism service platform, operated by Search Engine Optimization, a joint venture between Beacon Venture Capital (venture arm of Kasikornbank) and Krungthai Ventures (venture arm of Krungthai Bank) is showing strong upward momentum following a 300% business growth in just seven months since launch in the past year. Aimed at upgrading its platform, Gother is […]

BlackRock’s iShares Bitcoin Trust surpassed $70 billion in assets under management on 6 June, achieving the fastest accumulation ever seen for a spot ETF—reaching the milestone in just 341 trading days. That pace outstrips the previous record held by SPDR Gold Shares, which took 1,691 days, marking a fivefold acceleration.

IBIT now holds approximately 662,707 BTC, nearly 20 per cent of the total 3.4 million bitcoins held by public and private entities, government bodies, exchanges, and decentralised finance protocols. Such concentration under BlackRock’s control is reshaping the distribution of Bitcoin supply across institutional players.

Secondary spot Bitcoin ETFs—led by Fidelity’s Wise Origin with roughly $21.3 billion AUM, and Grayscale’s GBTC at $19.3 billion—lag far behind IBIT in scale. Ark 21Shares and Bitwise report assets under $5 billion. Analysts note that IBIT’s dominance reflects not only investor appetite for regulated exposure to Bitcoin but also confidence in BlackRock’s operational strength and trust in its custody and compliance framework.

The ETF’s structural advantages lie in its cost-effective fee, integration with Coinbase Prime custody, and BlackRock’s institutional-grade infrastructure. It provides market participants with direct Bitcoin exposure without requiring them to navigate private key management or self-custody complexities.

Bitcoin’s value hierarchy has been boosted by IBIT’s growth. With total holdings just shy of 663,000 BTC, the trust exceeds erstwhile leader MicroStrategy, which held 582,000 BTC. A rising number of publicly traded companies are preparing to expand their Bitcoin treasuries. Corporate treasurers are watching IBIT’s capital inflows closely, signalling a shift in institutional allocation strategies from traditional assets into digital scarcity.

The influence of corporate buyers extends beyond small-scale investments. Michael Saylor’s MicroStrategy remains a strong presence, but other blue‑chip corporates are signalling potential acquisitions. Arkham Intelligence data indicates that incremental corporate accumulation may further redistribute Bitcoin supply, previously more diversified across governments, miners and individual holders.

IBIT’s momentum accelerated in May, posting its largest monthly inflow yet. Bloomberg reports this surge synchronised with Bitcoin trading above $108,000, hinting at institutional investors strategically buying ahead of broader market highs.

Secondary market activity reinforces the appetite for IBIT shares. In April, the ETF recorded a single‑day trading volume of $4.2 billion—with Bitcoin hovering around $91,000—underscoring its liquidity and the appetite among both retail and institutional investors.

Industry experts suggest this liquidity is a key attractor. IBIT’s trading activity consistently outpaces competitors, offering tighter spreads and reduced transaction costs, which in turn fuels further inflows.

Regulatory clarity remains pivotal. The official IBIT prospectus confirms the trust is governed by Delaware law, uses Coinbase as custodian and prime broker, and implements safeguards to align on‑chain Bitcoin with the ETF shares. This structure mitigates risks of mispricing or premium/discount discrepancies, giving institutional investors assurance. It also reveals that IBIT is not registered under the Investment Company Act of 1940, though it complies with major U.S. securities and exchange rules.

Meanwhile, BlackRock hints at international ambitions. A European equivalent to IBIT is under regulatory consideration, targeting Swiss registration under evolving EU cryptocurrency taxonomy. The success of the U.S. product strengthens its case for cross‑jurisdiction expansion.

Market analysts emphasise that the dilution of available Bitcoin supply via institutional custody may tighten free float and reduce volatility. With one entity holding a fifth of the publicly held Bitcoin, even modest inflows from public companies or IBIT could exert noticeable price effects.

A shift in supply concentration also raises systemic questions. As BlackRock and corporate treasuries secure larger holdings, the dynamics of price discovery may move away from retail and miner-driven liquidity pools. On‑chain analytics firms suggest emerging demand imbalance between supply locked in long‑term institutional wallets and tradable supply available to speculative or transactional buyers.

Critics argue that increasing centralisation challenges the decentralised ethos of Bitcoin. The risk is that a few large custodians could accrue disproportionate influence over market flows and network sentiment. Proponents counter that regulated trust models and robust custody reduce systemic risk and enhance asset legitimacy among institutional participants.

IBIT’s fee structure is also under scrutiny in comparison to competing ETFs. At 0.25 per cent, it positions itself competitively against alternatives, though slightly higher than passive gold or broad‑market ETFs. Nevertheless, institutional investors appear willing to pay a premium for regulatory certainty and deep liquidity.

Speculation is mounting around BlackRock’s next moves. The firm is reportedly exploring tokenised treasury products across other asset classes, including corporate bonds and money‑market instruments. Observers suggest that if IBIT’s performance continues, similar frameworks could be deployed for Ethereum or thematic digital‑asset baskets.

As rivals respond, competition intensifies. Fidelity’s FBTC and Grayscale’s GBTC have begun marketing enhancements and lower fees. Field analysts expect them to intensify efforts, particularly as Bitcoin continues to test and potentially surpass all‑time high prices near $112,000.


Dubai’s FIX Dessert Chocolatier confirmed it will unveil a new chocolate bar at Mall of the Emirates this Friday, June 13, launching a three‑day pop-up from 10 AM until midnight through Sunday, June 15. The brand, already famed for its pistachio‑and‑knafeh‑filled “Dubai Chocolate” bars, has withheld details on the new variant, teasing only that it draws from “childhood memories”. Shoppers will also encounter interactive games, prize giveaways and brand‑curated surprises […]

Hong Kong’s Hang Seng index climbed past the 24,000 mark, reaching heights unseen since March, fuelled by renewed optimism surrounding US-China trade discussions. Investor sentiment improved as market participants weighed the possibility of easing tensions between the two largest economies, sparking a notable rally in Hong Kong’s benchmark index. However, this upbeat mood contrasted sharply with the performance of Bitcoin, which struggled amid uncertainties over inflation dynamics and broader market volatility.

The Hang Seng’s advance reflected a growing belief that US and Chinese officials are making progress toward resolving key trade disputes. Early talks aimed at addressing tariffs, technology restrictions, and investment barriers have led investors to anticipate a thawing in one of the most consequential economic standoffs globally. The improving trade dialogue appears to be encouraging capital inflows into Hong Kong-listed shares, particularly in sectors sensitive to cross-border trade such as technology, manufacturing, and finance.

Market experts highlight that investor focus remains fixed on the trajectory of these negotiations, with any breakthroughs potentially unlocking significant value in the region’s equities. The rally also aligns with a more cautious but hopeful stance among traders that a prolonged trade conflict could ease, bolstering global economic growth prospects. Notably, blue-chip stocks led the gains, signalling confidence among institutional investors betting on recovery and expansion in the Asia-Pacific markets.

Conversely, Bitcoin’s performance diverged, as the leading cryptocurrency grappled with pressure from both macroeconomic and regulatory fronts. The digital asset has faced downward momentum partly due to investor apprehensions over persistent inflationary pressures in the United States. Inflation data remains a key focal point, as higher consumer prices could prompt the Federal Reserve to sustain or accelerate interest rate hikes, tightening liquidity conditions and dampening risk appetite in speculative assets.

Bitcoin’s volatility has also been compounded by shifting regulatory attitudes worldwide. Authorities in various jurisdictions are intensifying scrutiny of digital currencies, citing concerns over money laundering, market manipulation, and financial stability risks. Such regulatory tightening has contributed to a cautious investor approach, limiting Bitcoin’s ability to capitalize on broader risk-on sentiment seen in equities.

Analysts note that while Bitcoin has often been viewed as a potential inflation hedge, its correlation with traditional risk assets has increased, causing it to react sensitively to shifts in monetary policy and global economic uncertainty. This evolving dynamic challenges the narrative of cryptocurrencies as safe havens, complicating portfolio strategies for institutional and retail investors alike.

The Hang Seng’s rally has benefited from strong performances in technology companies listed in Hong Kong. Giants in the semiconductor and telecommunications sectors saw their share prices rise amid speculation that easing trade tensions could reduce supply chain disruptions and promote cross-border business activities. Additionally, financial stocks gained momentum as optimism grew about improving economic fundamentals and potential credit growth in the region.

Meanwhile, traders are closely monitoring upcoming US inflation reports, which could significantly influence market direction. Persistent inflation could lead the Federal Reserve to maintain a hawkish stance, thereby exerting downward pressure on risk assets including equities and cryptocurrencies. Conversely, signs of easing inflation could provide further impetus for market rallies and reduce volatility.

Hong Kong’s role as a financial gateway between China and the global economy continues to underpin investor confidence. The city’s markets are seen as a barometer for broader regional economic health, and the Hang Seng’s rise signals expectations that cross-border trade and investment flows will stabilise or improve amid diplomatic progress. This optimism is tempered by awareness of ongoing geopolitical risks, including Taiwan tensions and global supply chain uncertainties.

Bitcoin’s challenges underscore the growing complexity of the global investment landscape, where traditional and emerging asset classes are influenced by an intertwined set of economic, regulatory, and geopolitical factors. While the cryptocurrency market remains dynamic, its path forward appears increasingly contingent on external economic conditions rather than solely on technological or adoption milestones.

Stablecoins are processing roughly $33 trillion in yearly volume—around 20 times that of PayPal and three times Visa—while amassing $128 billion in U.S. Treasuries, placing these issuers among the top 20 holders of American debt and ahead of major nations such as Germany and Saudi Arabia.

Data from Andreessen Horowitz’s crypto arm shows that over 1 percent of the total U.S. dollar supply is now tokenised on blockchains. Major institutions, including Citi, project that by 2030 stablecoins could accumulate up to $3.7 trillion in Treasury holdings. While Ethereum and Tron currently underpin most of this infrastructure, emerging platforms such as Solana, Arbitrum and Base are gaining traction. Notably, on-chain data reveals that transactional activity in stablecoins appears largely decoupled from broader cryptocurrency trading volumes, indicative of growing real-world adoption. Today, these assets enable sub-second, sub-cent payments—positioning them as serious contenders to onboard the next billion users into the crypto economy.

Market analysts warn that growing stablecoin-backed Treasury holdings may shift demand dynamics for U.S. government debt. One study from academia found that by the end of the first quarter of 2025, Tether held roughly $98.5 billion in Treasury bills—equating to 1.6 percent of total outstanding bills. The research estimates that this level of demand has directly driven down one-month Treasury yields by approximately 24 basis points, indicating that stablecoin issuance is already influencing funding costs and potentially easing liquidity pressures.

Coinciding with this shift is a legislative push in Washington. A bill nearing Congressional approval would require issuers to fully back stablecoins with liquid assets, such as U.S. dollars and short-term Treasuries, and mandate monthly disclosures. Proponents suggest such regulation would reinforce investor trust, legitimize the sector and bolster U.S. debt demand. According to Reuters, Tether and Circle already hold a combined $166 billion in Treasuries—amounts that may increase further under binding legal frameworks.

Financial authorities have offered mixed views. Moody’s warns that large-scale liquidation driven by plunging confidence in stablecoin issuers could destabilise Treasury prices and spill over into broader fixed-income markets. Conversely, policymakers hope that expanded stablecoin activity could facilitate smoother funding for the Treasury, especially if issuers pivot toward demand for short-term debt like bills.

Macro strategies are duly noted. Vanguard’s rates chief suggests that sustained demand from digital currency custodians might spur the Treasury to favour issuing bills over long-term bonds, which could rebalance maturity profiles. Meanwhile, Bitwise’s investment head argues that this growing digital demand could reinforce the dollar’s position as the global reserve currency.

Infrastructure diversification within stablecoins is evolving. Ethereum and Tron continue to dominate, but high-throughput chains like Solana, Arbitrum and Google-backed Base are attracting developers and users aiming to benefit from faster, cheaper payments. The presence of real-world transactions—such as merchant and remittance use cases—underscores that stablecoins are transcending crypto-speculative flows, with sub-cent fees and near-instant settlement now commonplace features.

Emerging risks centre on financial-system vulnerability. The Treasury Borrowing Advisory Committee cautioned that a significant diversion of deposits into stablecoins could dampen demand for Treasuries and potentially curb lending by commercial banks. Money-market managers remain vigilant, with some estimating that stablecoins must scale further before triggering systemic instability.

Proponents counter that regulated stablecoins may alleviate pressures in the Treasury issuance process, with digital platforms absorbing demand in lieu of traditional buyers. Early legislative frameworks could incentivise these issuers to prefer bills over longer-duration instruments, helping to smooth fiscal financing.

Stablecoins are redefining the interface between digital currency networks and the time‑tested Treasury market, leaving policymakers to navigate a complex balance between innovation, stability and monetary control.

OPEC+ has escalated production quotas by roughly one million barrels per day from March to June, aiming to reactivate idled capacity, yet actual output across the group remains flat, according to data from Morgan Stanley analysts led by Martijn Rats. Saudi Arabia in particular shows no detectable uptick, underscoring a lag between policy shifts and market reality.

The decision to accelerate quota rollbacks follows sustained cuts totalling around 2.2 million b/d, initiated in early 2023 to support prices. With non‑OPEC supply growing and global demand weakening, the efficacy of supply restraint has waned, prompting OPEC+ to pivot back to restoring output gradually. Despite headline quota increases of approximately 137,000 b/d per month since April, actual deliveries appear limited.

Underlying structural factors are at play. Several members—most notably Kazakhstan and Iraq—have reportedly exceeded their quotas, diluting the announced gains. Saudi Arabia, with substantial spare capacity, stands out as the most capable contributor to any genuine rise in output. However, its contribution remains muted so far. Analysts suggest this reflects a strategic choice to reclaim market share rather than an immediate scale-up.

Analysts at Morgan Stanley project modest growth: between June and September, OPEC+ core members may add around 420,000 b/d—approximately half of which could originate from Saudi Arabia. Even then, actual production may fall well short of quotas, with implementation challenges persisting.

This gap between policy and output carries market implications. With more supply forecast, Morgan Stanley predicts a surplus of roughly 800,000 b/d in Q4 and 1.5–2.0 million b/d in early 2026, pressuring Brent crude prices down toward the mid‑$50s. Currently, Brent trades near $66 per barrel—11% below its level at the start of the year.

In parallel, geopolitical friction between Saudi Arabia and Russia surfaced during policy talks. Riyadh favoured a more aggressive quota rollback, while Moscow, alongside Oman and Algeria, urged caution amid worries about demand resilience. The compromise settled on another 411,000 b/d increase for July, a repetition of earlier monthly hikes.

Markets initially responded positively: oil prices climbed 3–4% following the July quota announcement, with Brent touching the mid‑$60s. That rebound, however, reflected relief over continuity rather than enthusiasm over fresh supply. Wildfires in Canada and refinery maintenance cycles were also cited as supporting factors.

Across OPEC+, reliability of quotas remains a concern. While some members exceed limits, others—constrained by infrastructure or investment—may struggle to ramp up. Saudi Arabia’s spare capacity remains central, but constraints on countries like Russia complicate the outlook even as OPEC+ restores cut volumes faster than planned.

Meanwhile, non‑OPEC supply continues to grow, particularly in the U.S., Canada, Guyana and Brazil—with forecast increases of about 1.1 million b/d in 2025. That expansion alone could outpace expected global demand growth of 800,000 b/d, risking oversupply irrespective of OPEC+ decisions.

With a full quota restoration now likely by September 2025—months ahead of the original schedule—and non‑OPEC volumes outweighing demand growth, the market faces a mounting supply glut heading into late 2025 and 2026. Analysts caution that idled capacity may remain untouched for months beyond official quotas, delaying meaningful production gains.

As OPEC+ enters this intensified phase of quota reopening, its central challenge remains execution rather than announcement. High-profile policy shifts are yet to translate into barrels at market, and the divergence between targets and reality could widen over the coming quarters. Market players are now watching whether Saudi Arabia leads by example or the rhetoric fades before the pumps do.

Maein Khalid Since the pandemic, IPO activity across GCC capital markets has surged – offering a sharp contrast to the stop-start pace on New York’s Nasdaq and the near standstill on London’s LSE. Nearly 300 IPOs have raised around $50 billion across the Gulf since 2021. Below I outline six key macro themes shaping this post-Covid IPO boom in the GCC. First, contrary to expectations, the number, […]

The 2025 MICHELIN Guide selection in Vietnam features a record 181 establishments: 9 One MICHELIN Star (1 new and 1 promoted), 2 MICHELIN Green Star (1 new), 63 Bib Gourmand (9 new), and 109 MICHELIN Selected (14 new). CieL (Ho Chi Minh City) directly debuts with One MICHELIN Star, while Coco Dining (Ho Chi Minh City) is promoted to One MICHELIN Star. The new MICHELIN Green Star […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA