News related to
Saudi

Four sources confirm that Saudi Aramco is negotiating to acquire 2 million tonnes per annum of liquefied natural gas from Commonwealth LNG’s planned Cameron, Louisiana export facility. This addition would bring Commonwealth closer to its ambition of locking in 8 mtpa from its total 9.5 mtpa capacity, enhancing its commercial viability and drawing it nearer to a final investment decision by year‑end. Commonwealth LNG, backed by private equity firm Kimmeridge, […]

MENA region investment banking fees declined 2 per cent year‑on‑year in the first half of 2025, falling to US$773.7 million, the third‑highest H1 tally since 2000, according to London Stock Exchange Group’s Deals Intelligence data. The dip occurred amid an environment of oil‑price volatility, geopolitical fragmentation and escalating global trade tensions. Debt capital markets underwriting emerged as the growth engine, with related fees rising 20 per cent to US$278.9 million. However, […]

Senior officials from Saudi Arabia, the United Arab Emirates and Kuwait have defended the August production boost of 548,000 barrels per day, stating that global markets are absorbing the extra supply without piling up inventories. UAE Energy Minister Suhail al‑Mazrouei told delegates in Vienna that inventories have remained stable despite the accelerated output increases, reflecting genuine consumption growth. Kuwait Petroleum Corp. echoed this view, with its CEO Sheikh Nawaf Al‑Sabah noting strong demand from Asian customers and signalling a tighter market than widely perceived.

Oil markets displayed resilience as Brent crude climbed above $70 a barrel, recovering from an initial dip following the OPEC+ announcement. Analysts cite robust summer travel demand, Middle East geopolitical strains—such as intermittent Houthi attacks in the Red Sea—and tighter fuel product cracks as underpinning near‑term market firmness. The supply surge, although substantial, has not yet triggered signs of oversupply. OECD stock levels remain flat, while US Strategic Petroleum Reserve levels stay well below maximum, pointing to a balanced market setup and sustained product demand.

The OPEC+ decision marks an acceleration of a reversal programme that began in April with a modest 138,000 bpd increase, followed by three successive monthly hikes of 411,000 bpd. The latest announcement represents a strategic shift: rather than merely unwinding voluntary cuts, producers are intent on reclaiming market share and anchoring long-term stability. Saudi Arabia, which had shouldered most of the original production curbs, is now pushing ahead to restore output levels much faster than previously scheduled.

UAE officials emphasise fundamentals over headlines, asserting that additional barrels were essential to maintain equilibrium rather than depress prices. “We haven’t seen a major buildup in inventories, which means the market needed those barrels,” al‑Mazrouei said, stressing the need for steady investment in oil infrastructure. Kuwait’s Sheikh Nawaf further highlighted sustained demand growth—particularly in Asia—estimating additional global need of up to 1.3 million bpd over the year and pointing to record-high shipments from his country in June.

Supporting evidence emerges in price trend analysis. Despite the supply increase, Brent crude closed near $69–$70 per barrel, with West Texas Intermediate at approximately $68. Reuters reported a 1 per cent rise in oil prices shortly after the announcement, driven by stronger-than-expected demand signals and a dip in US production projections. Market commentary suggests that the anticipated supply surplus may not materialise until later in the year, allowing current price support to persist.

However, concern is building among forecasters regarding the risk of supply outpacing demand in the months ahead. Analysts at ING and Bloomberg caution that cumulative increases—including a potential similar rise in September—could tilt the market towards surplus by winter. Goldman Sachs predicts Brent could drop to an average of $59 in the fourth quarter if these trendlines hold. Such projections underscore the delicate balance between stabilising markets today and sowing the seeds of tomorrow’s oversupply.

Geopolitical factors continue to sway market sentiment. Renewed attacks by Houthi forces on shipping lanes in the Red Sea have boosted risk premiums and contributed to diverging regional price dynamics. In conjunction with potential US tariffs on trade partners, these developments inject layers of complexity into demand forecasts and shipping routes. Meanwhile, softer oil output projections from US shale producers, prompted by lower prices this year, have lent additional upward momentum to benchmarks.

Central to OPEC+ strategy is ensuring investment resilience in producing countries. UAE highlighted underinvestment concerns, warning that deferred spending could undermine long-term supply stability. The August lift, they argue, responds to both short-term demand and the need to signal commitment to investors. Kuwait pointed to customer outreach as evidence of healthy demand and stressed its competitive edge in terms of low-cost, lower-carbon intensity oil—a differentiator in markets such as China, Japan and South Korea.

Market analysts remain split on the outlook. Enverus Intelligence Research recently contended that prevailing data does not support a bearish narrative, noting flat stock levels in OECD countries, strong seasonal consumption, and resilient cracks. By contrast, energy consultancy FGE flagged the limitations of ramping up production, citing member compliance and infrastructure constraints that may prevent full implementation of quotas—particularly in Iraq and Kazakhstan.

Suhail bin Mohammed Al Mazrouei, Minister of Energy and Infrastructure, reaffirmed the UAE’s full backing for OPEC+ mechanisms, underlining the nation’s commitment to sustaining equilibrium in global oil markets through capacity expansion and coordinated policy.

At the 9th OPEC International Seminar in Vienna on 9 July, Al Mazrouei praised OPEC+ for its collective decision‑making model, which he said ensures production responds to actual market demand rather than price speculation. He noted that the UAE’s strategic investments in expanding production capacity reflect a readiness to release additional oil when consumption trends warrant, providing a stabilising buffer to global supply. The minister highlighted that this expansion aligns with prudent leadership foresight aimed at reinforcing market resilience.

He emphasised that there has been no substantial rise in inventories despite several months of gradual production increases. “Even with the increases…we haven’t seen a major buildup in inventories, which means the market needed those barrels,” he stated. This observation supports broader OPEC+ data showing that successive monthly output increments have been absorbed by demand, a trend that the UAE believes underlines the rationality behind its expanded quota.

Since April, OPEC+ has reversed approximately 2.17 million barrels per day of voluntary output cuts via a phased rollout: 138,000 bpd in April, then 411,000 bpd in each of May, June and July, followed by a proposed 548,000 bpd increase for August – a move reflecting growing market confidence. Notably, the UAE is set to complete a 300,000 bpd quota increase by September, a benchmark reached ahead of the original 2026 timeline as OPEC+ expedited its capacity hike schedule.

Analysts suggest that such robust production gains could recover roughly 2.5 per cent of global demand by September. Al Mazrouei remarked that the UAE’s investments will strengthen its role within OPEC+ and that once additional capacity comes online, it will serve as a crucial stabilising factor during demand shifts.

He further argued that focusing solely on oil price levels is insufficient. Rather, OPEC+ aims to strike a sustainable balance that encourages long‑term investment. “We need the price to be right for investments to happen,” he said, warning of the consequences of underinvestment across producers.

Current market dynamics appear to confirm this approach: data from mid‑June and early July indicate that inventories across OECD nations remained stable despite the production uptick, confirming demand absorption remains robust. That observation, Al Mazrouei suggested, validates the pace of OPEC+ supply restoration and diminishes concern about a looming oversupply.

While output is increasing, policy is cautious. The Group of Eight core OPEC+ members—Saudi Arabia, Russia, UAE, Kuwait, Oman, Iraq, Kazakhstan and Algeria—are proceeding in measured increments. Al Mazrouei underscored that OPEC+ continues to meet monthly via ministerial and committee reviews, carefully calibrating production relative to shifting market fundamentals.

Beyond ensuring balance, the UAE’s production capacity expansion also carries strategic benefits. Having secured a higher individual quota, the country aims to restore and extend its market share. This reinforcement was acknowledged by external observers, including Richard Bronze of Energy Aspects, who noted “the UAE is benefiting from this speeding up of the quota increases” within a context of broader OPEC+ output acceleration.

Despite concerns about slowing economies in key importers, including China, and rising US trade tensions, OPEC+ retains a cautiously optimistic outlook. Prices in July experienced modest one‑per‑cent gains near $69 per barrel following the announcement of the August supply increase—an indicator that demand continues to absorb the additional volumes.

Nevertheless, OPEC+ remains vigilant about macroeconomic risks. Commentators have warned that demand softness later this year, driven by uncertainties in global growth and trade policies, could pressurise prices. Al Mazrouei echoed that view, stressing that short‑term supply increases must be accompanied by stable investment in oil infrastructure to prevent future shortages.

Persistent coordinated production strategy is a central theme from the Vienna seminar. Ministers emphasised OPEC+’s response to shifting fundamentals rather than geopolitical or speculative impulses. With the group moving to complete the unwind of emergency cuts, markets will closely monitor whether global demand continues to match supply advances.


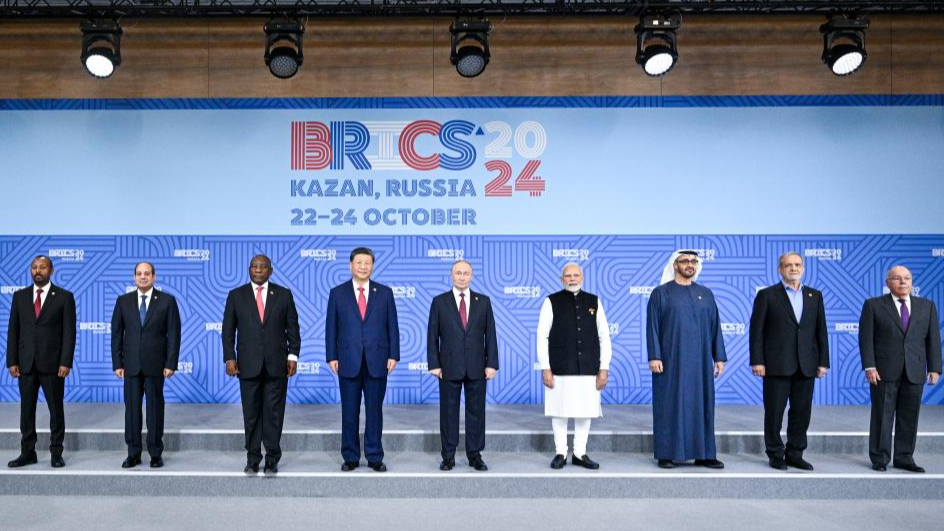
XI’s BICKS NO-SHOW: STRATEGIC SHIFT OR SILENT WARNING? CHINESE SYMBOLISM ON CONFIDENCE IN FULL PLAY M A Hossain In the realm of global politics, symbolism matters almost as much as substance. President Xi Jinping of China has decided not to attend this year’s BRICS summit which will be held in Rio de Janeiro. This is the first time President Xi will not be at the summit since […]

Dubai’s ultra‑luxury real estate market surged in April to June 2025, with transactions for homes priced above $10 million reaching US $2.6 billion, a 37 % rise from the previous quarter and a 63 % increase year‑on‑year, according to London‑based researcher Knight Frank. The emirate recorded 143 such deals in Q2, up from fewer in Q2 2024, underscoring its dominance in the global super‑prime segment. Palm Jumeirah held its status as the top destination […]

Dubai‑based hospitality firm Tashas Group is entering a rapid new phase of expansion across the Middle East and South Africa, with founder Natasha Sideris spearheading a strategy that balances boutique charm with accelerated growth. Operating 40 venues in five countries—including 18 in South Africa, 17 across the UAE, three in Saudi Arabia, and single locations in Bahrain and the UK—the group plans to open a further 15 […]

Advertisements

Iran has achieved its highest energy output in nearly half a century, as crude production and exports continue expanding despite escalating tensions and Western sanctions. In 2024, total oil output—including crude and gas liquids—reached approximately 5.1 million barrels per day, marking levels unseen since before 1978. Indicators from the first half of 2025 signal further growth, reinforcing Tehran’s stance that its energy sector remains resilient even under pressure.

China remains the principal destination for Iranian crude. According to Vortexa and Kpler data, Beijing imported an average of 1.4 million bpd of Iranian crude and condensate during the first half of 2025. In June alone, Chinese imports surged to a record 1.8 million bpd, exploiting floating storage reserves accumulated previously.

Despite U. S. legal restrictions, these volumes endure through intricate shipping methods and discounts. As of June, Iranian crude was being sold to China at discounts of $3.30–$3.50 per barrel below Brent—the widest spread since 2023—partly triggered by weak demand from independent Chinese “teapot” refineries and additional U. S. sanctions on mid-tier processing firms in Shandong province. Refineries such as these have cut utilisation rates to around 51 per cent, down from 64 per cent last year.

Iran’s export capacity has been safeguarded by infrastructural alternatives designed to bypass the Strait of Hormuz. The Goreh‑Jask pipeline and Jask terminal—capable of exporting around 300,000 bpd—offer strategic flexibility, although actual utilisation fell to under 70,000 bpd in late 2024. Elsewhere, Saudi Arabia and the UAE have also enhanced their own bypass routes through the Strait to mitigate risk.

Nonetheless, current events pose fresh challenges. Israeli strikes in June damaged parts of oil infrastructure near Tehran and affected the South Pars gas field—responsible for up to 700,000 bpd of condensate. Exports from key terminals such as Kharg Island briefly dropped below 120,000 bpd from a weekly average of 1.7 million bpd. However, Iran manages significant stockpiles—approximately 27.5 million barrels afloat—that can sustain exports for weeks.

Domestic dynamics complicate this energy story further. Iran’s gasoline consumption has outpaced refining capacity by nearly 15–20 per cent since late 2024, triggering reliance on reserves and imports to fill shortfalls. Peak summer demand reached unprecedented levels, surpassing 143 million litres in a single day. Panic-buying followed some military strikes, exposing strains in planning and supply.

Iran’s global energy standing aligns with broader market projections. The International Energy Agency forecasts that global oil supply will exceed demand in 2025 by around 1.8 million bpd, a backdrop that may soften impacts from Iranian output. At the same time, discussions in Washington about lifting U. S. sanctions have raised concerns in Beijing, particularly for its fragmented independent refining sector. Analysts warn that a sudden lifting of sanctions could flood global markets—with an additional 500,000 bpd of Iranian oil—and undercut smaller Chinese players by crushing their margins.

Iran’s energy strategy shows calculated resilience. While nuclear tensions invite military risks, the oil ministry appears intent on diversifying markets, expanding infrastructure, and leveraging geopolitical leverage. Iran Daily reported that production comprised 4.3 million bpd of crude plus around 0.7 million bpd of other liquids in 2024. Analysts advocate that increased domestic use, ageing facilities, and investment gaps could temper the pace of future gains unless Tehran secures long-term funding and technical partnerships.

Observers note the inherent paradox: Iran continues ramping production even as global energy security faces renewed uncertainty. Control over chokepoints such as the Strait of Hormuz remains central. Although no full closure has occurred—the Iranian parliament proposed closure in late June pending council approval—the symbolic threat alone underlines Tehran’s strategic positioning. Global markets, buoyed by inventories and diversified routes, have so far absorbed the shock. Yet any escalation could rapidly unsettle thresholds.

By Nantoo Banerjee It is difficult to believe that India, the world’s fourth largest economy by gross domestic product (GDP) and a major military power, ranks below even the tiny states of Kuwait and Greece when it comes to defence spending as a percentage of GDP. Considering the tricky geo-political situation in the south Asian […]

Dubai’s Roads and Transport Authority has formalised a Memorandum of Understanding with Pony. ai to commence pilot trials of self‑driving vehicles across the emirate later this year, laying the foundation for a fully driverless commercial service by 2026. The agreement marks a pivotal milestone in Dubai’s Smart Self‑Driving Transport Strategy, which aims to convert a quarter of the city’s journey volume into autonomous mobility by 2030. Senior […]

OPEC+ has opted to raise oil production by approximately 548,000 barrels per day in August, marking a sharp departure from earlier plans and surprising markets worldwide. The move, confirmed in a brief video conference, is projected to accumulate a surplus towards the close of the year, potentially eroding revenues for both OPEC members and higher-cost producers, including US shale firms.

With Brent crude prices slipping over 1% to around $67.50 and West Texas Intermediate falling to the mid‑$65 range, the group’s decision has already begun to ripple through markets. The scale of the increase is unprecedented compared to prior months—more than 130% larger than April’s hike and substantially above the 411,000 bpd rise earlier this summer.

Leaders within OPEC+ signalled that this shift reflects a strategic pivot: from defending elevated prices to asserting market share. Saudi Arabia, the group’s dominant force, spearheaded the increase, while also raising premiums for Arab Light crude sold to Asian markets—a move widely interpreted as a signal of confidence in near-term demand.

Analysts emphasise that current market structure is supportive of absorbing this surge. UBS’s Giovanni Staunovo remarked that “the oil market remains tight, suggesting it can absorb additional barrels,” though he cautioned about potential headwinds from macroeconomic uncertainties and lingering trade tensions in the next 6–12 months. Similarly, Reuters reporting notes that the decision followed assessments of low inventories and healthy economic indicators.

US President Donald Trump, whose administration has repeatedly lobbied for lower fuel costs domestically, is widely seen as a direct beneficiary of this policy. OPEC+ officials framed the increase as responsive to US pressure, with Saudi Arabia effectively stepping into a balancing role ahead of diplomatic visits.

Nevertheless, market watchers warn of mounting risks. RBC Capital projects that around 80% of the voluntary cuts—a total of 2.2 million bpd—will be reversed by September, hinting at oversupply. Financial institutions such as Morgan Stanley anticipate Brent could slide below $60 by early 2026, while ING and Barclays have also trimmed their forecasts in response to expanding inventories.

Geopolitical variables add further complexity. Though Middle Eastern tensions have eased since the brief flare‑up between Israel and Iran, any resurgence in conflict could inject volatility into the supply outlook. Moreover, internal cohesion within OPEC+ remains fragile, with nations such as Kazakhstan and Iraq reportedly exceeding quotas in recent months.

US domestic production continues its ascent, as data shows output from shale and other sources has hit record levels—adding to potential global gluts. The prospect of elevated US tariffs and slowing economic momentum could further suppress demand, amplifying price pressures.

Even so, OPEC+ remains optimistic in the short run. Saudi Arabia’s decision to lift regional premiums and analysts’ assessments of supportive market conditions reinforce this stance.

As this enlarged supply enters the market, price-sensitive producers such as US shale operators may face tighter margins. Global capitals will closely follow whether OPEC+ sustains this production path or retreats in the face of a deepening surplus.

Finance ministers from the BRICS nations have pressed the International Monetary Fund to adopt sweeping reforms that would recalibrate its governance and better represent developing economies. They jointly advocated for a modernised quota formula, increased voting power for emerging and low-income countries, and the installation of a merit-based leadership system, rather than the customary European-led management. Meeting in Rio de Janeiro ahead of the BRICS summit, ministers […]

Abu Dhabi Securities Exchange has opened the pricing stage for the first blockchain-based digital bond in the Middle East and North Africa, issued by First Abu Dhabi Bank and powered by HSBC Orion, marking a significant leap in regional capital market innovation. Global investors will be able to participate through accounts at the Central Moneymarkets Unit in Hong Kong, Euroclear, Clearstream or via HSBC Orion, either directly or through […]

Dubai’s Knowledge and Human Development Authority has confirmed that three esteemed international institutions—the Indian Institute of Management Ahmedabad, the American University of Beirut, and Saudi Arabia’s Fakeeh College for Medical Sciences—will launch branch campuses in the emirate for the 2025–26 academic year. This move aligns with Dubai’s strategic Education 33 and broader Dubai Economic Agenda D33, designed to enhance its status as a global education hub.

The Indian Institute of Management Ahmedabad is renowned for its Business and Management programme, currently ranked 27th globally by the QS World University Rankings by subject. The American University of Beirut holds a position of 237th in the overall QS World University Rankings. Fakeeh College for Medical Sciences brings specialised strength in health and medical education to Dubai’s portfolio.

Dr Wafi Dawood, CEO of KHDA’s Strategic Development Sector, emphasised that the initiative “reflects the emirate’s international stature” and aligns with goals to enhance graduate competitiveness, boost educational tourism ten-fold by 2033, broaden Emirati workforce integration, and bolster economic diversification. The strategy also aims to see international students making up 50 per cent of Dubai’s higher education population by 2033, contributing an estimated AED 5.6 billion to the sector’s GDP.

Dubai’s higher education ecosystem already includes 41 private international providers—37 of which are branch campuses—including the University of Manchester Dubai and University of Birmingham Dubai, whose home institutions rank 35th and 76th respectively in QS 2026. Curtin University Dubai and University of Wollongong in Dubai also feature within the top 200 global rankings.

The emirate recorded a 20 per cent rise in total private university enrolment for 2024–25, with international students growing by 29 per cent to reach over 42,000 across more than 700 programmes. This marks the highest student population to date in Dubai’s sector.

A broader pipeline is in place, with several other globally ranked institutions currently in advanced discussions with KHDA to establish Dubai campuses. The initiative supports Dubai’s ambition to position itself among the world’s top ten cities for university education by 2033.

Dubai International Academic City, the emirate’s dedicated higher education zone, accommodates around 27,500 students across 27 colleges and three innovation centres, offering over 500 programmes. Many of the new branch campuses are expected to be located within DIAC or Dubai Knowledge Park, reinforcing the emirate’s capacity for transnational education.

Amid growing demand, student housing projects have expanded to meet the needs of a diverse population representing more than 150 nationalities. Dubai’s education authorities have also prioritised research collaboration and academic innovation through cross-border partnerships, consistent with KHDA’s quality framework.

A record net outflow of 16,500 high-net-worth individuals is set to leave the UK in 2025, marking the largest wealth exodus recorded globally. This trend, stemming from major shifts in tax policy and visa regulations, signals a turning point in the UK’s appeal to the global rich. High earners are relocating in large numbers in response to the scrapping of the non-domicile status in favour of a […]

Amazon has unveiled a new mobile‑only shopping section called Bazaar within its Amazon. ae app in the UAE, delivering value‑focused products across fashion, home and lifestyle categories. Launching initially in beta for select users, the platform offers items priced mostly under AED 25, with some starting at just AED 4, alongside tiered savings, fast delivery, and a 15‑day returns policy.

Stefano Martinelli, Vice‑President of Amazon MENA, said Bazaar is meant to be “fun and effortless to browse”, offering the trusted reliability of Amazon combined with surprising value. A launch‑month promotion grants shoppers a 25 per cent discount across all Bazaar purchases in July.

Accessible via the “Bazaar” icon in the Amazon. ae app or by searching “Bazaar”, the platform also supports browsing on mobile web at amazon. ae/bazaar. Desktop users must scan a QR code in the browser to open the feature within the app.

Bazaar has its own search, cart and checkout system, distinct from the main Amazon experience. The interface is vibrant and purpose‑built for quick deal discovery. The platform integrates reviews and star ratings to aid user decisions.

Delivery is standard across Amazon Bazaar accounts: orders above AED 90 qualify for free shipping and typically arrive within 6–12 days. Returns are free within 15 days for most products.

Beyond initial price advantage, Bazaar encourages bulk purchases with automatic discounts: 5 per cent off orders over AED 150, and 10 per cent off for orders over AED 300. Combined with the launch‑month 25 per cent promotion, savings can accumulate significantly.

In the UAE’s booming e‑commerce environment—forecast to exceed US$ 13.8 billion by 2029—Bazaar positions Amazon to capture more bargain‑seeking consumers, complementing existing daily‑need offerings.

Dharmesh Mehta, Vice‑President at Amazon, referred to the local variant as Amazon Bazaa r or “Amazon Haul” as in other markets, noting its alignment with prior launches in the US, UK, Germany and Saudi Arabia. Gulf Business, Khaleej Times, What’s On, Times of India and Arabian Business all report that Bazaar has launched in the UAE over the past week, emphasising its mobile‑first approach and bargain pricing.

Analysts say the platform could strengthen Amazon’s value proposition in the region and give competitors like Noon, Carrefour, and Mumzworld a run for their money in the low‑cost segment. Bazaar’s playful app interface—especially its “crazy‑low” deals and under‑AED 25 “super savers” sections—appeals to price‑sensitive shoppers.

By Nitya Chakraborty On the eve of the 17th BRICS Summit scheduled at Rio de Janeiro in Brazil on July 6 and 7, the ongoing discussions among the senior officials of the member countries for the preparation of the draft joint declaration from the Summit, are showing big divergence of views on the two major […]

Global tourism is projected to reach 30 billion trips by 2034 and contribute $16 trillion to world GDP, growing 1.5 times faster than the global economy, according to the World Economic Forum’s latest report. Amid this surge, Saudi Arabia is emerging as a pivotal force, ranking the second fastest-growing tourism destination and leading global investments in innovation, infrastructure, and sustainability The WEF report, Travel and Tourism at a Turning […]

Saudi energy giant Aramco is preparing to divest up to five gas-fired power plants as part of a broader strategic shift aimed at unlocking billions of dollars to bolster state revenues and maintain fiscal discipline amid softening global oil prices. The proposed sale, focused on gas-based plants supporting key refinery operations, is expected to yield approximately $4 billion, according to individuals familiar with the internal deliberations. These […]

A coalition of eight OPEC+ nations is preparing to approve another increase in oil production for August, locking in a 411,000 barrels‑per‑day boost during their meeting on Saturday. The group—comprising Saudi Arabia, Russia, the UAE, Kuwait, Oman, Iraq, Kazakhstan and Algeria—has steadily wound back earlier cuts, reversing a 2.2 million bpd reduction begun in April.

Market analysts note that this would mark the fourth straight monthly escalation, totaling around 1.78 million bpd so far this year—equivalent to more than 1.5 per cent of global oil consumption. While the group has repeatedly implemented these increases, actual output has varied, as some members still clamp down to make up for past quota overshoots.

A shift ahead of schedule

OPEC+ fast‑tracked this weekend’s gathering by one day, underscoring its urgency to reclaim market share amid rising competition, particularly from U. S. shale producers. This realignment follows a strategy change observed across May, June and July, a pivot away from enforced cuts towards restoration of production volumes.

Internal friction persists

Tensions within the group continue, especially with Kazakhstan. The country’s June output reached record levels—1.88 million bpd—far exceeding its quota, as Chevron’s expansion at the Tengiz field ramped up operations. Other members, observing tighter compliance, have expressed frustration over these deviations. Observers suggest the bulk output increases serve multiple purposes: penalising over‑producers and deterring further deviations by rewarding compliant members.

Price and market reception

Brent crude recently edged lower, trading in the mid‑$60s per barrel, partly due to assurances that supply will remain ample, and also on uncertainties around U. S. tariff policy. Analysts at ING and Morgan Stanley expect prices to hover near $60‑$67, citing well‑supplied markets. Goldman Sachs forecasts a similar output increase at 0.41 mbpd and anticipates stable production after August, projecting average Brent prices around $60 in 2025.

HSBC, meanwhile, warned that ongoing supply hikes could push Brent below $65 in the fourth quarter, predicting mounting market surplus through 2026 and into 2027.

Strategic trade‑offs

OPEC+ appears to be walking a tightrope between market share expansion and price support. The rollout of successive supply increases challenges the group’s previous aim of bolstering prices. Analysts from Energy Aspects and RBC’s Helima Croft view this as a deliberate shift: smoothing out supply reductions to prevent erosion of influence, while retaining flexibility to respond to demand surprises.

Geopolitical context also features in the calculus. The group continues to factor in global uncertainties—such as U. S. tariff threats and geopolitical strains in the Middle East—into its supply decisions. Saudi Arabia is expected to raise its official selling prices to Asia in August, even amid the production uptick, reflecting efforts to defend revenue amid market volatility.

Looking ahead, market watchers will scrutinise whether all eight members will fully support the proposed increase—or whether some seek a more aggressive supply push above the already ambitious 411,000 bpd figure.

Court filings in the Chapter 11 case for collapsed exchange FTX suggest that users in 49 jurisdictions may see their claims disputed or denied over local crypto restrictions. A filing submitted on 2 July to the Delaware bankruptcy court outlines a new “hold‑and‑review” process, halting distributions to users in areas with bans on crypto trading or restrictions on offshore platforms.

FTX’s trustee, along with legal counsel, will evaluate whether paying out creditors in these jurisdictions violates local laws. Notices will then be issued to affected users, granting them at least 45 days to challenge their classification. Absent a timely response, claims and any accrued interest will be forfeited to the estate.

Although users in these 49 jurisdictions represent just 5% of approved claims, the financial exposure is heavily weighted. Over 82% of that total value originates from mainland China. China accounts for the vast majority of claims in what FTX labels “potentially restricted jurisdictions”. Advocates warn that most Chinese claimants may not recover any funds.

FTX’s court motion says it will seek legal opinions for each jurisdiction before approving any payout. If counsel concludes local law prohibits the disbursement, those claims will be formally challenged. The legal framework treats such claims as “disputed,” pending approval or denial of their status. Distributions will be suspended until those claims are resolved.

Affected users must submit sworn statements confirming acceptance of US court jurisdiction to pursue objections. Upon objection, the trustee will petition the court to determine if exclusion is justified. Lack of objection will result in automatic forfeiture.

The list of 49 jurisdictions includes not only China, but also countries such as Nigeria, Russia, Egypt, Saudi Arabia, Andorra, Fiji and Zimbabwe. That breadth reflects the wide global footprint of FTX prior to its collapse.

Chinese users have responded with alarm, exploring legal avenues in the US. One affected claimant, identified as “Will,” told media that though the crypto ban in mainland China prevents trading, holdings remain legal and ownership rights should entitle them to fiat reimbursement in US dollars. He has engaged a New York attorney to counter FTX’s position on wire transfers and jurisdictional exclusion.

Some creditors are studying whether to transfer or sell their claims through entities in compliant jurisdictions, though it remains unclear whether such mechanisms will resolve legal barriers.

FTX Recovery Trust reported an overall decline in disputed claims—from US $6.5 billion to US $4.6 billion—after approving $1.8 billion in claims and expecting another $2.7 billion to be cleared. Approved claim distributions have reached approximately $8.3 billion. This new policy specifically targets the subset linked to restricted jurs, leaving billions in limbo.

Legal experts suggest the court’s decision could set precedent for how bankruptcy courts manage cross‑border crypto claims when local compliance is at risk. FTX is therefore seeking judicial approval to formalise this tailored procedure.

Critics argue the move undermines proportional equity. Victims from major markets like China, Nigeria and Egypt, who collectively hold substantial unrationalised stakes, now face potential complete exclusion. These developments raise concerns about transparency and fairness in the global recovery process.

FTX’s reorganisation plan approved in October 2024 allows repayment of up to US $16.5 billion to customers. It prioritises accounts holding US $50,000 or less under the terms of the Chapter 11 order, but regional legal hurdles may override the general scheme.

Trustee Sunil Kavuri summarised that each claim will proceed only with a supportive local legal opinion. If the opinion concludes a payout contravenes domestic laws, the claim will be formally disputed and may be permanently disallowed.

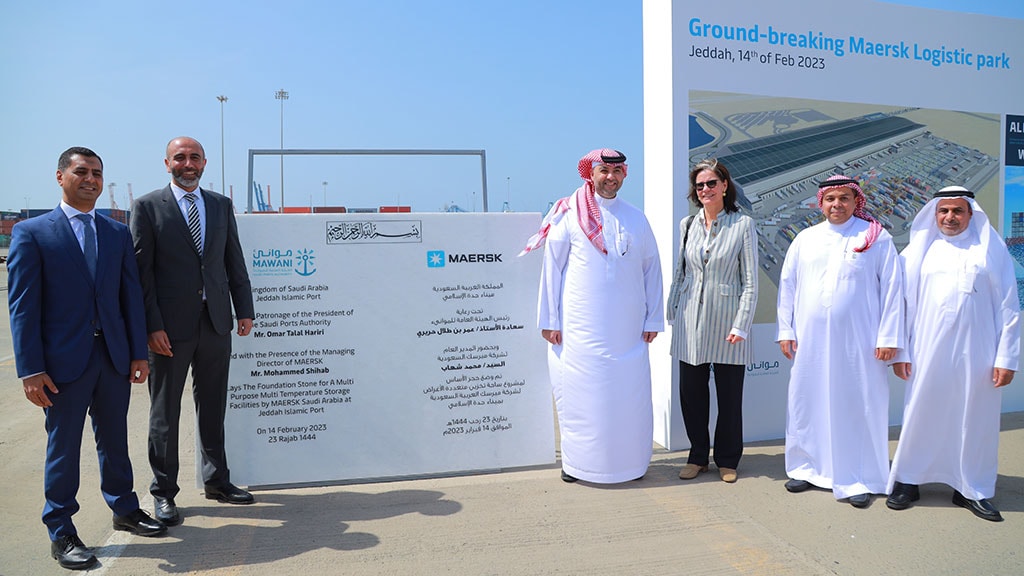
Saudi Arabia’s burgeoning e‑commerce sector has taken a strategic leap forward as the landmark partnership between Maersk Saudi Arabia and Saudi Post transitions from agreement to action. Evidence is already emerging that this alliance—anchored by Maersk’s newly launched Integrated Logistics Park in Jeddah—is beginning to streamline the kingdom’s supply chains and attract international players.

Operations in Jeddah have officially begun, with Maersk overseeing global transport, bonded warehousing, and origin-end logistics, while SPL manages express customs clearance and last-mile delivery domestically. The MoU, signed on 3 July 2025, outlines joint digital integration, combined marketing, coordinated customer service and operational efficiency.

Industry sources suggest that several multinational online retailers are in advanced talks to leverage the new gateway. Although specific names have been withheld, analysts view the integrated model as particularly attractive to Asia‑based brands seeking fast, low‑cost market entry into Saudi Arabia and the wider Gulf Cooperation Council.

Experts highlight that Maersk’s global reach combined with Saudi Post’s local footprint addresses major bottlenecks in cross-border trade—namely customs delays and fragmented distribution networks. SPL’s national infrastructure, originally developed to support Vision 2030’s economic diversification goals, now aligns seamlessly with Maersk’s logistics corridors.

Karsten Kildahl, Maersk’s Chief Commercial Officer, previously noted that global supply chains remain unpredictable, and enhanced visibility and resilience are crucial for upstream customers. This partnership directly supports those objectives via real‑time digital tracking, automated handovers, and unified service teams.

Market response has been swift. Regional logistics analysts report a 15% increase in inbound parcel volumes through Jeddah’s port cluster in the past month compared to the same period last year. While other factors—such as seasonal demand shifts—are at play, the increase aligns with the ramp‑up of cross-border operations facilitated by the Maersk–SPL alliance.

Customs officials in Jeddah confirm expedited clearances under a “premium e‑commerce lane” established within the SPL framework. They say this streamlining has shaved several days off processing times for inbound B2C shipments, helping foreign brands meet tight delivery schedules.

Saudi Post’s International Business Sales Director, Rouni Saad, stated the arrangement “is pivotal in streamlining cross‑border e‑commerce flows to and from the Kingdom … enhancing connectivity, reliability and growth opportunities across the region”. Maersk’s Ahmed Al Olaby added that combined networks would meet the growing demand for efficient fulfilment by global players entering or expanding in the Saudi market.

Consultants note that Saudi Arabia is now positioned to compete more effectively with regional hubs such as Dubai, which has long served as the GCC’s principal logistics centre. With the integrated infrastructure online, analysts predict intra‑GCC e‑commerce flows will re‑route through Jeddah over the next six to twelve months.

The alliance also aligns with Saudi Vision 2030, reinforcing the kingdom’s commitment to modernise its logistics backbone. By linking global ocean routes with domestic delivery channels, the partnership promises smoother, faster access to consumers in a market anticipated to grow double‑digit annually in e‑commerce sales.

However, questions remain around digital interoperability. The MoU commits to systems integration, but execution will depend on effective collaboration between both entities’ IT architectures. Some industry insiders stress the need for standardised APIs and seamless data sharing to avoid fragmentation.

Scaling services beyond major urban centres, and replicating integration in other GCC markets, pose additional challenges. Achieving cohesive bonded fulfilment across borders demands regulatory alignment and bilateral coordination.

The Abu Dhabi Securities Exchange has initiated the pricing phase for the MENA region’s first bond underpinned by distributed ledger technology, marking a new era in regional capital markets. The fixed-income instrument, issued by First Abu Dhabi Bank via HSBC Orion, is set to be listed on ADX, promising enhanced operational efficiency, transparency and market access. ADX, the UAE’s largest exchange and the second-largest in the Middle […]

Matein Khalid Both Israel and the US were careful not to target Iran’s oil export terminal at Kharg Island, a major reason why Brent crude trades at 68 and not 100. It is ironic that Iran’s oil output is now 5.1-MBD (this figure includes condensates and gas to liquids), its exact amount in 1978, the last year the Shah ruled from his Peacock Throne. There is no […]

VISHNU RAJA
RYO YAMADA
HITORI GOTOH
IKUYO KITA